Over the last few weeks, we have written:
Explosive Setup 5.0: 3rd October 2026.
Tech Winter 2.0: 10th October 2026.
Buy The Dips or Sell The Rip?: 17th October 2026.
As you can see, since the beginning of October, signs emerged that trouble was brewing in the cross-asset markets.
By 10th October, we also saw alarming signs that the “crowded” AI trade is on the verge of exploding, led by the Korean markets.
Last week, we warned paid subscribers about the AI trade, and our PF has been positioned for the anti-AI trade (though we were a month early).
There has been no letup in the credit markets; it’s absolute panic.
Oracle’s probability of default, per the CDS, is now on the verge of hitting 30%.
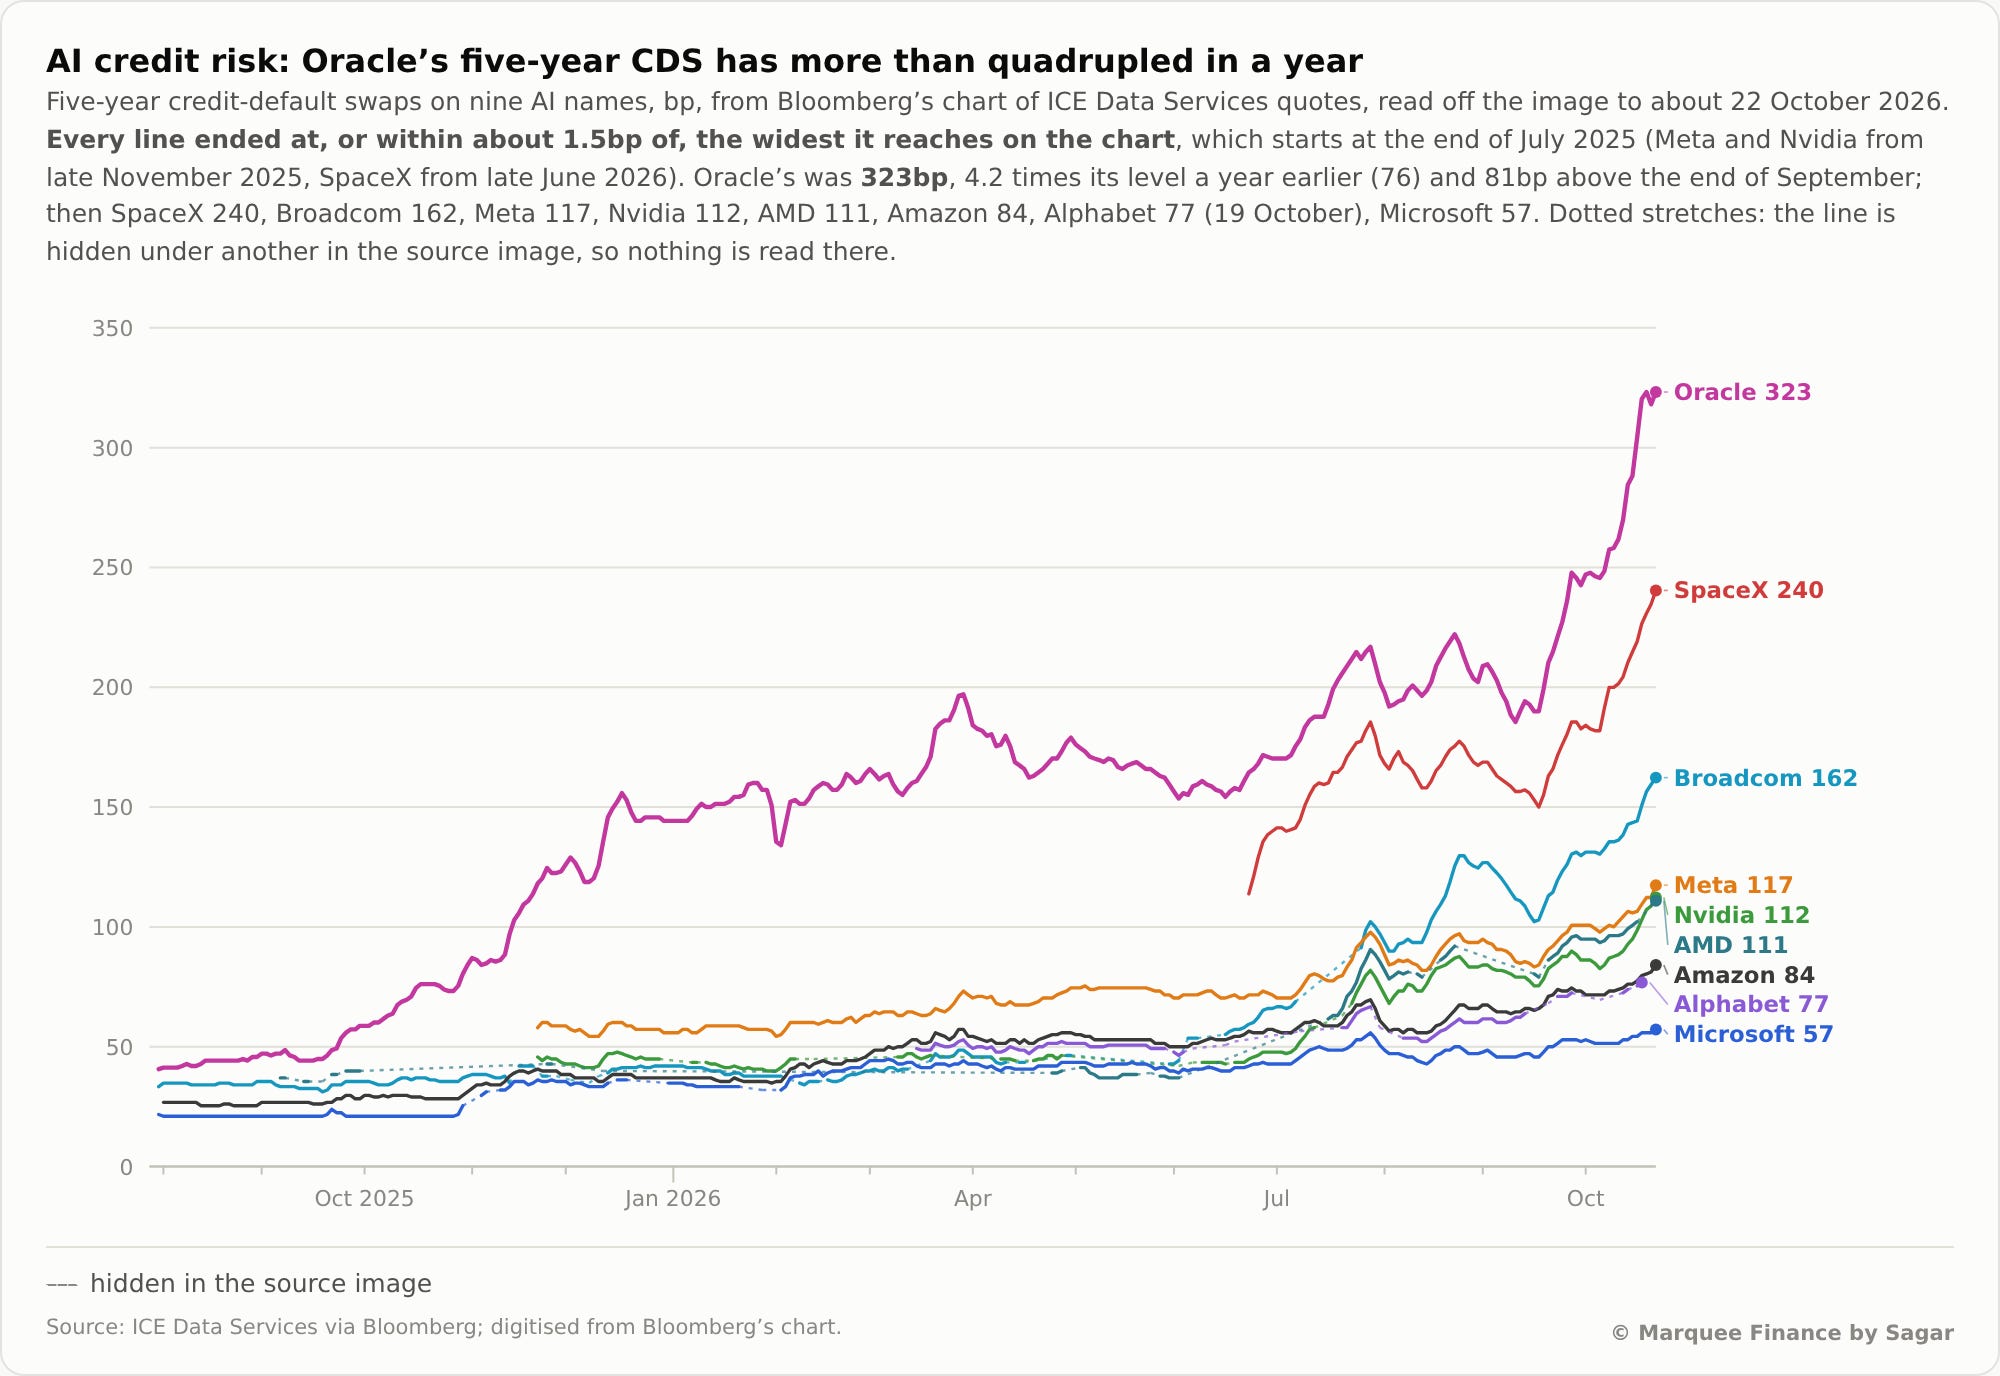
As a result, large equity and debt investors continue to hedge their exposure via CDS.
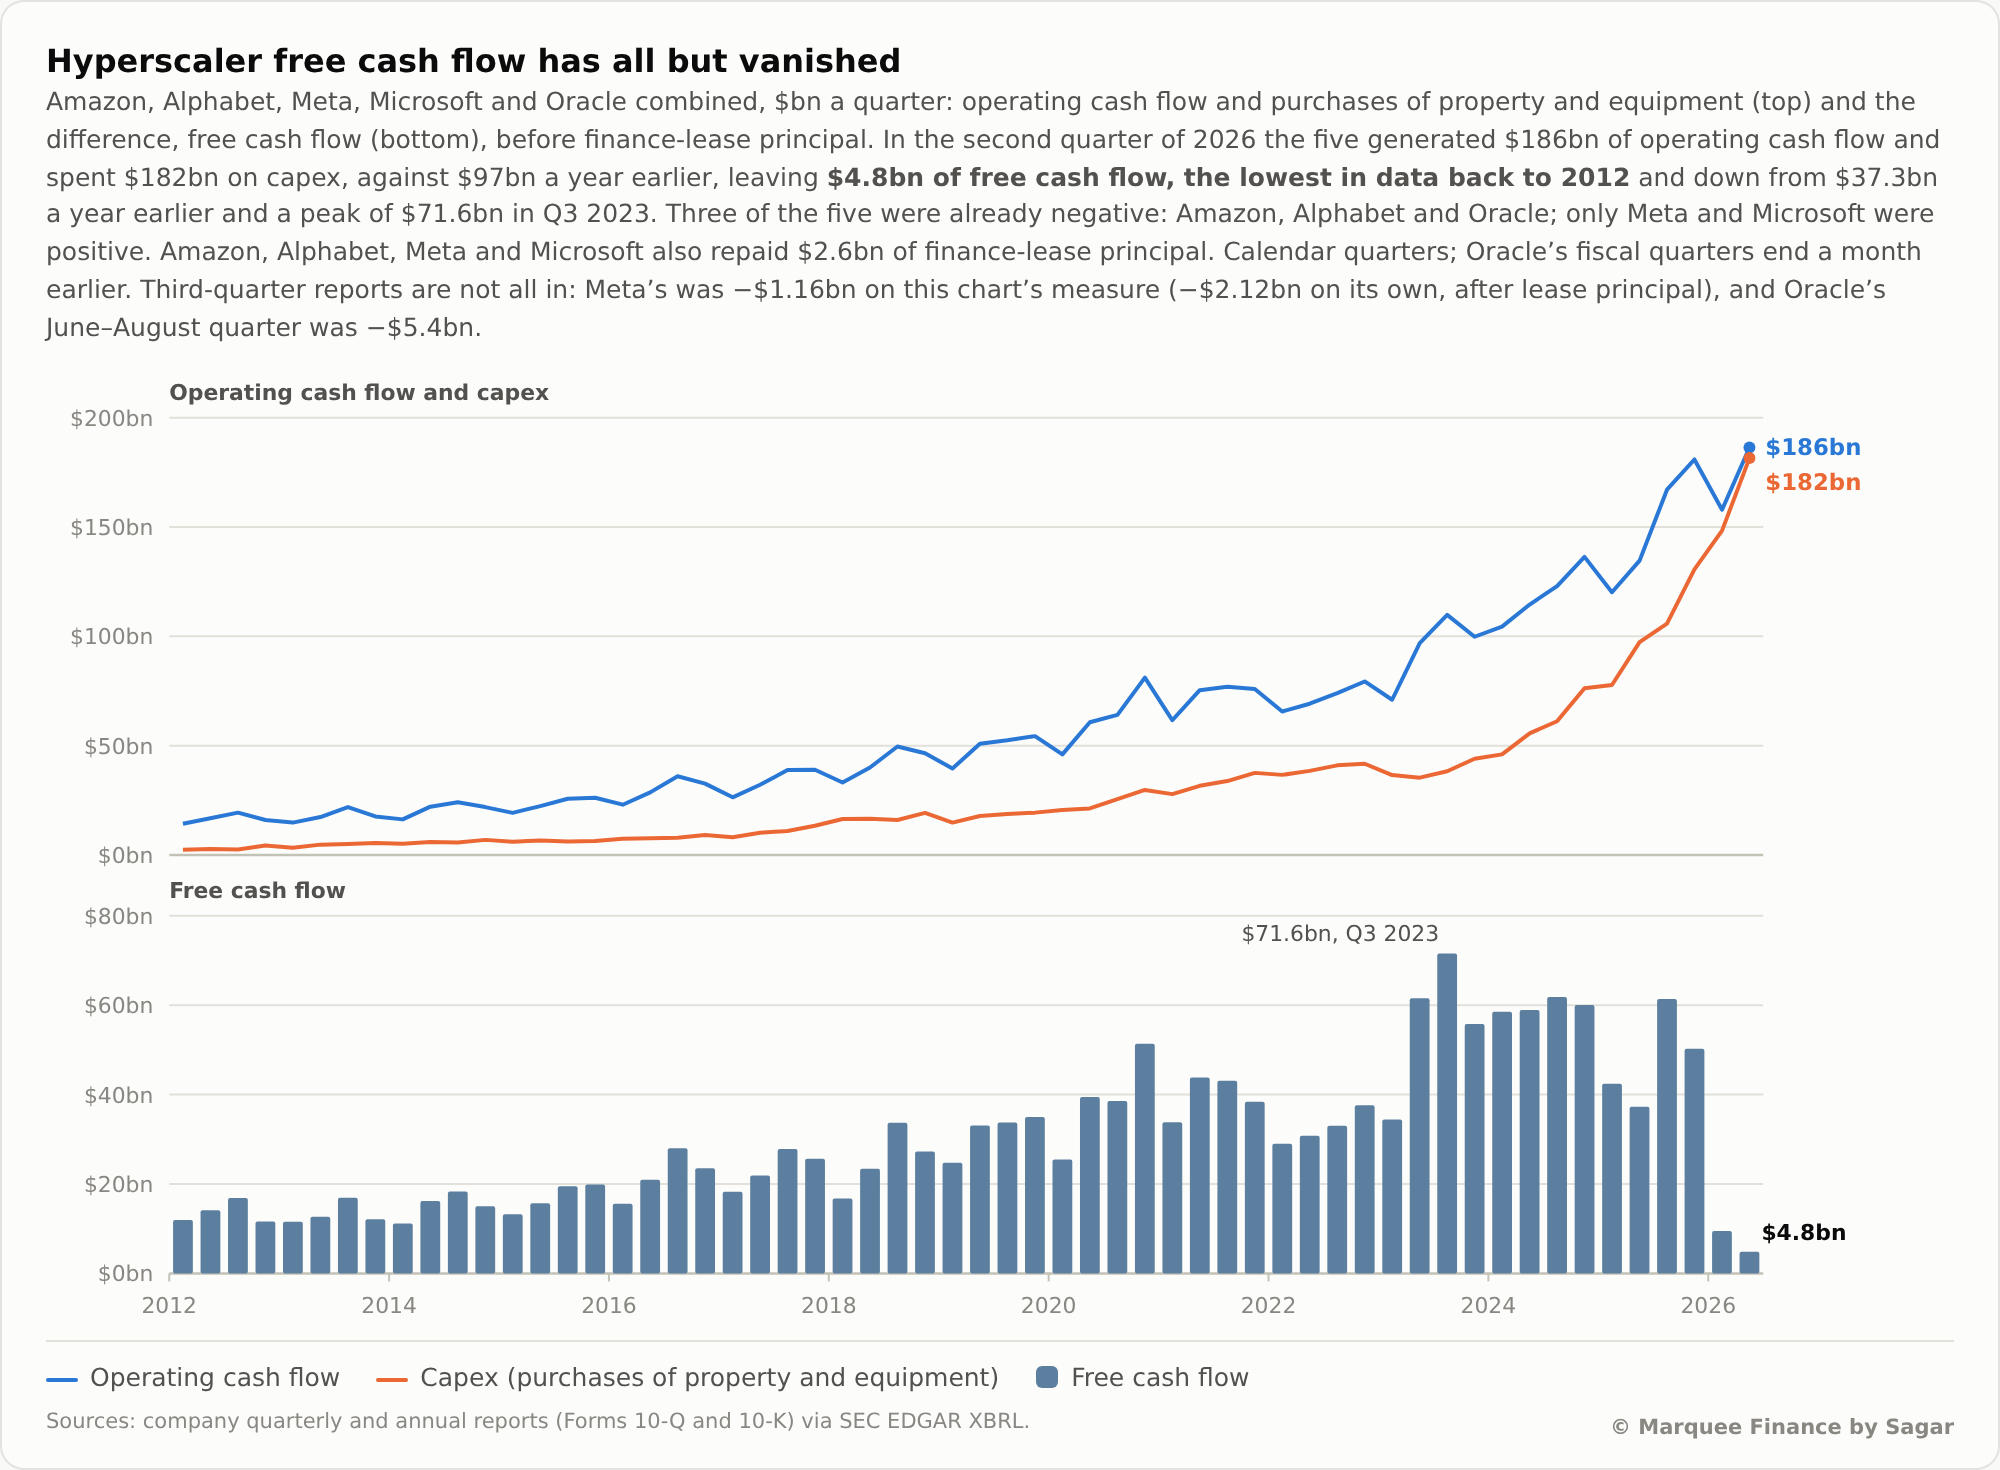
With credit markets frozen and the Free Cash Flows (FCF) of hyperscalers on the verge of turning negative (this quarter), the AI rollout hangs in limbo as the funding problem becomes the biggest issue (along with grid and power issues).
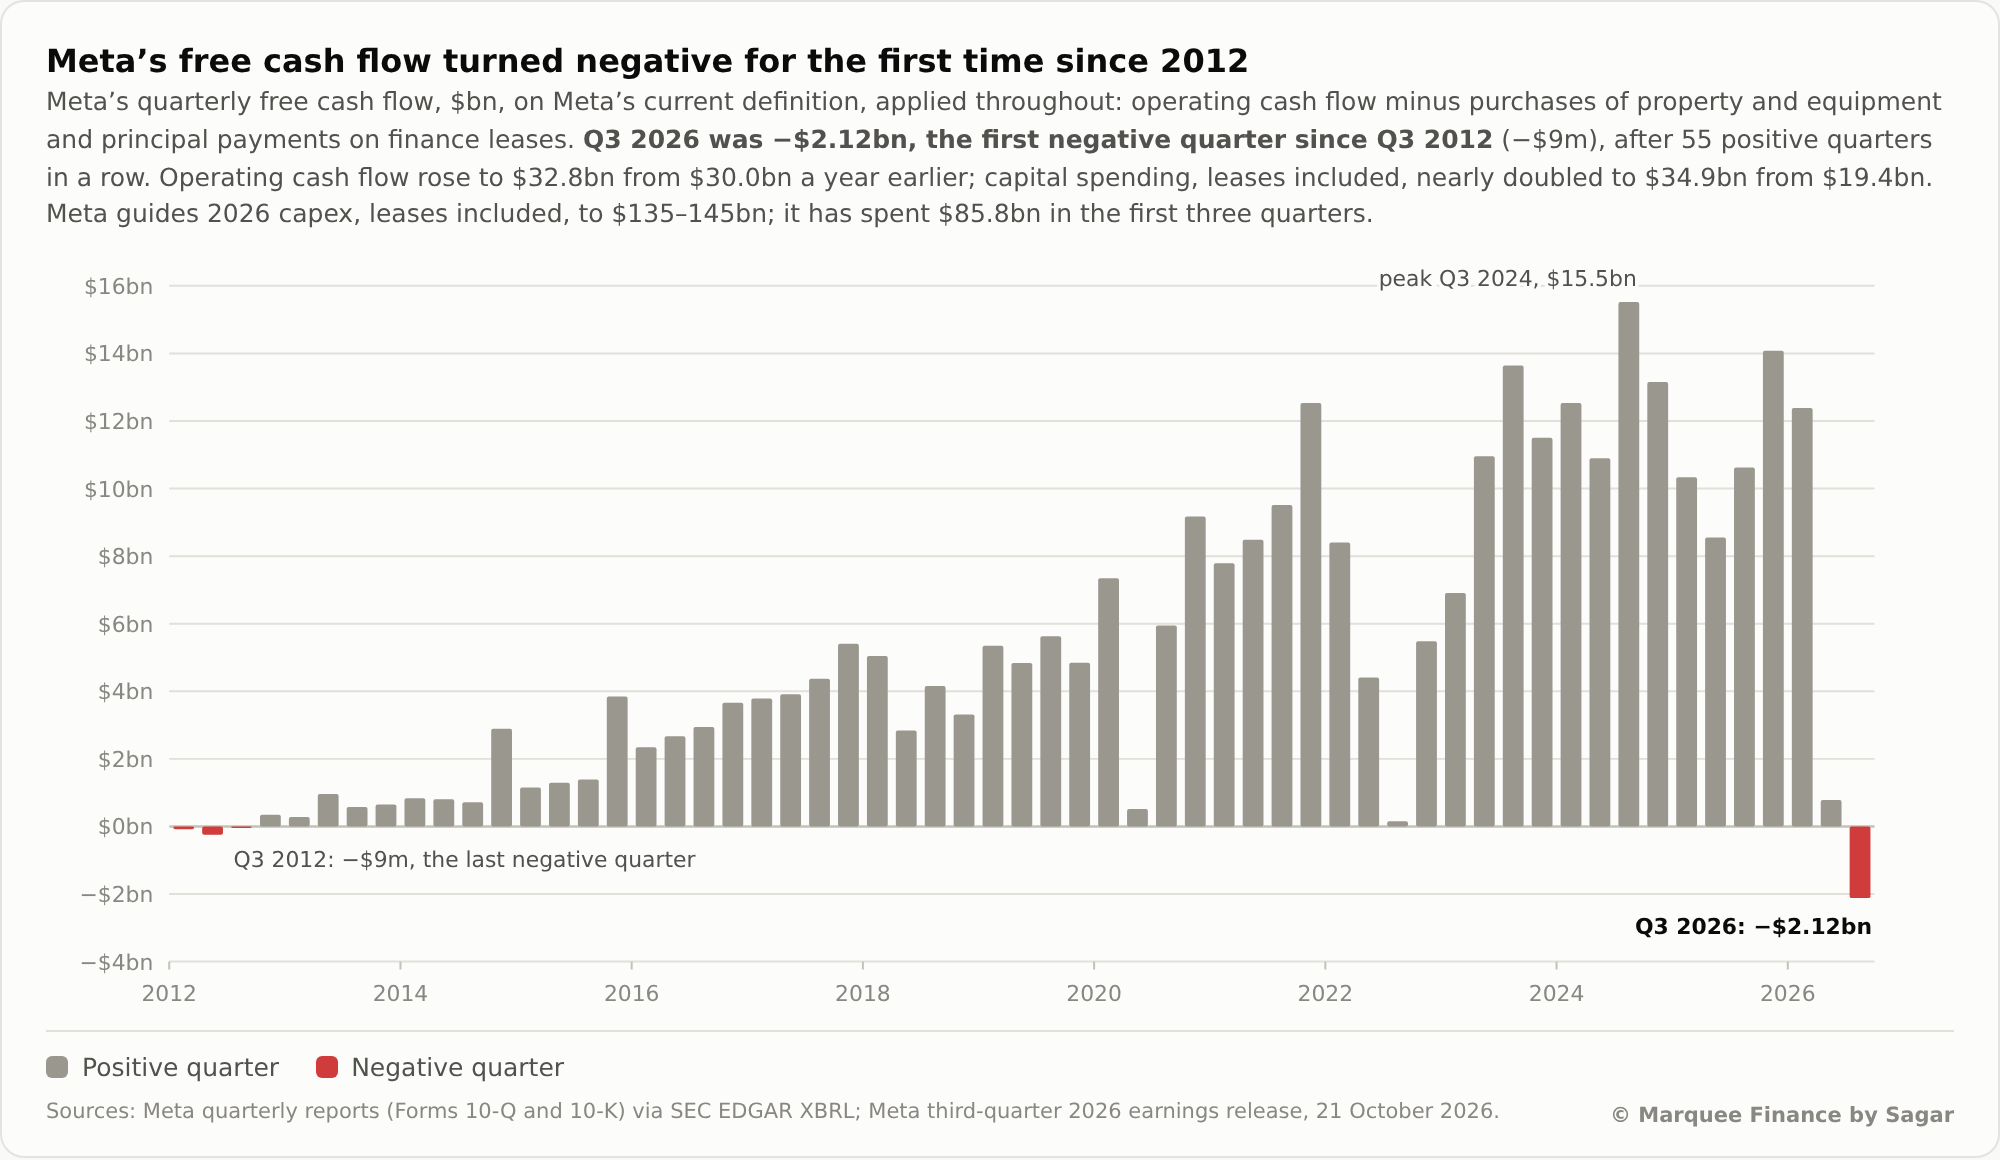
PS: Meta turned FCF negative for the first time this quarter.
On the other front, as open-source models gain market share and token prices keep falling, frontier-model companies' valuations have plunged.
Anthropic, which was vying for a $2 trillion valuation, is now looking at $1.5 trillion.
Furthermore, OpenAI's valuation for the next funding round ($30 billion) was cut from $1.4 trillion to $1.2 trillion.
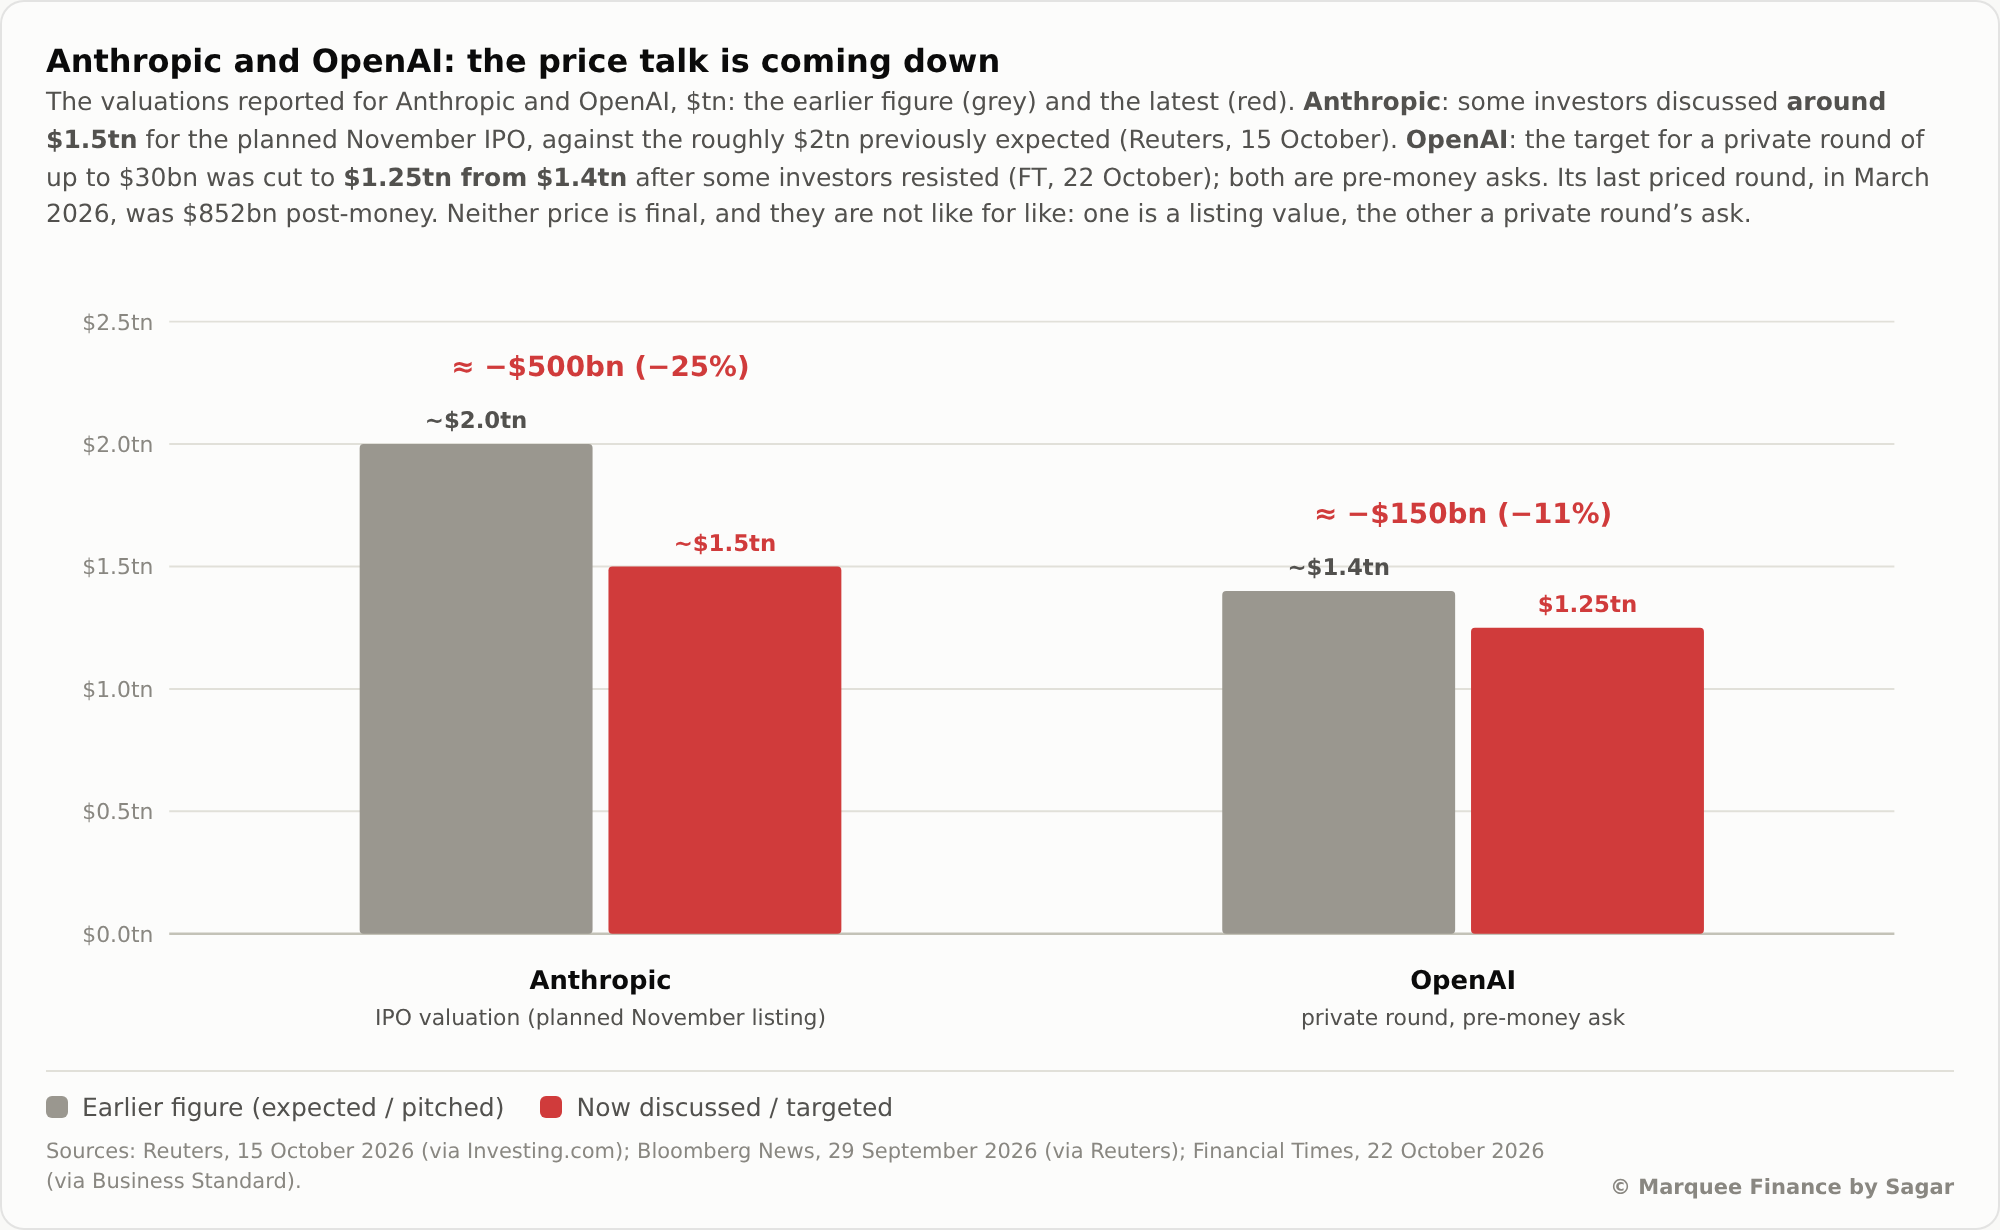
PS: AMZN and GOOG have reported large MTM gains on their investments in Anthropic; if valuations fall, expect them to book MTM losses, which will drive down EPS.
Global Macro Musings is ready for its soft launch, and paid subscribers will get access on Tuesday/Wednesday.
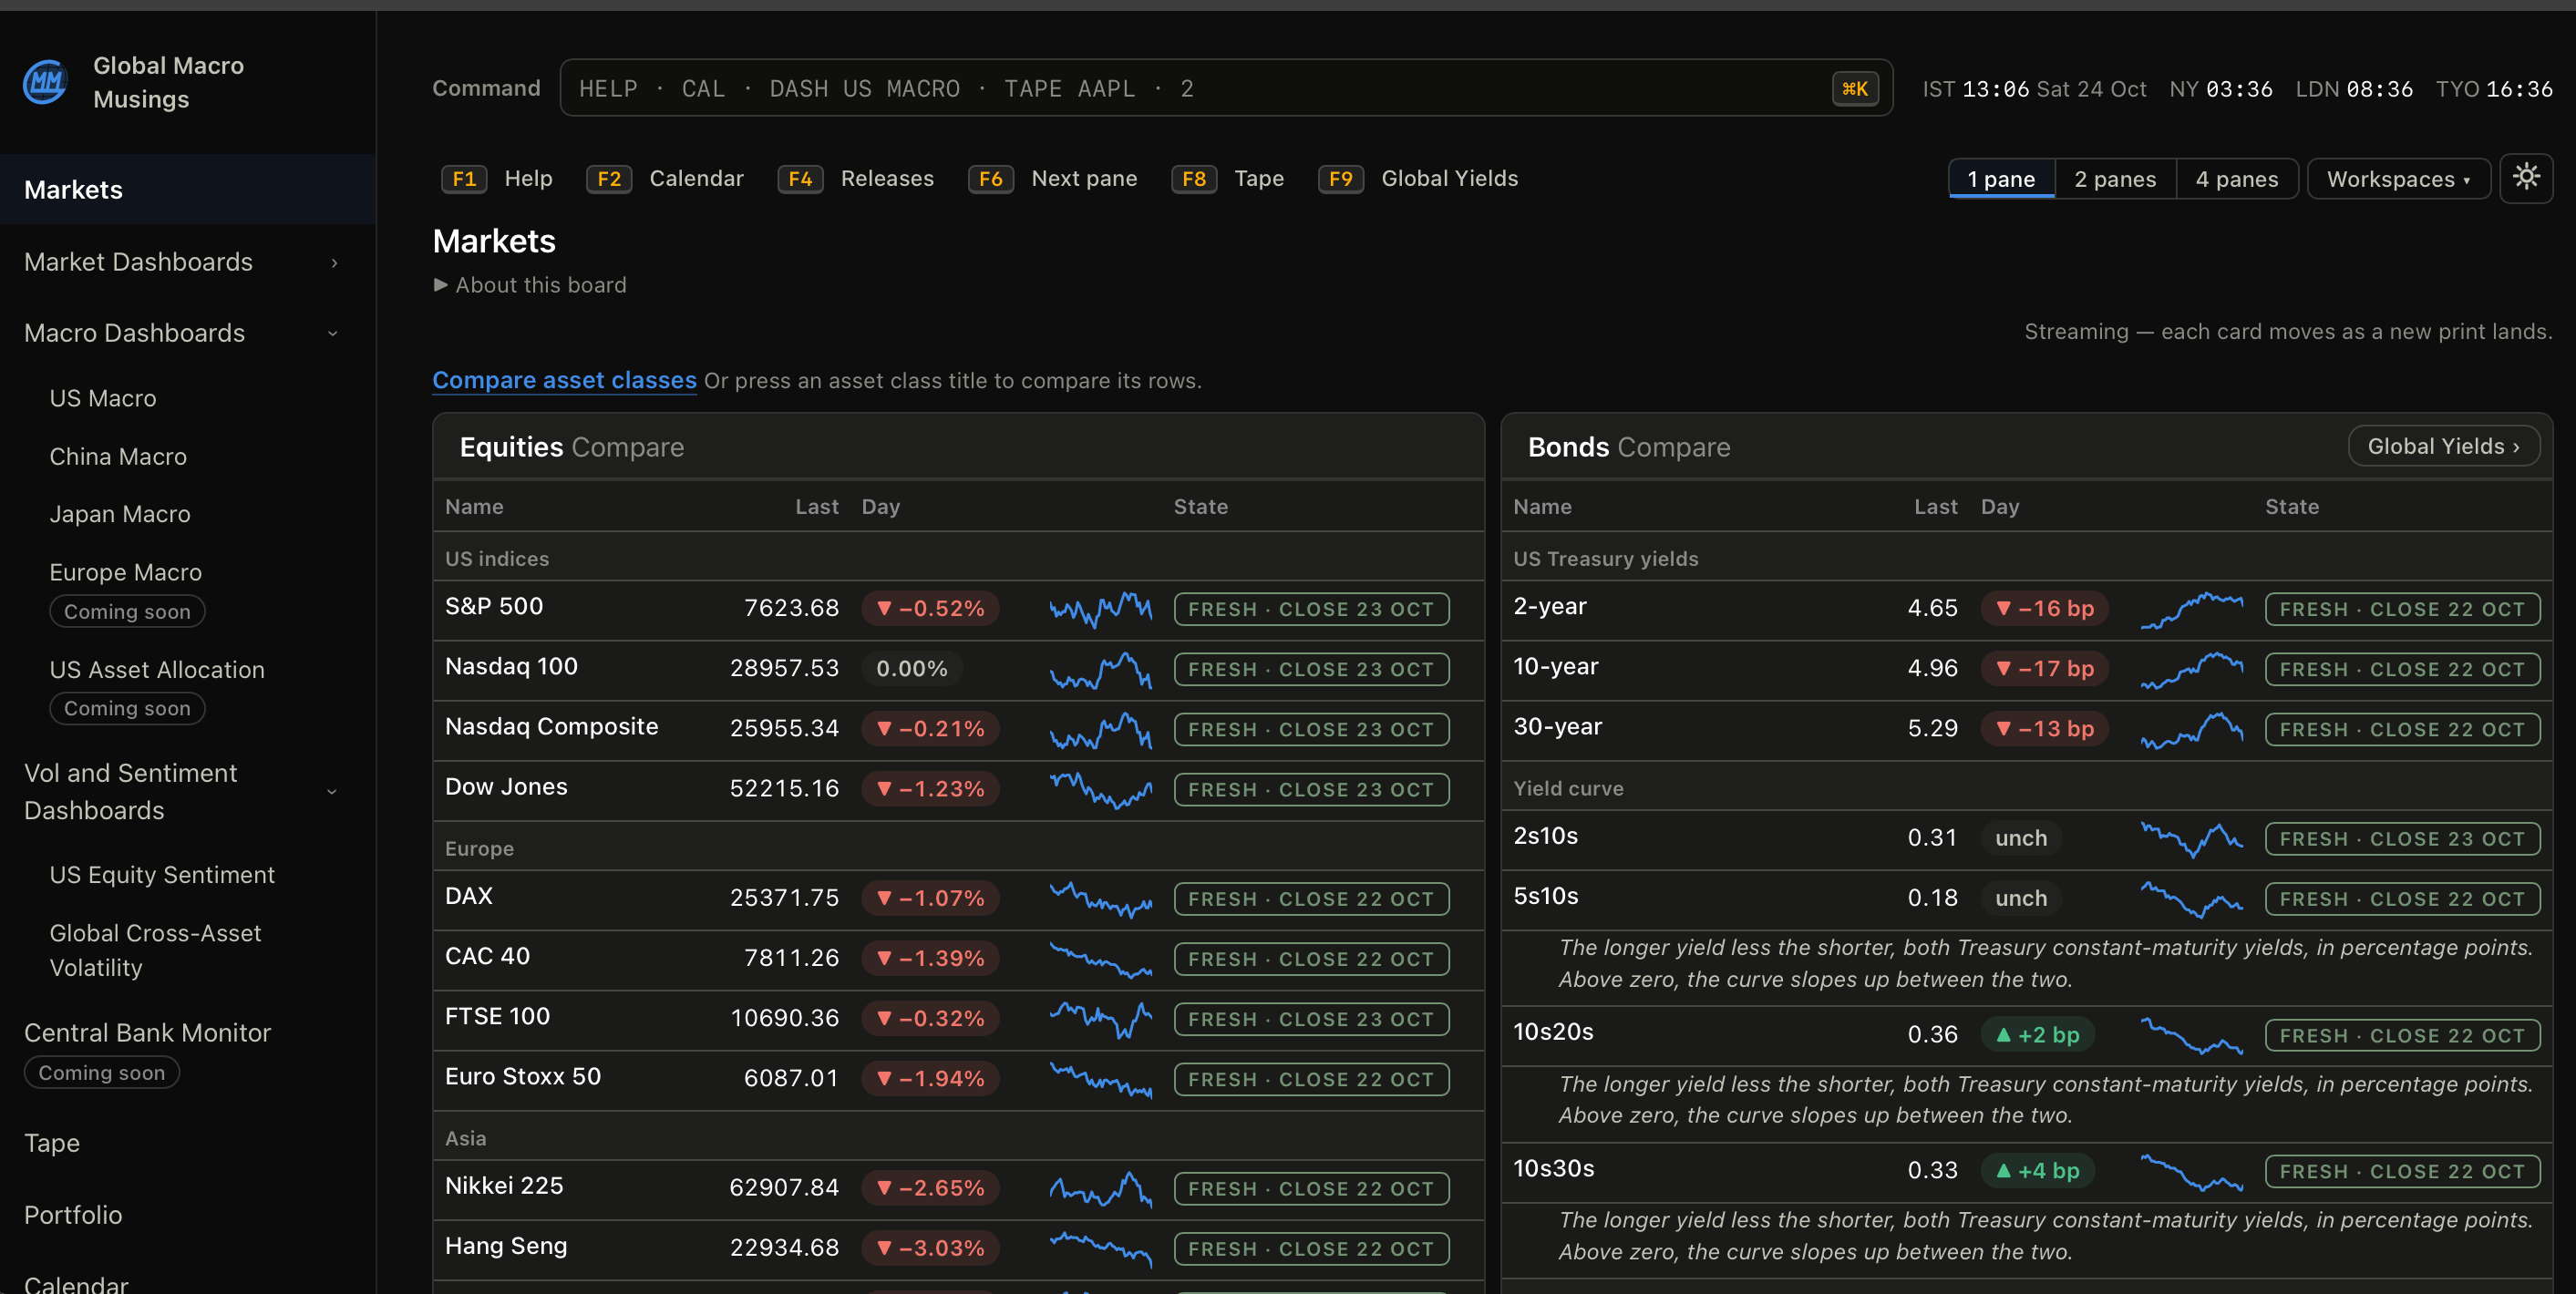
All other subscribers will get access to Global Macro Musings in a fortnight.
We are up 2% in September and have recouped 60% of the September losses.

We are up 5.63% YTD, and despite the tough market, we aim to deliver double-digit returns this year.
Let’s take a deep dive into the macro universe and comprehend the cross-asset market action.
US/Equities/Bonds/Gold & Silver/Oil/Dollar!
It's been a long time since we discussed housing data.
This week we will focus on the housing market. Long-time readers know we're big fans of Kantro’s HOPE model (Housing→ Orders→ Profits→ Employment).
Off-late, the housing market data has been deteriorating.
The rule here: Permits→ Starts→ Units Under Construction→ Completions.
Usually, this process takes 18-24 months (starting from permit application).
This week we got the permits data, and single-family permits are down to 845k while multi-family stands at 503k.
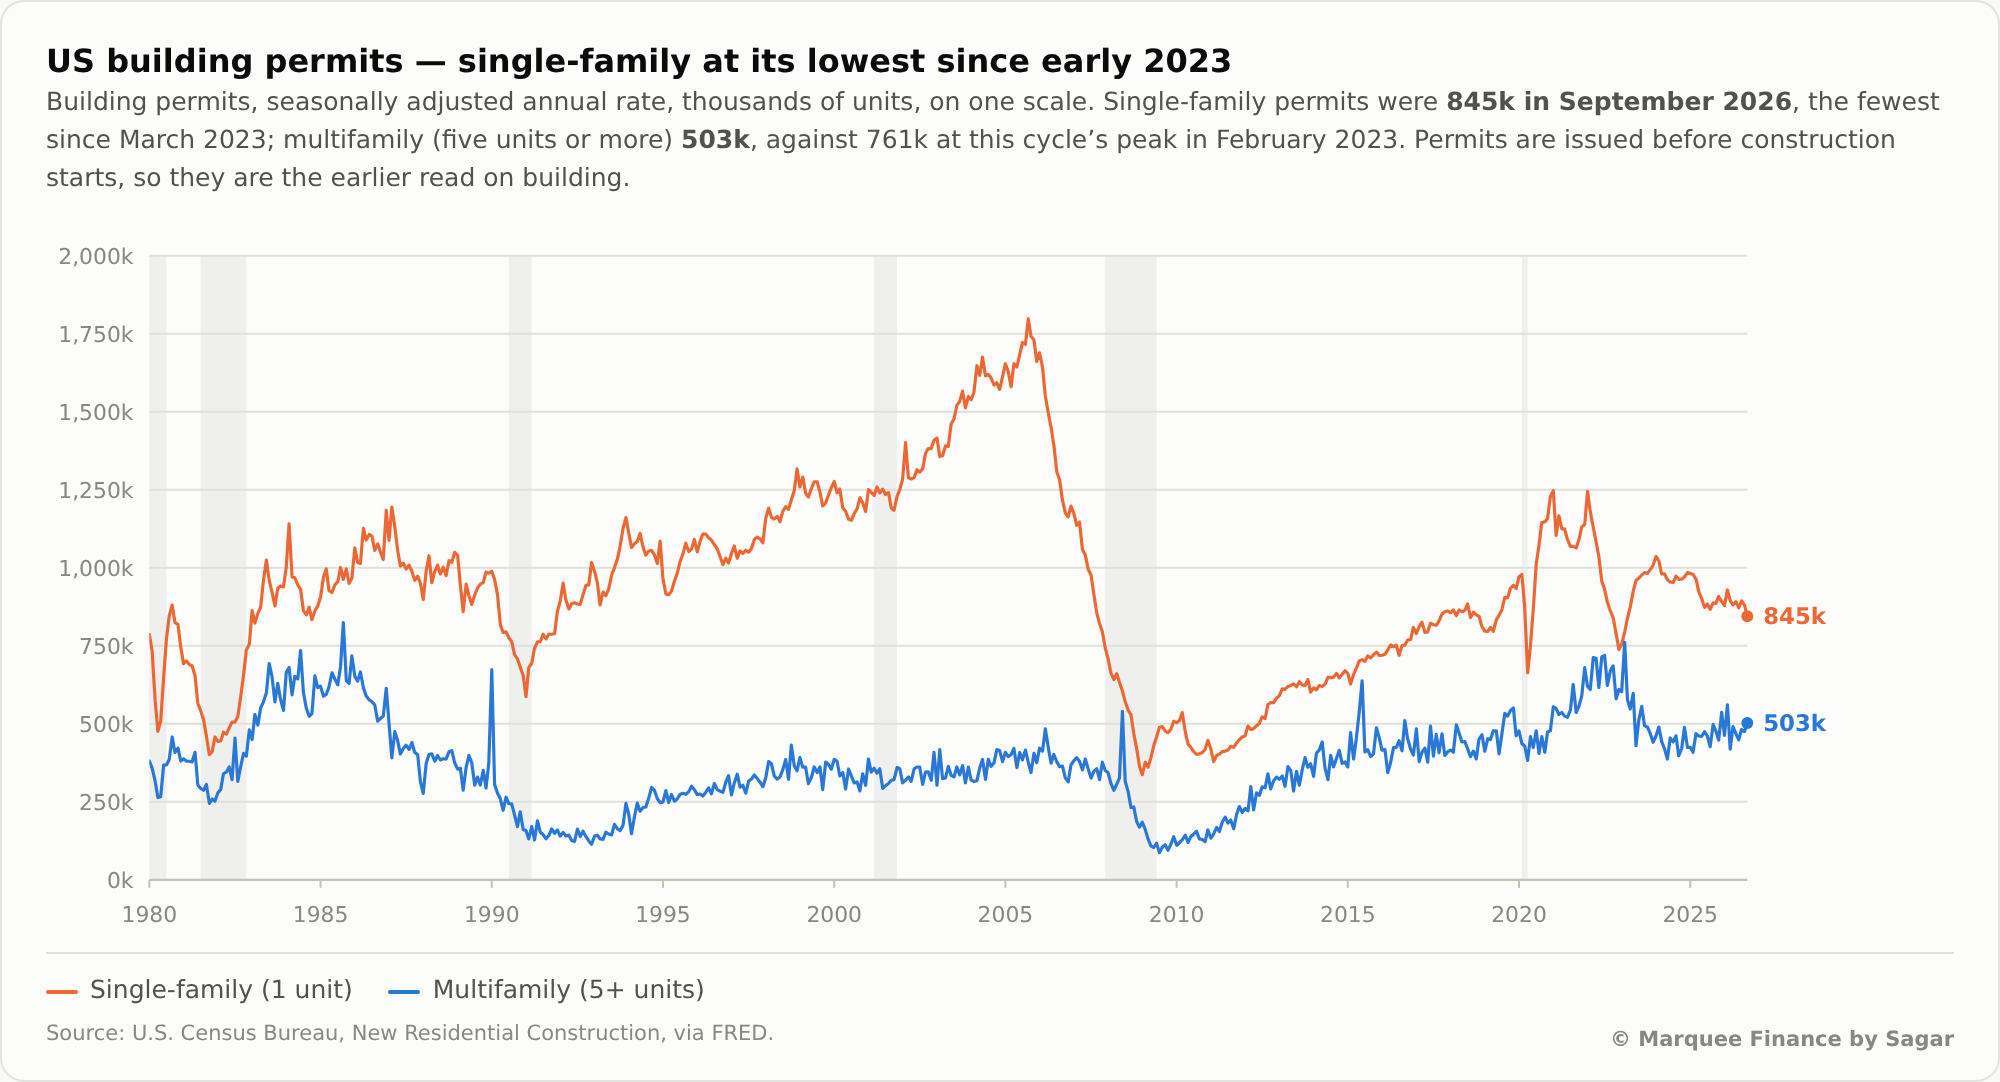
Single-family permits have fallen to levels last seen during the 2022 housing recession.
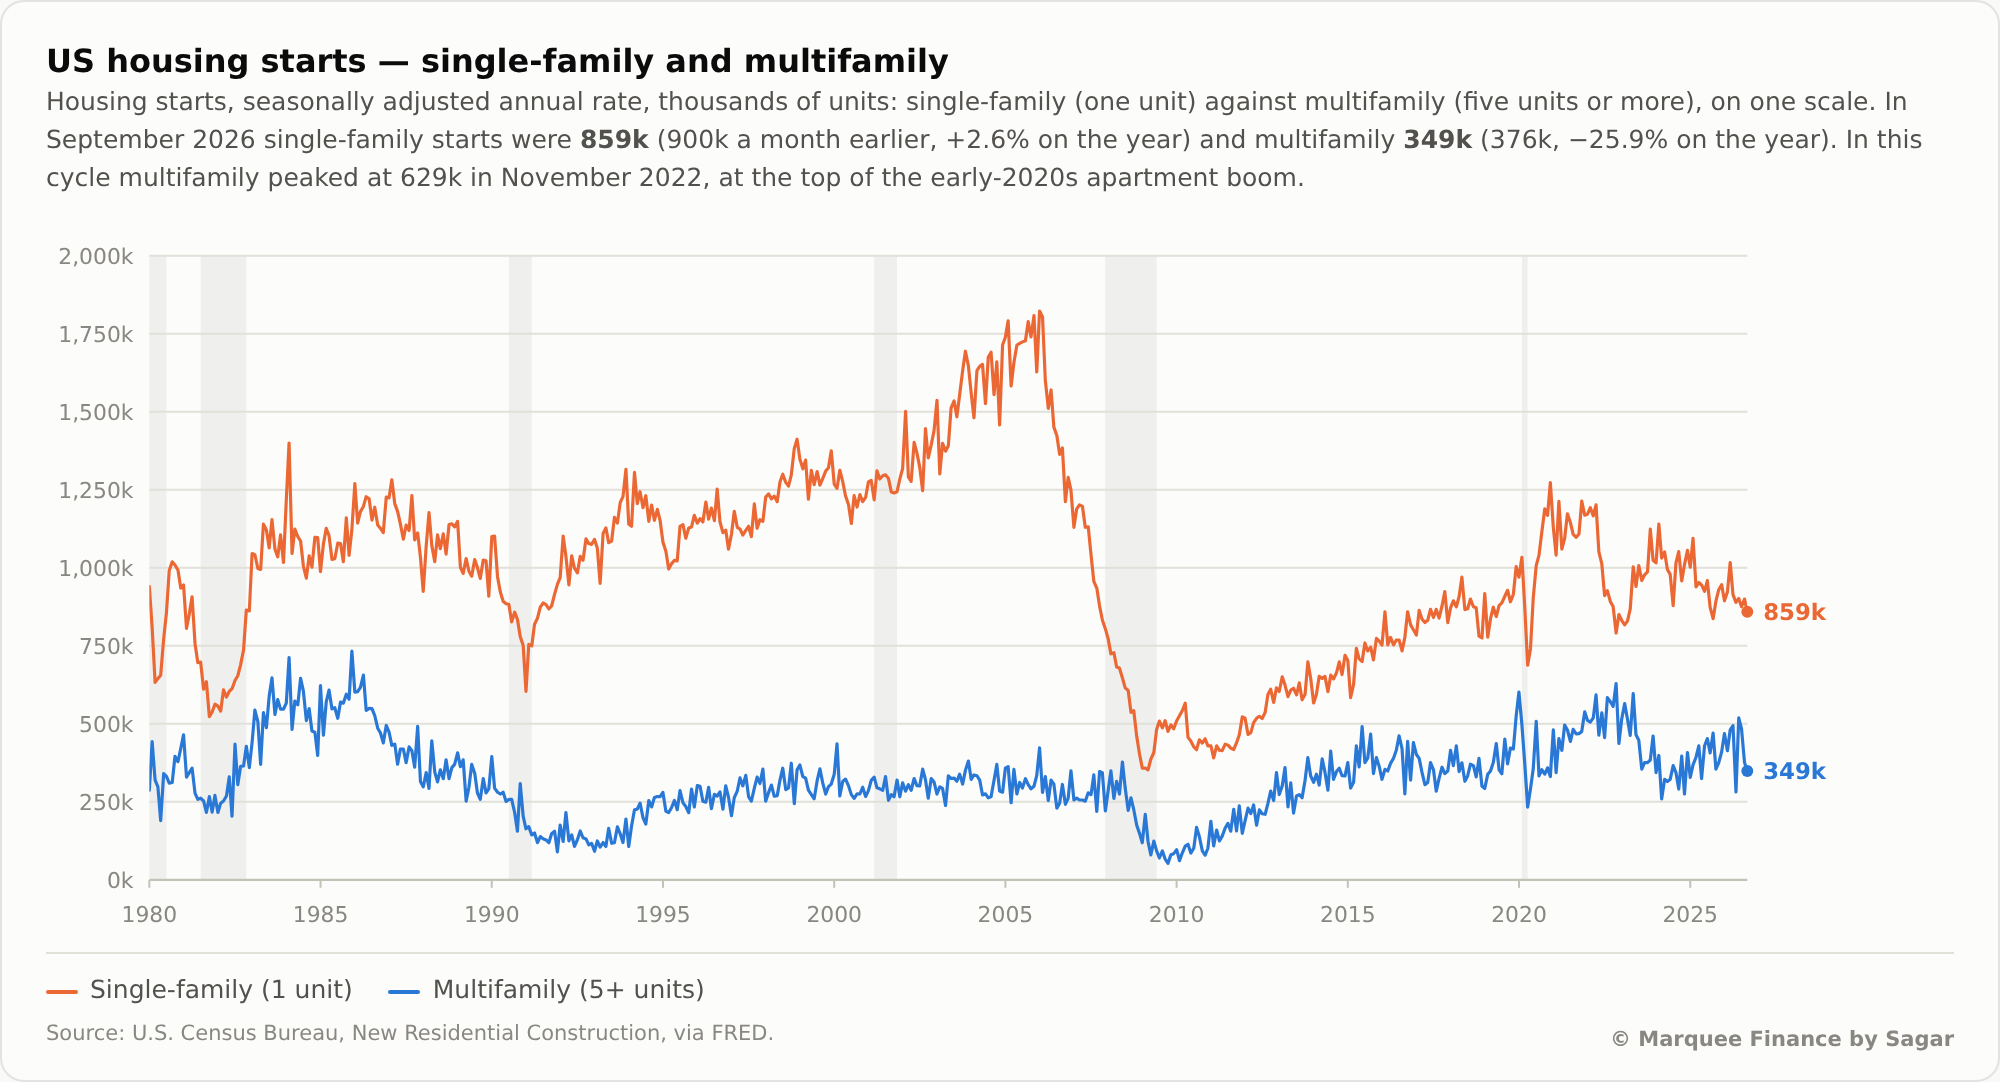
When we analyse starts, single-family has been trending down, and we expect it to fall further (as permits have collapsed).
Multi-family starts have also plunged.
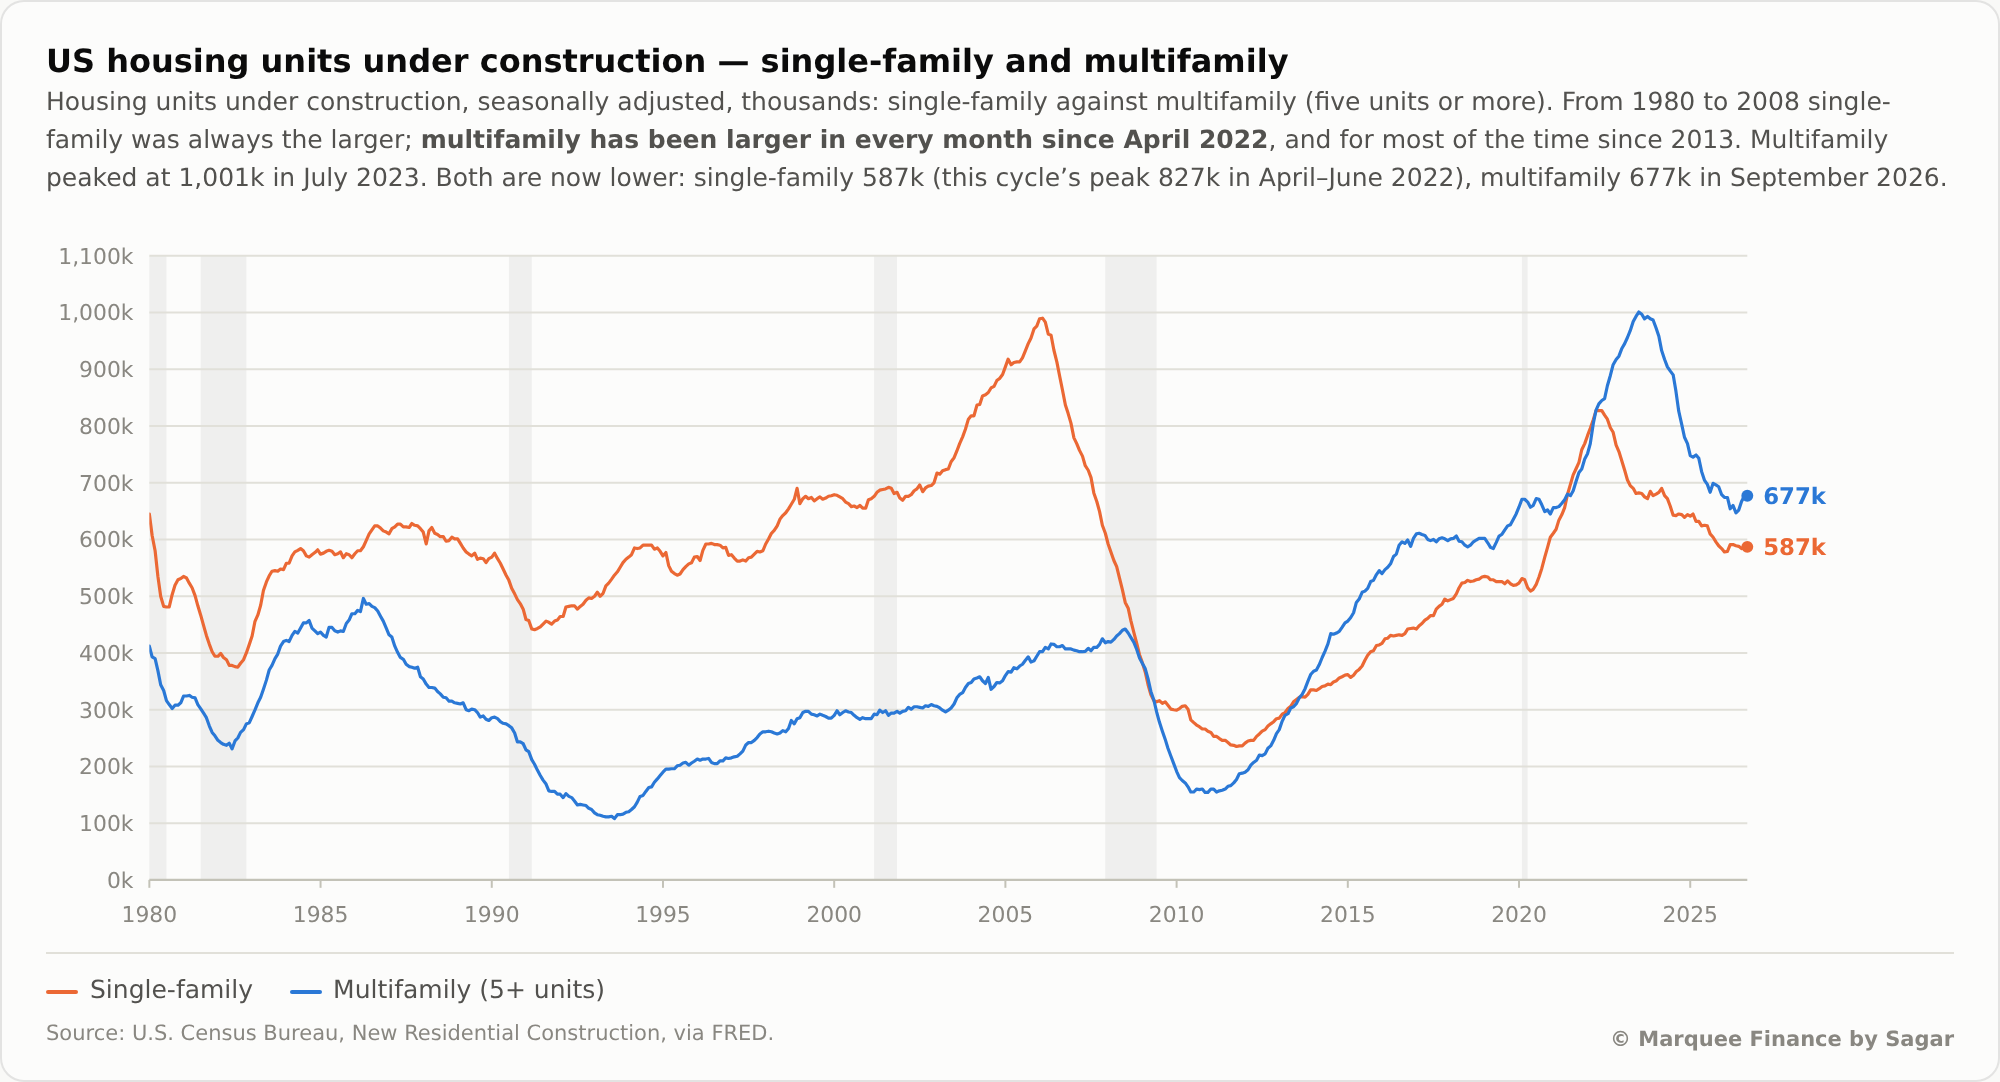
Single-family units under construction are expected to return to pre-COVID levels, given the lower starts.
On the contrary, units under construction for multi-family housing bottomed out late last year.
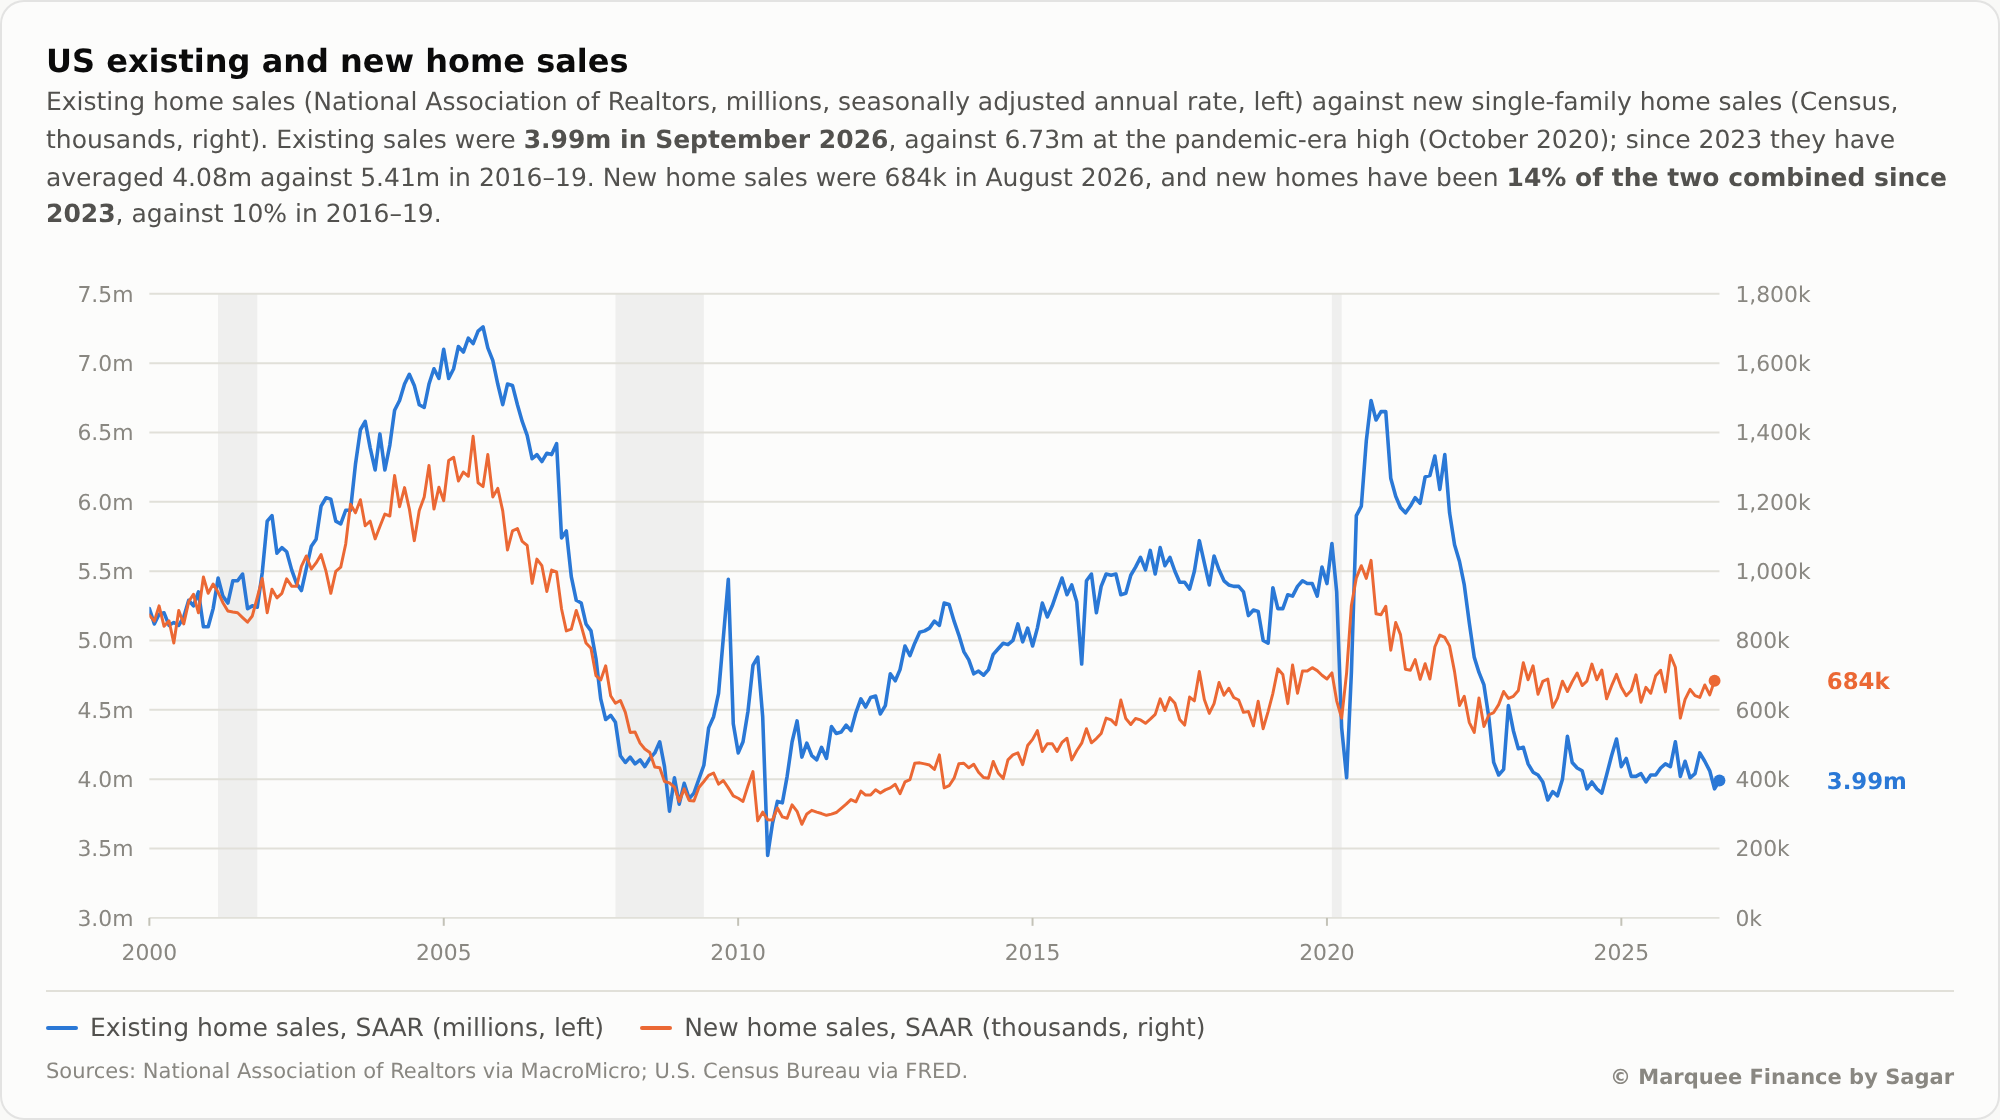
The most critical part of the housing market is sales.
Existing home sales have collapsed as sellers who locked in rock-bottom mortgage rates during COVID are reluctant to sell, while new home sales have been subdued (though they've recovered from the bottom) because of higher mortgage rates.
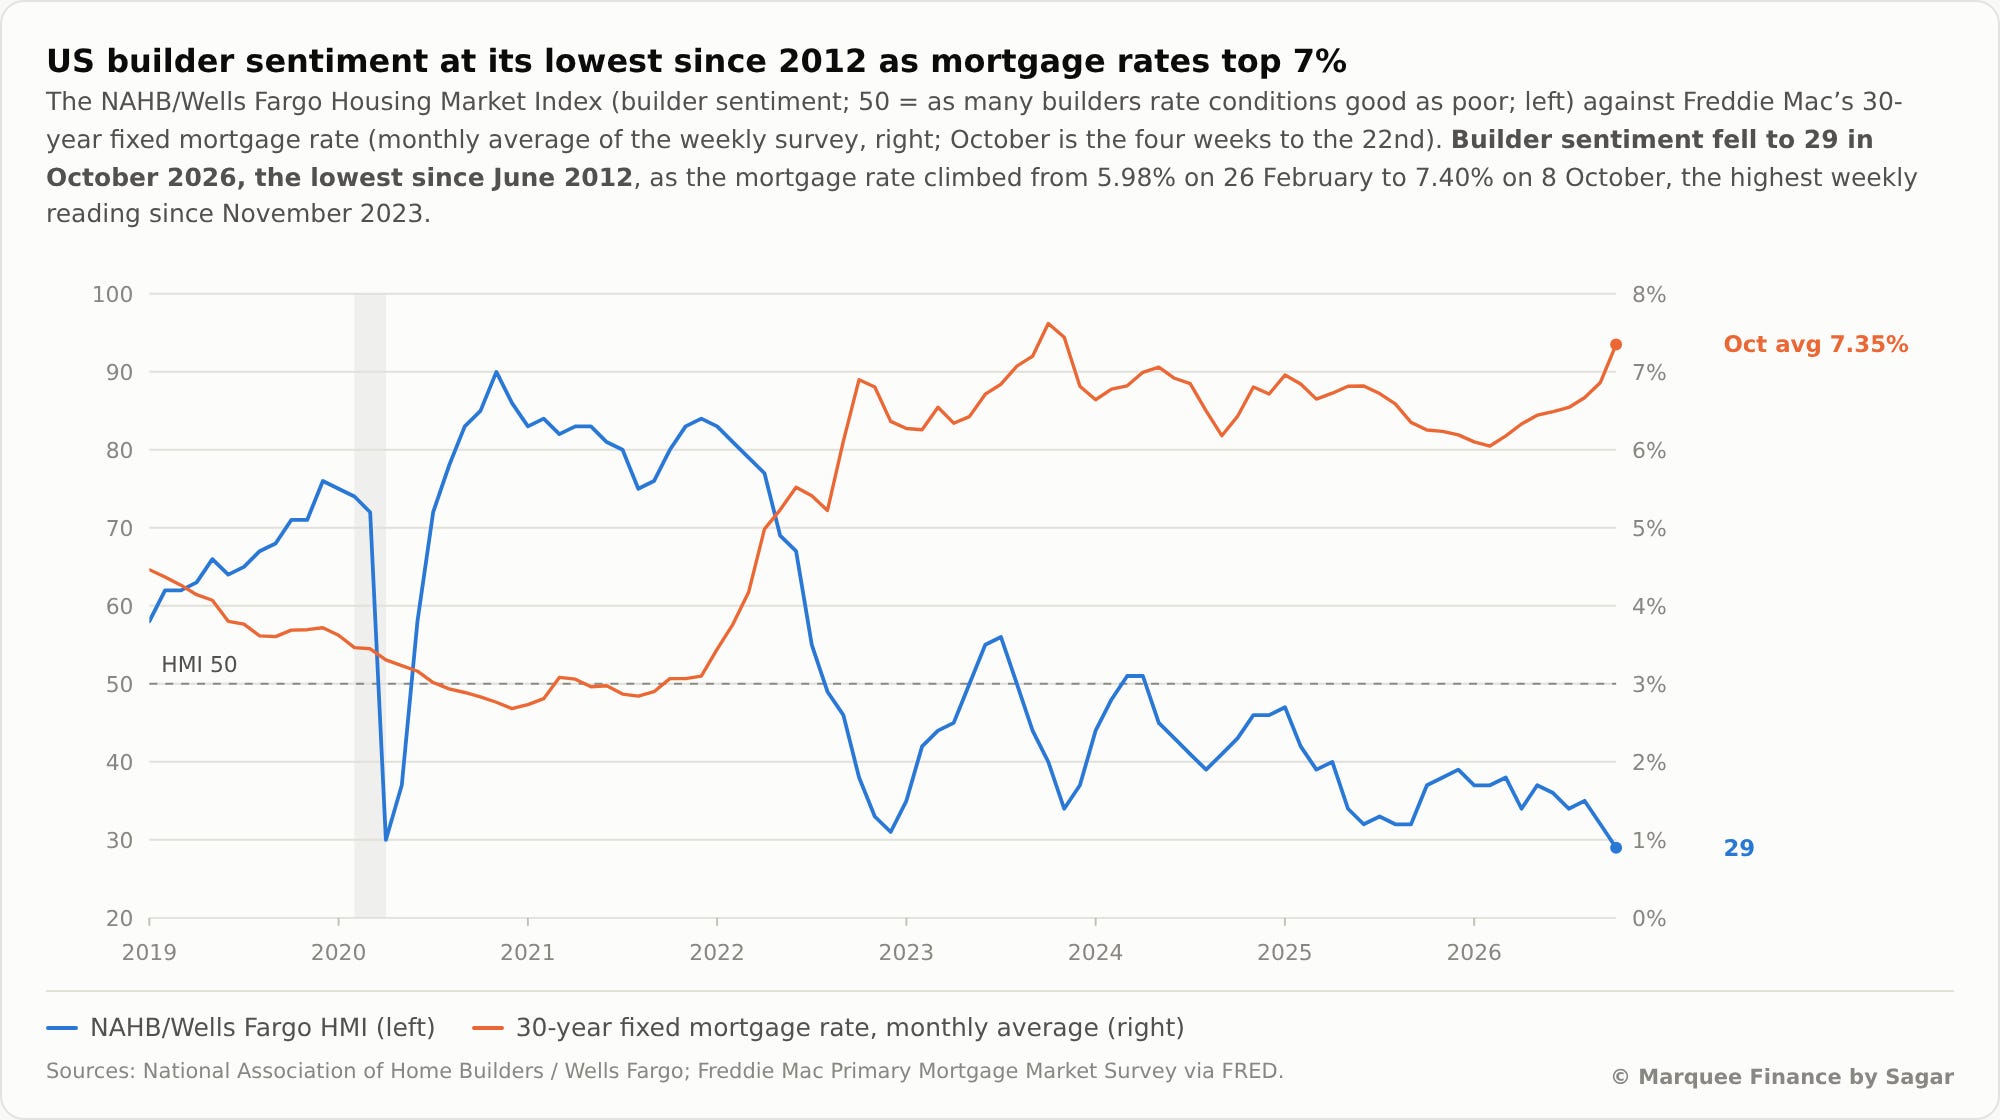
Builder sentiment has plunged to COVID levels, suggesting a frozen housing market because of higher mortgage rates.
Equities!
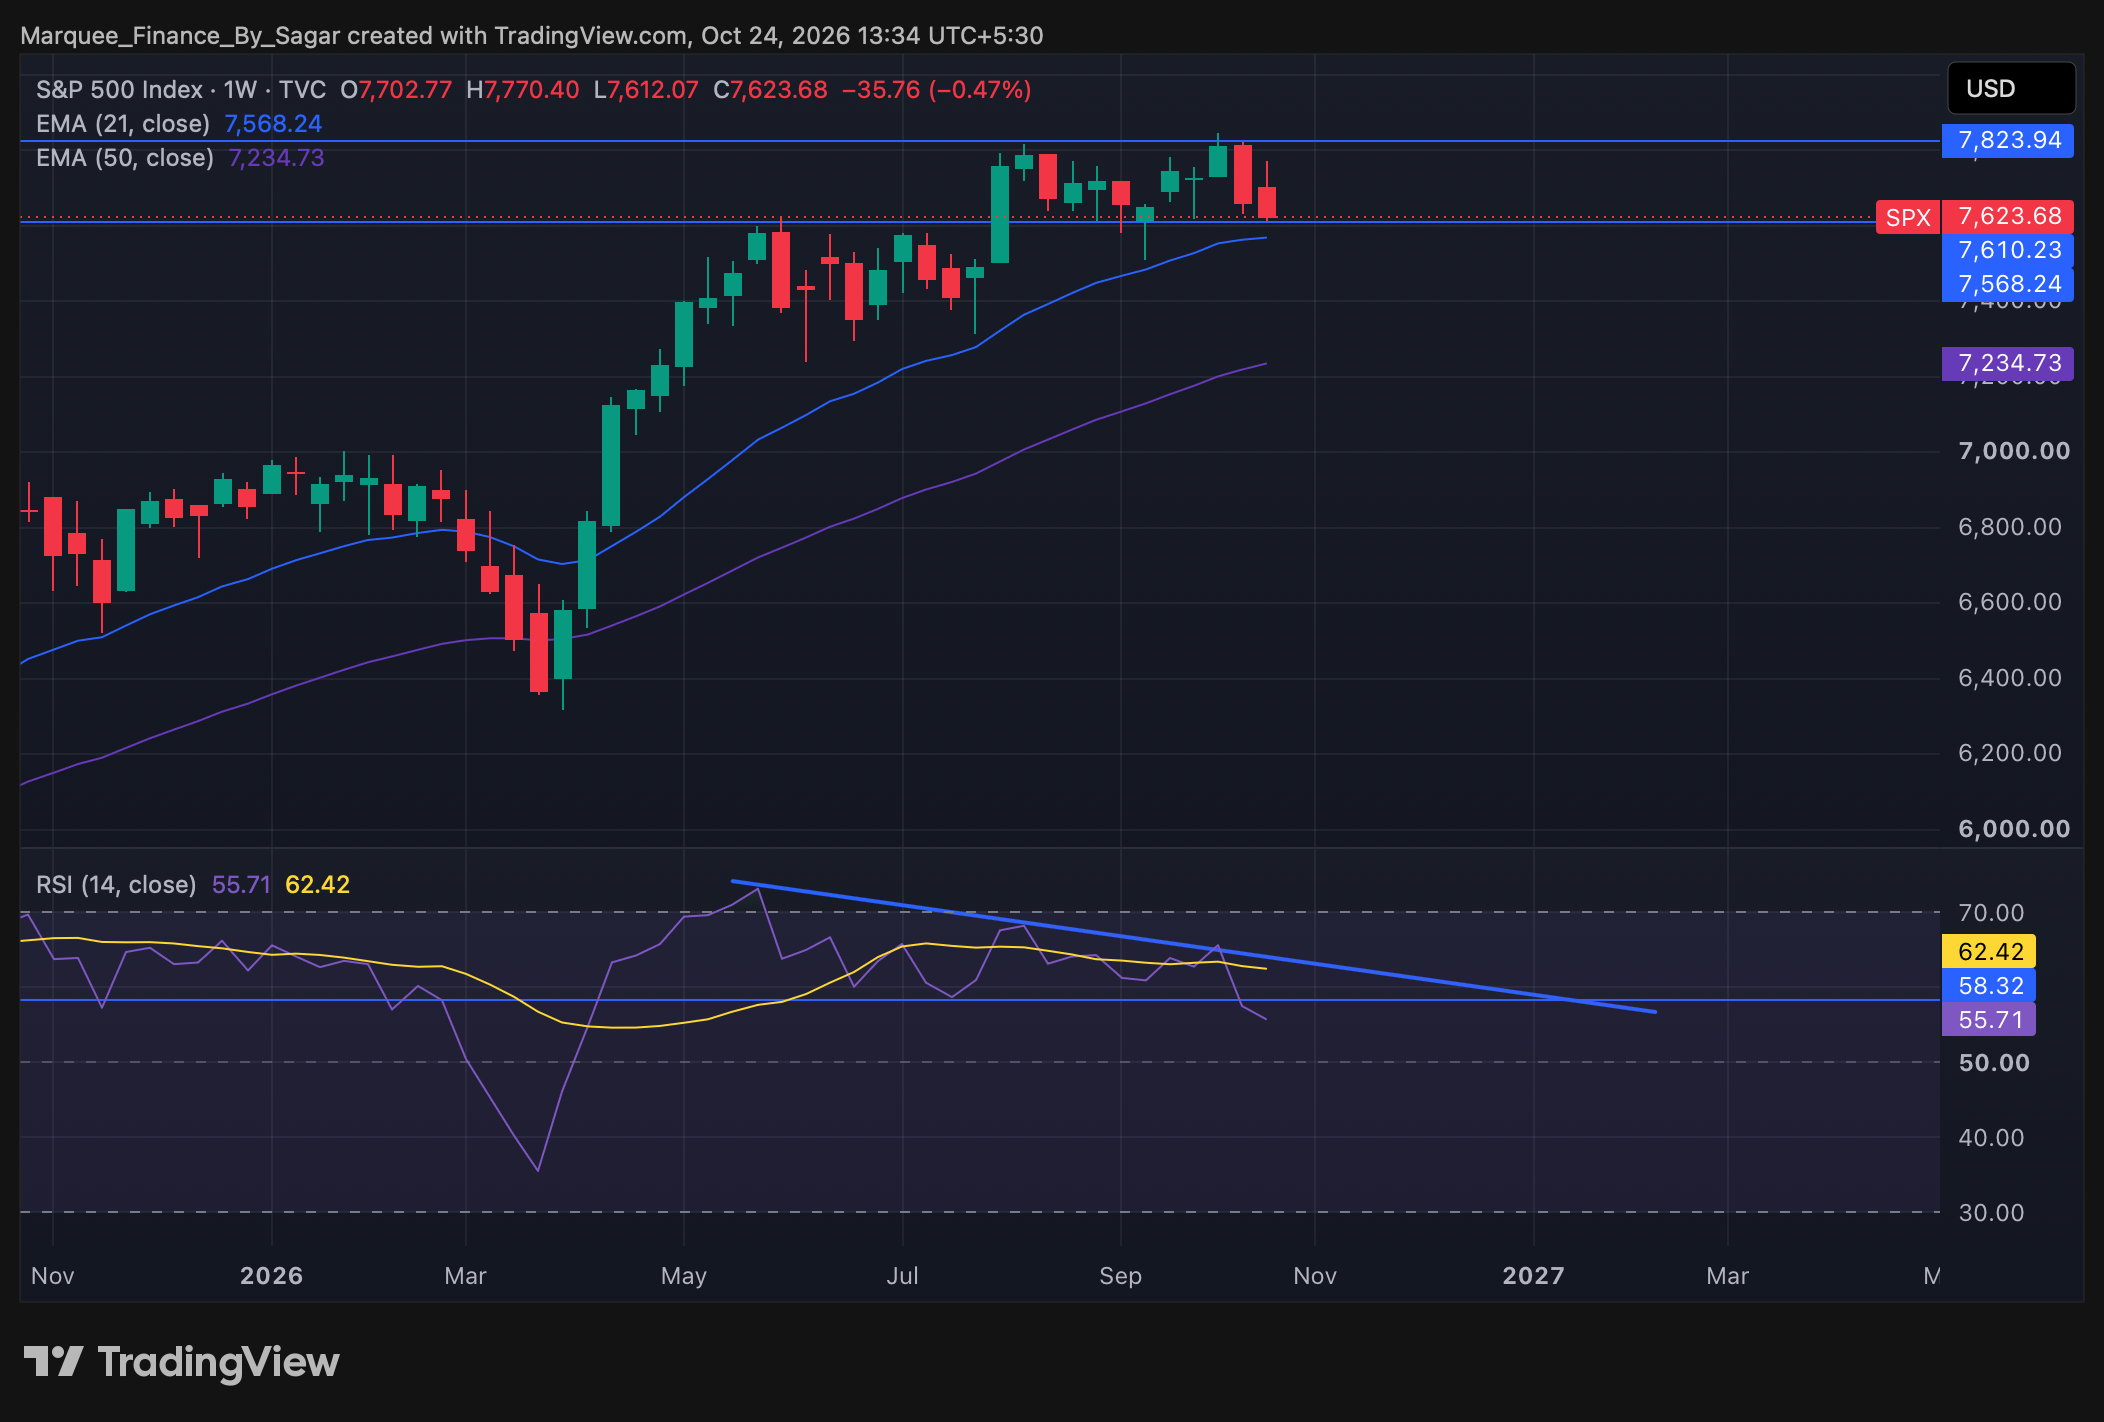
SPX has formed two ugly weekly red candles.