

Two weeks ago we wrote “Explosive Setup 5.0”, and last Saturday we wrote “Tech Winter 2.0”, as mounting concerns about the slowdown in Anthropic's revenue growth and advances in memory technology by Chinese company CXMT led to carnage in the global AI-related stocks.
We warned about AI Armageddon over the last few months and positioned our PF accordingly last month.
Multiple signs pointed to a meltdown, as credit markets had been predicting for the last few weeks.
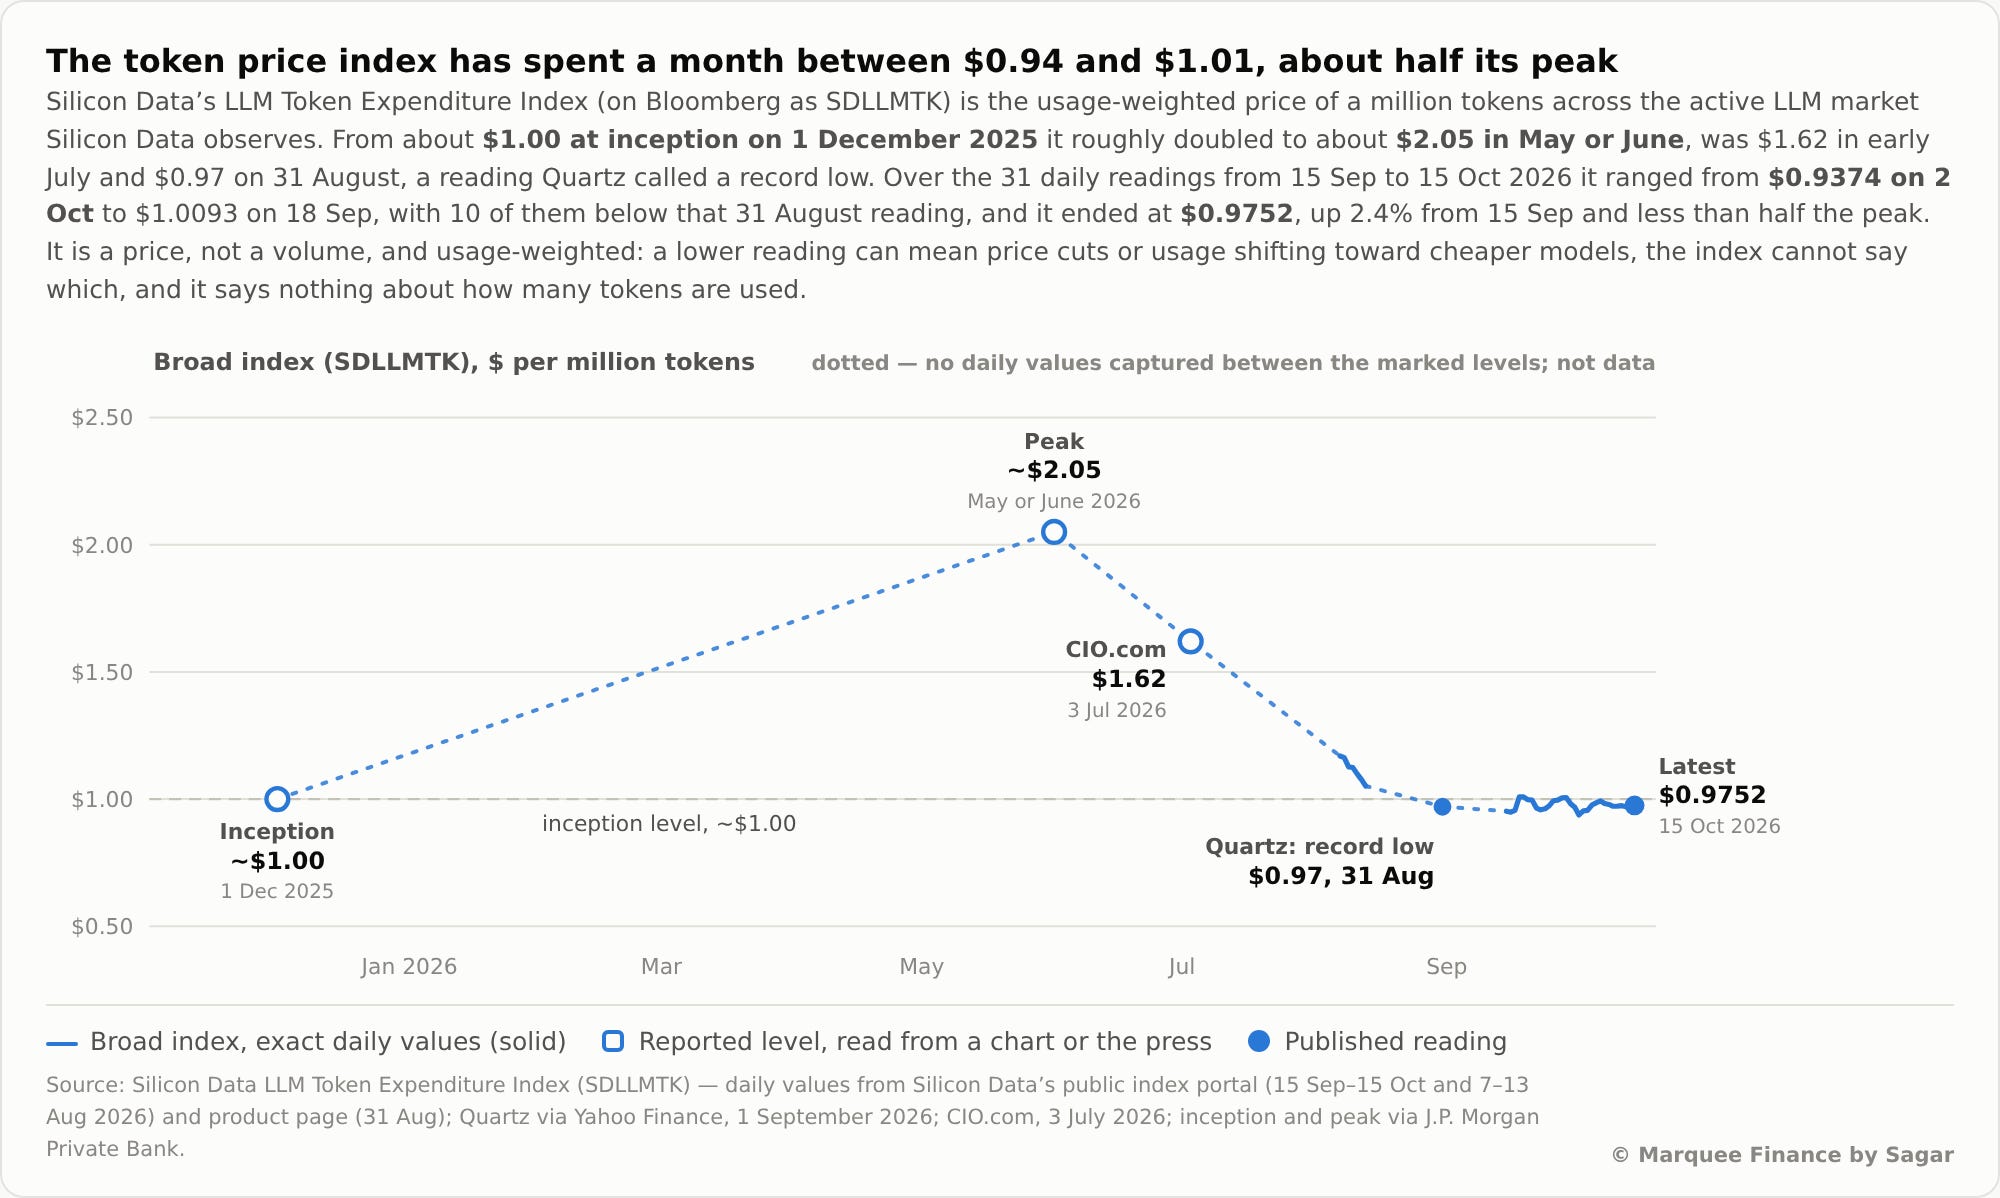
Token prices continue to plunge, and ironically, semis peaked when token prices peaked in June.
Furthermore, the hyperscalers are scaling back fundraising from the bond markets, as we believe it has become challenging to justify the ROI at elevated rates (a point we have been raising with our paid subscribers).
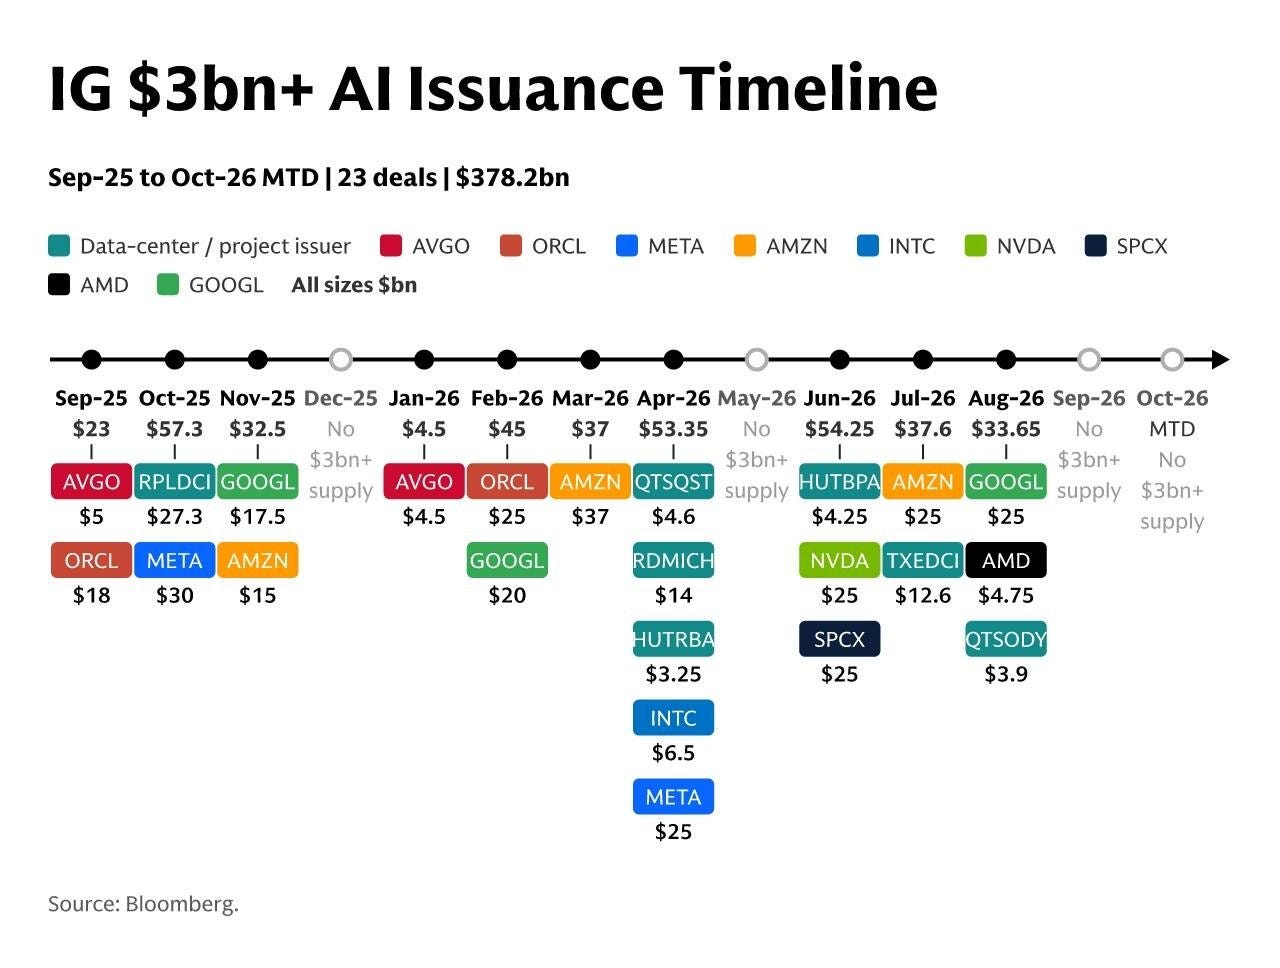
Thus, we are not only seeing slowing growth at frontier models (we also believe the major progress on intelligence is done), but the AI rollout is also facing a funding problem.
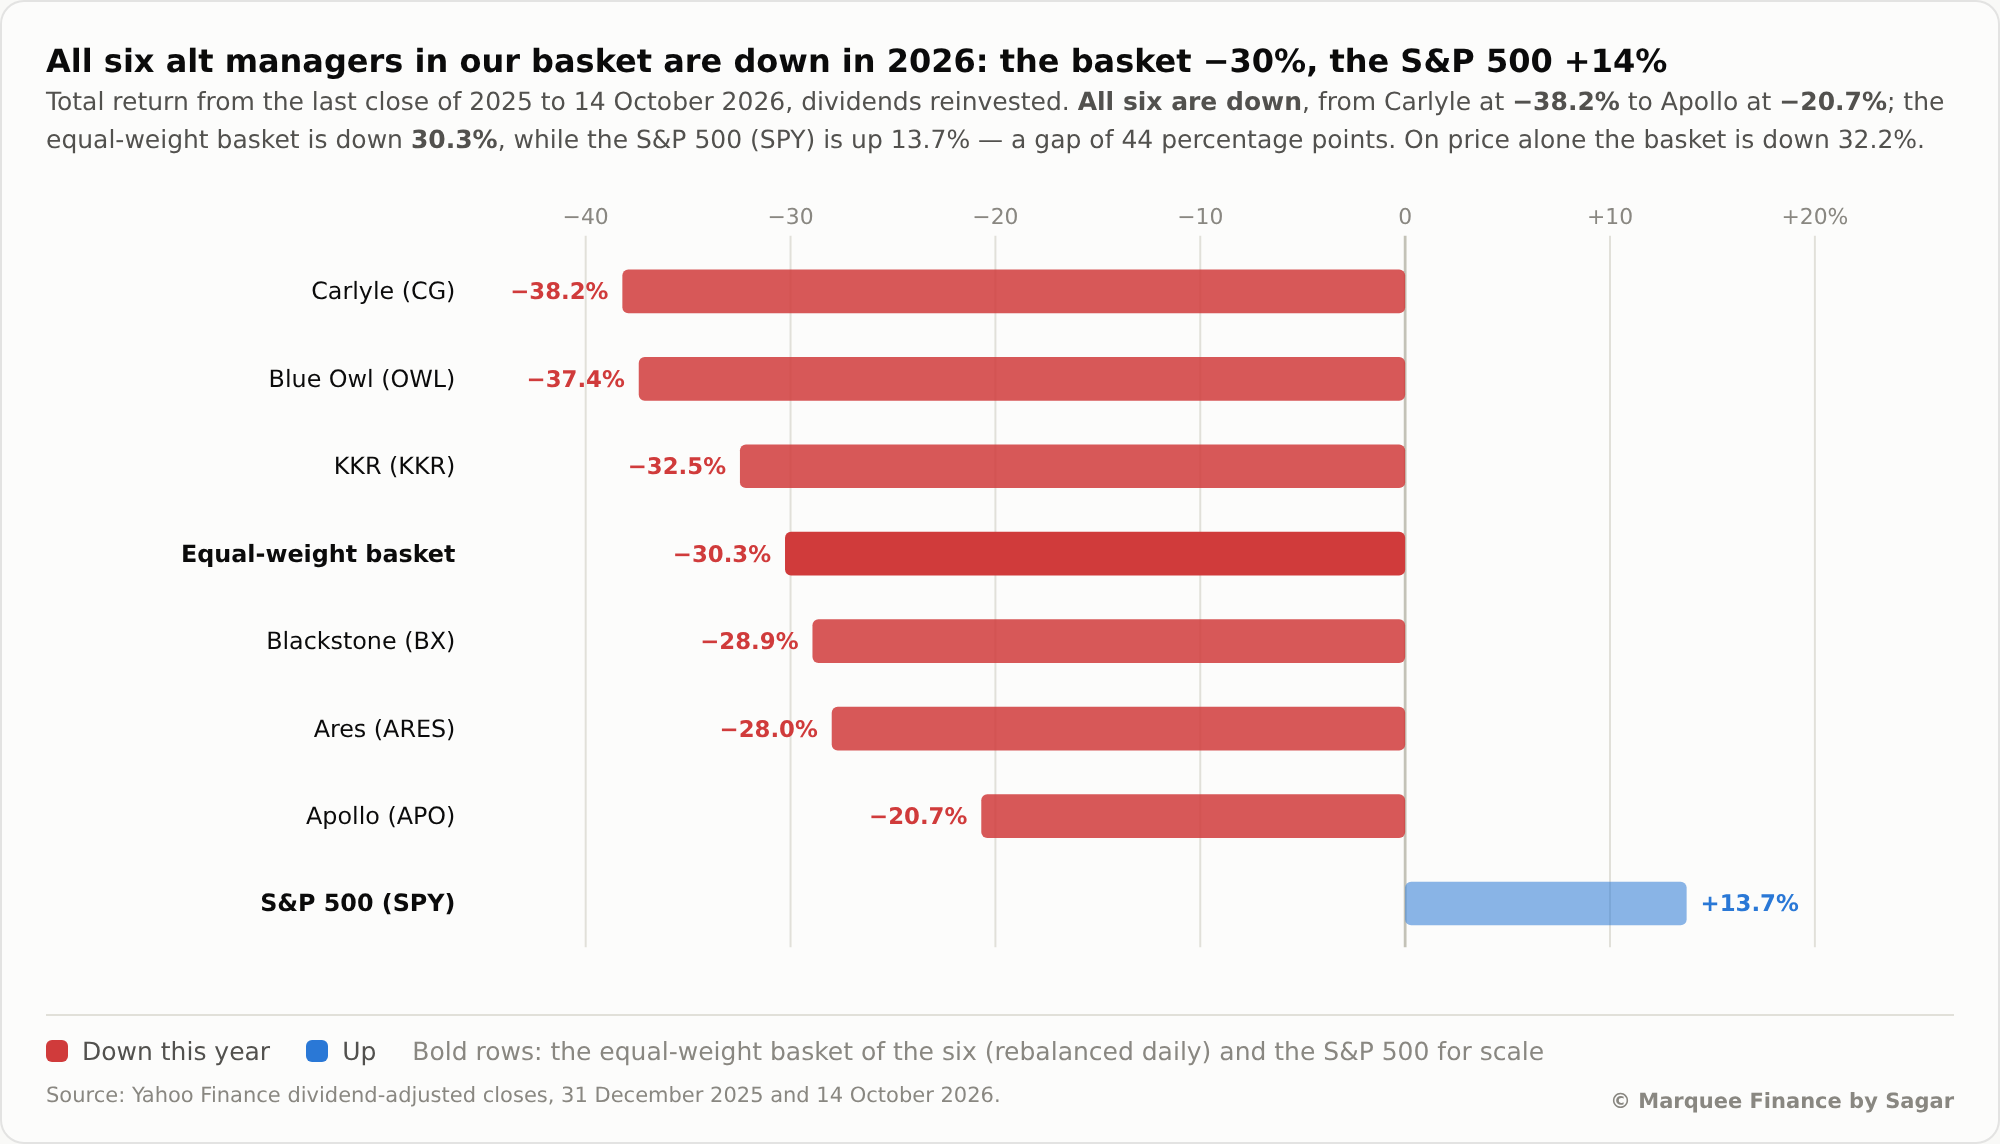
The market has already punished the private equity giants for their AI bets, believing private credit will be the biggest casualty of the capital destruction we will witness when the AI bubble pops (or has already popped).
Beyond that, the AI bubble isn't the only problem plaguing the global economy; the energy crisis is snowballing into a full-blown inflationary wave, with no end in sight for the Middle East crisis.
The Beige Book is one of the data points the Fed weighs heavily, and mentions of price hikes and pressures are at their highest since July 2025.
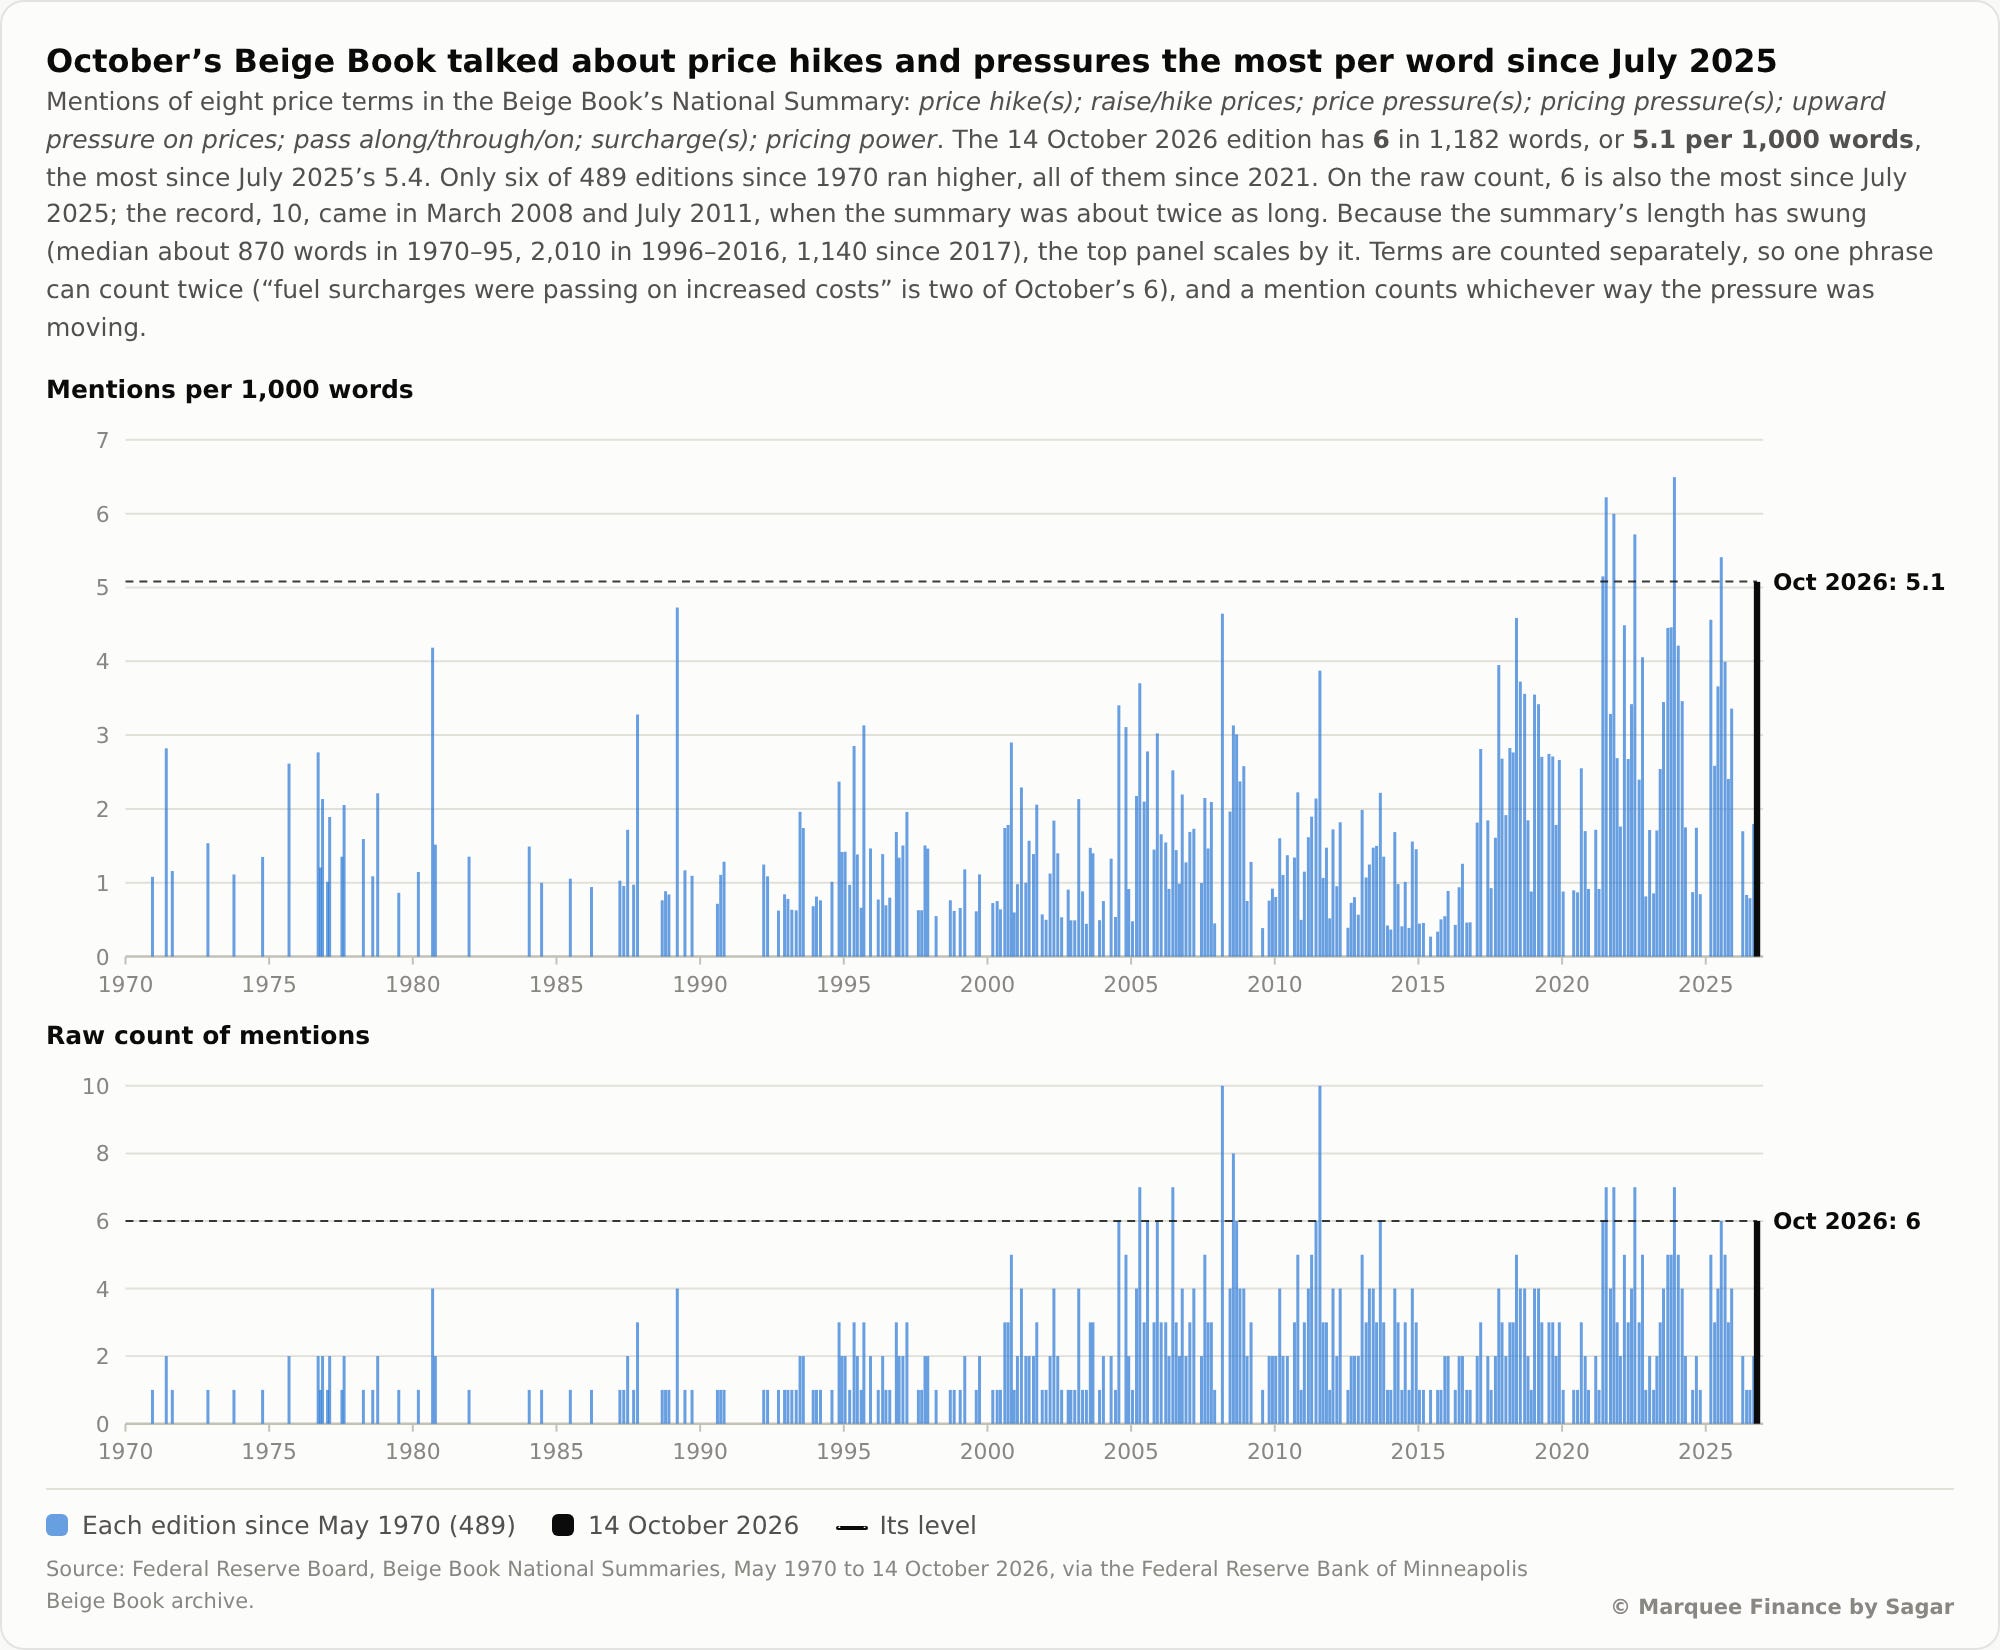
We will not be surprised if mentions of price pressures hit ATHs if oil and product prices keep surging.
BIG UPDATE: We are done building “Global Macro Musings” (more features will be added later on). The testing phase has begun, and the paid subscribers will get access (beta version) in the next 7-10 days.
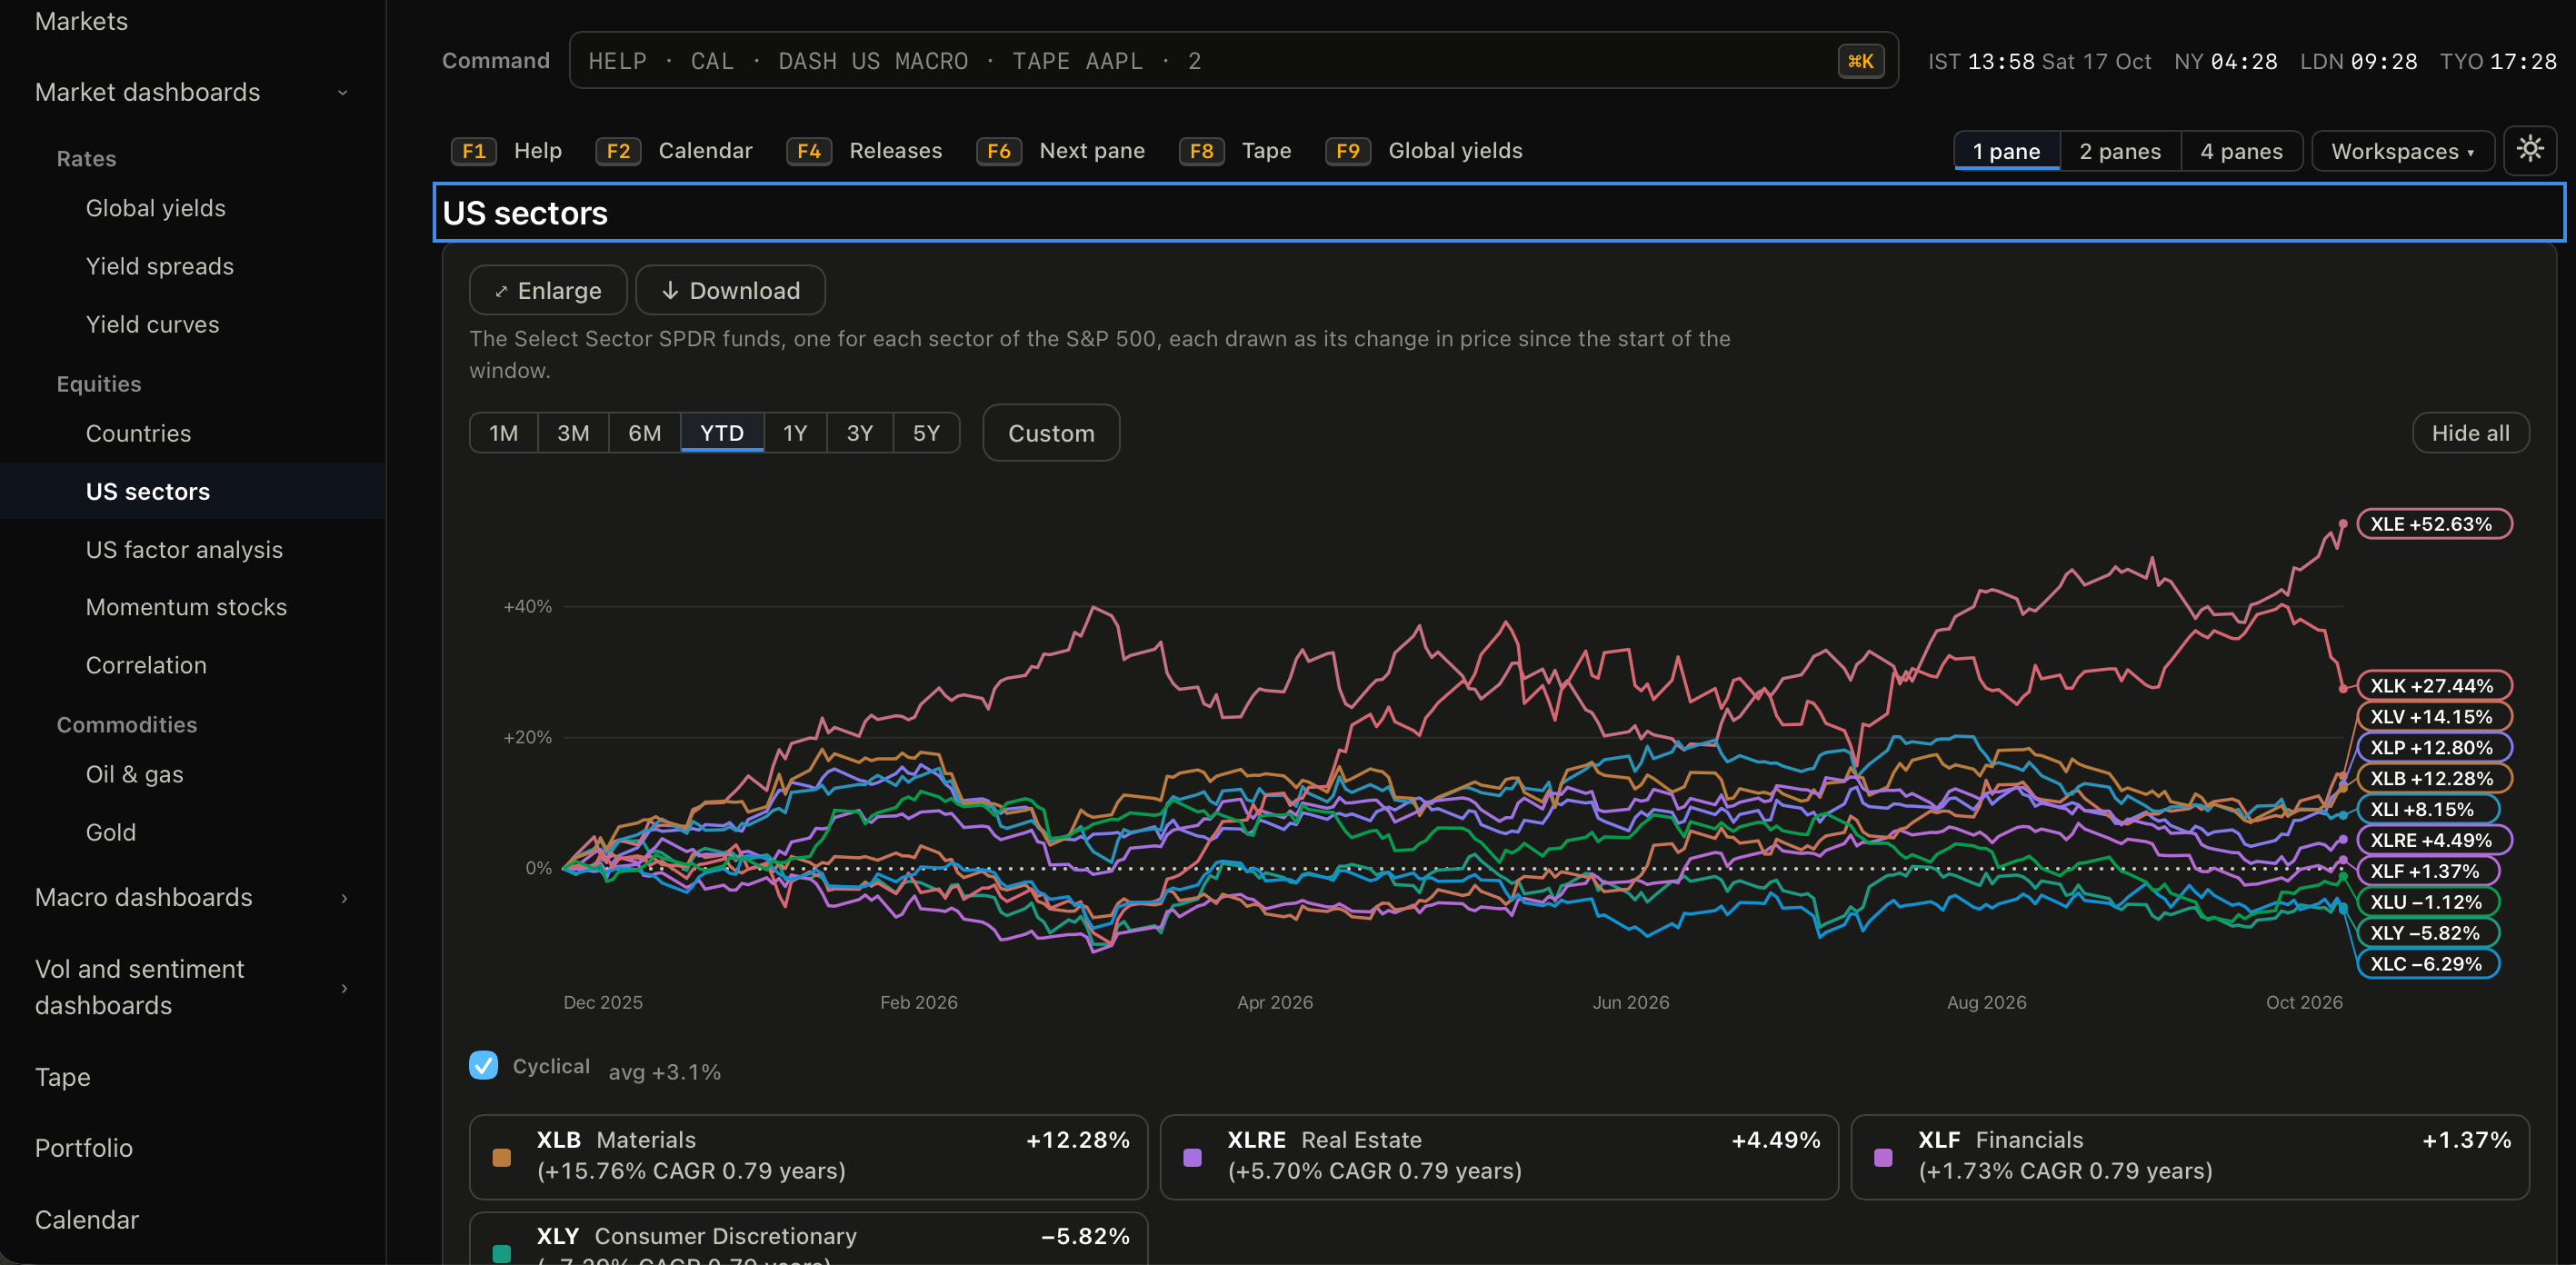
We have recouped some of the losses that we faced in September.
We are now up 5.22% YTD, and with our PF positioned as an anti-AI trade, we expect to gain further ground in the coming weeks.

US/Equities/Bonds/Dollar/Gold/Oil!
This was a data-heavy week, and the numbers point to a red-hot inflationary environment.
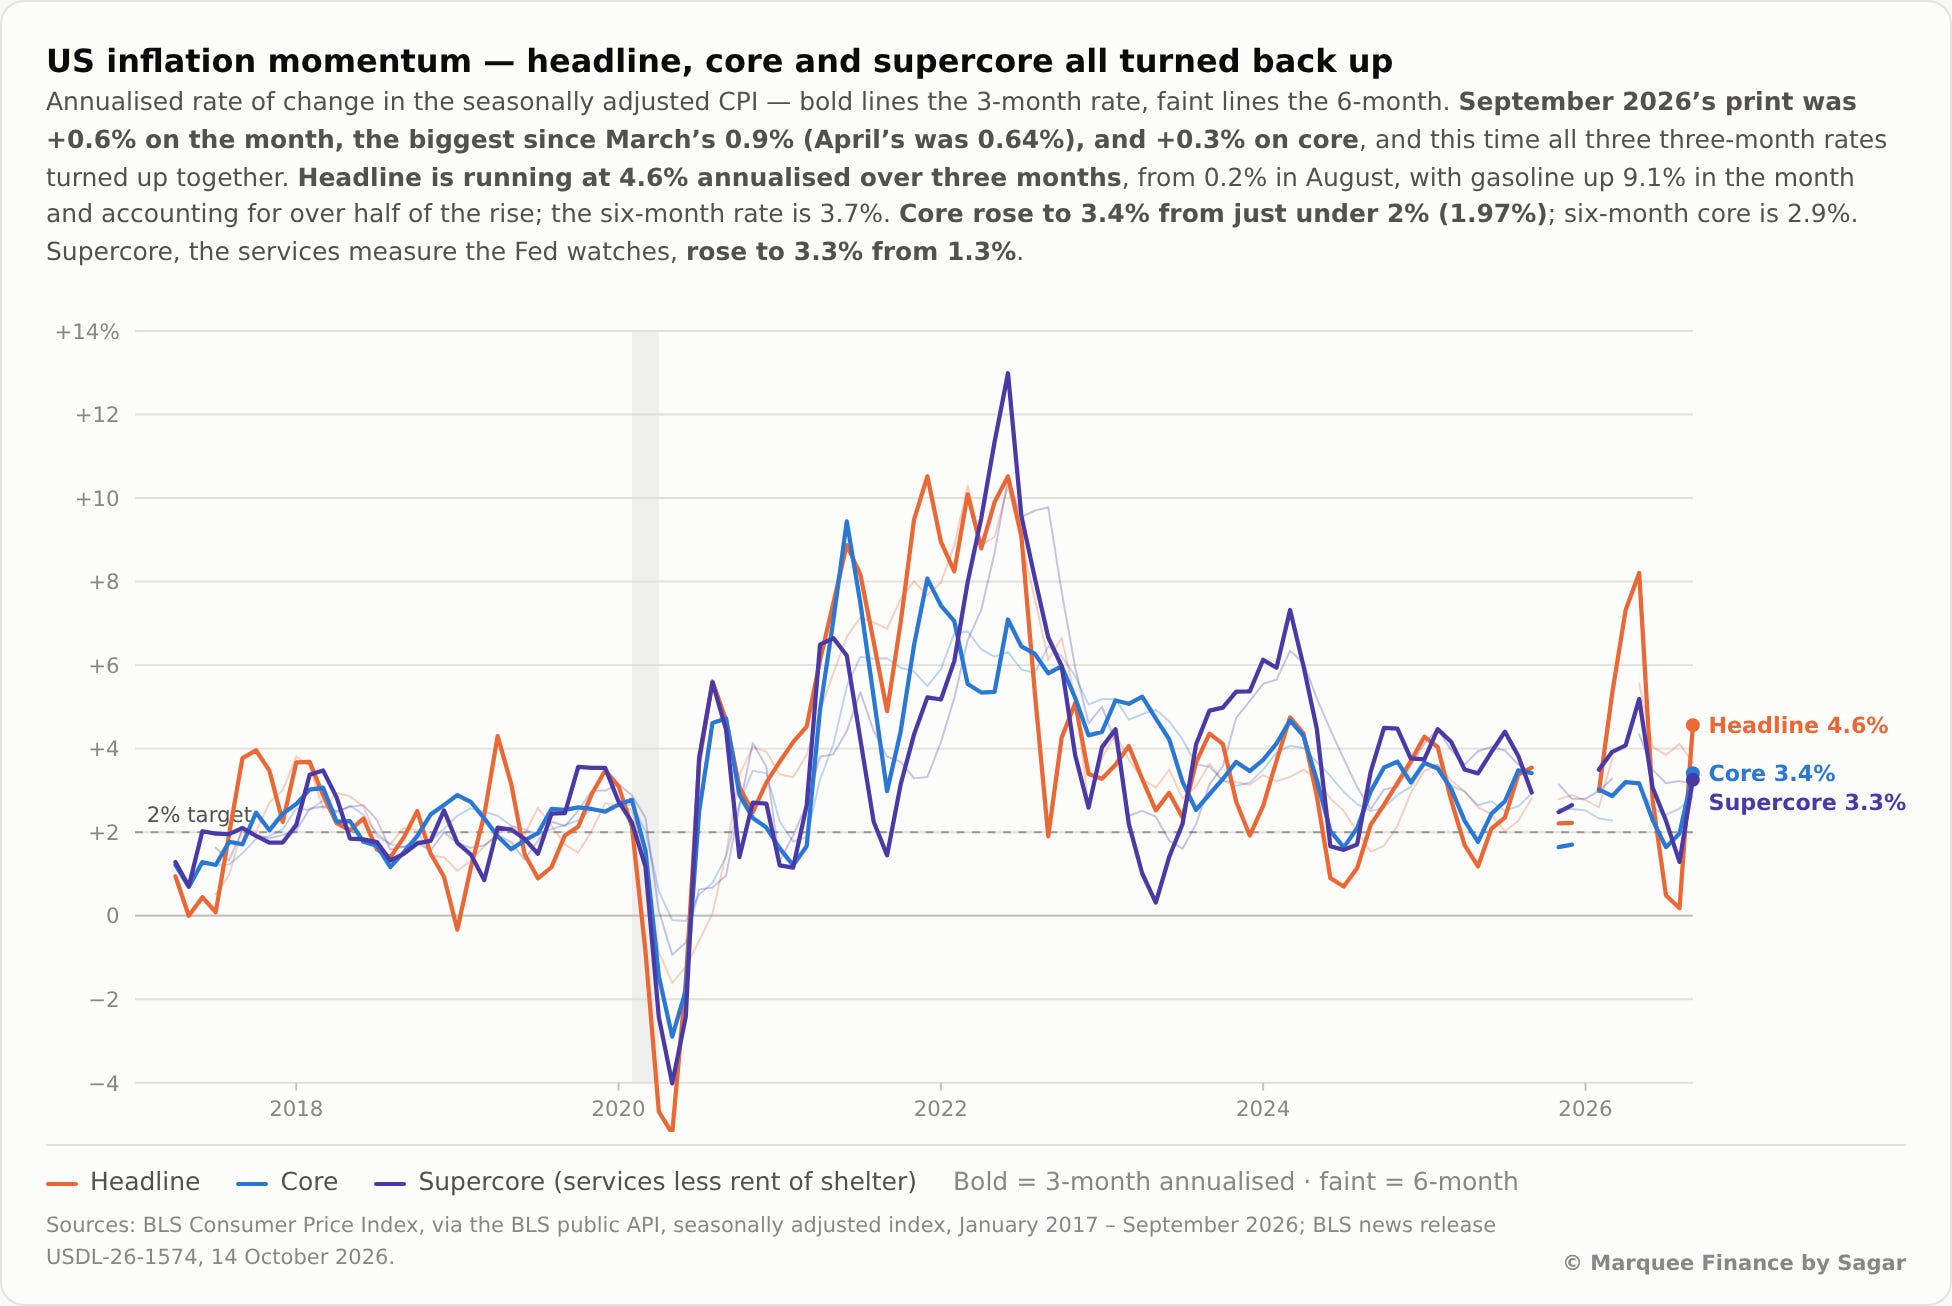
Inflation momentum accelerated as the annualised 3-month headline CPI surged to 4.6%, Core CPI rose to 3.4% (beating consensus), and Supercore moved higher to 3.3%.
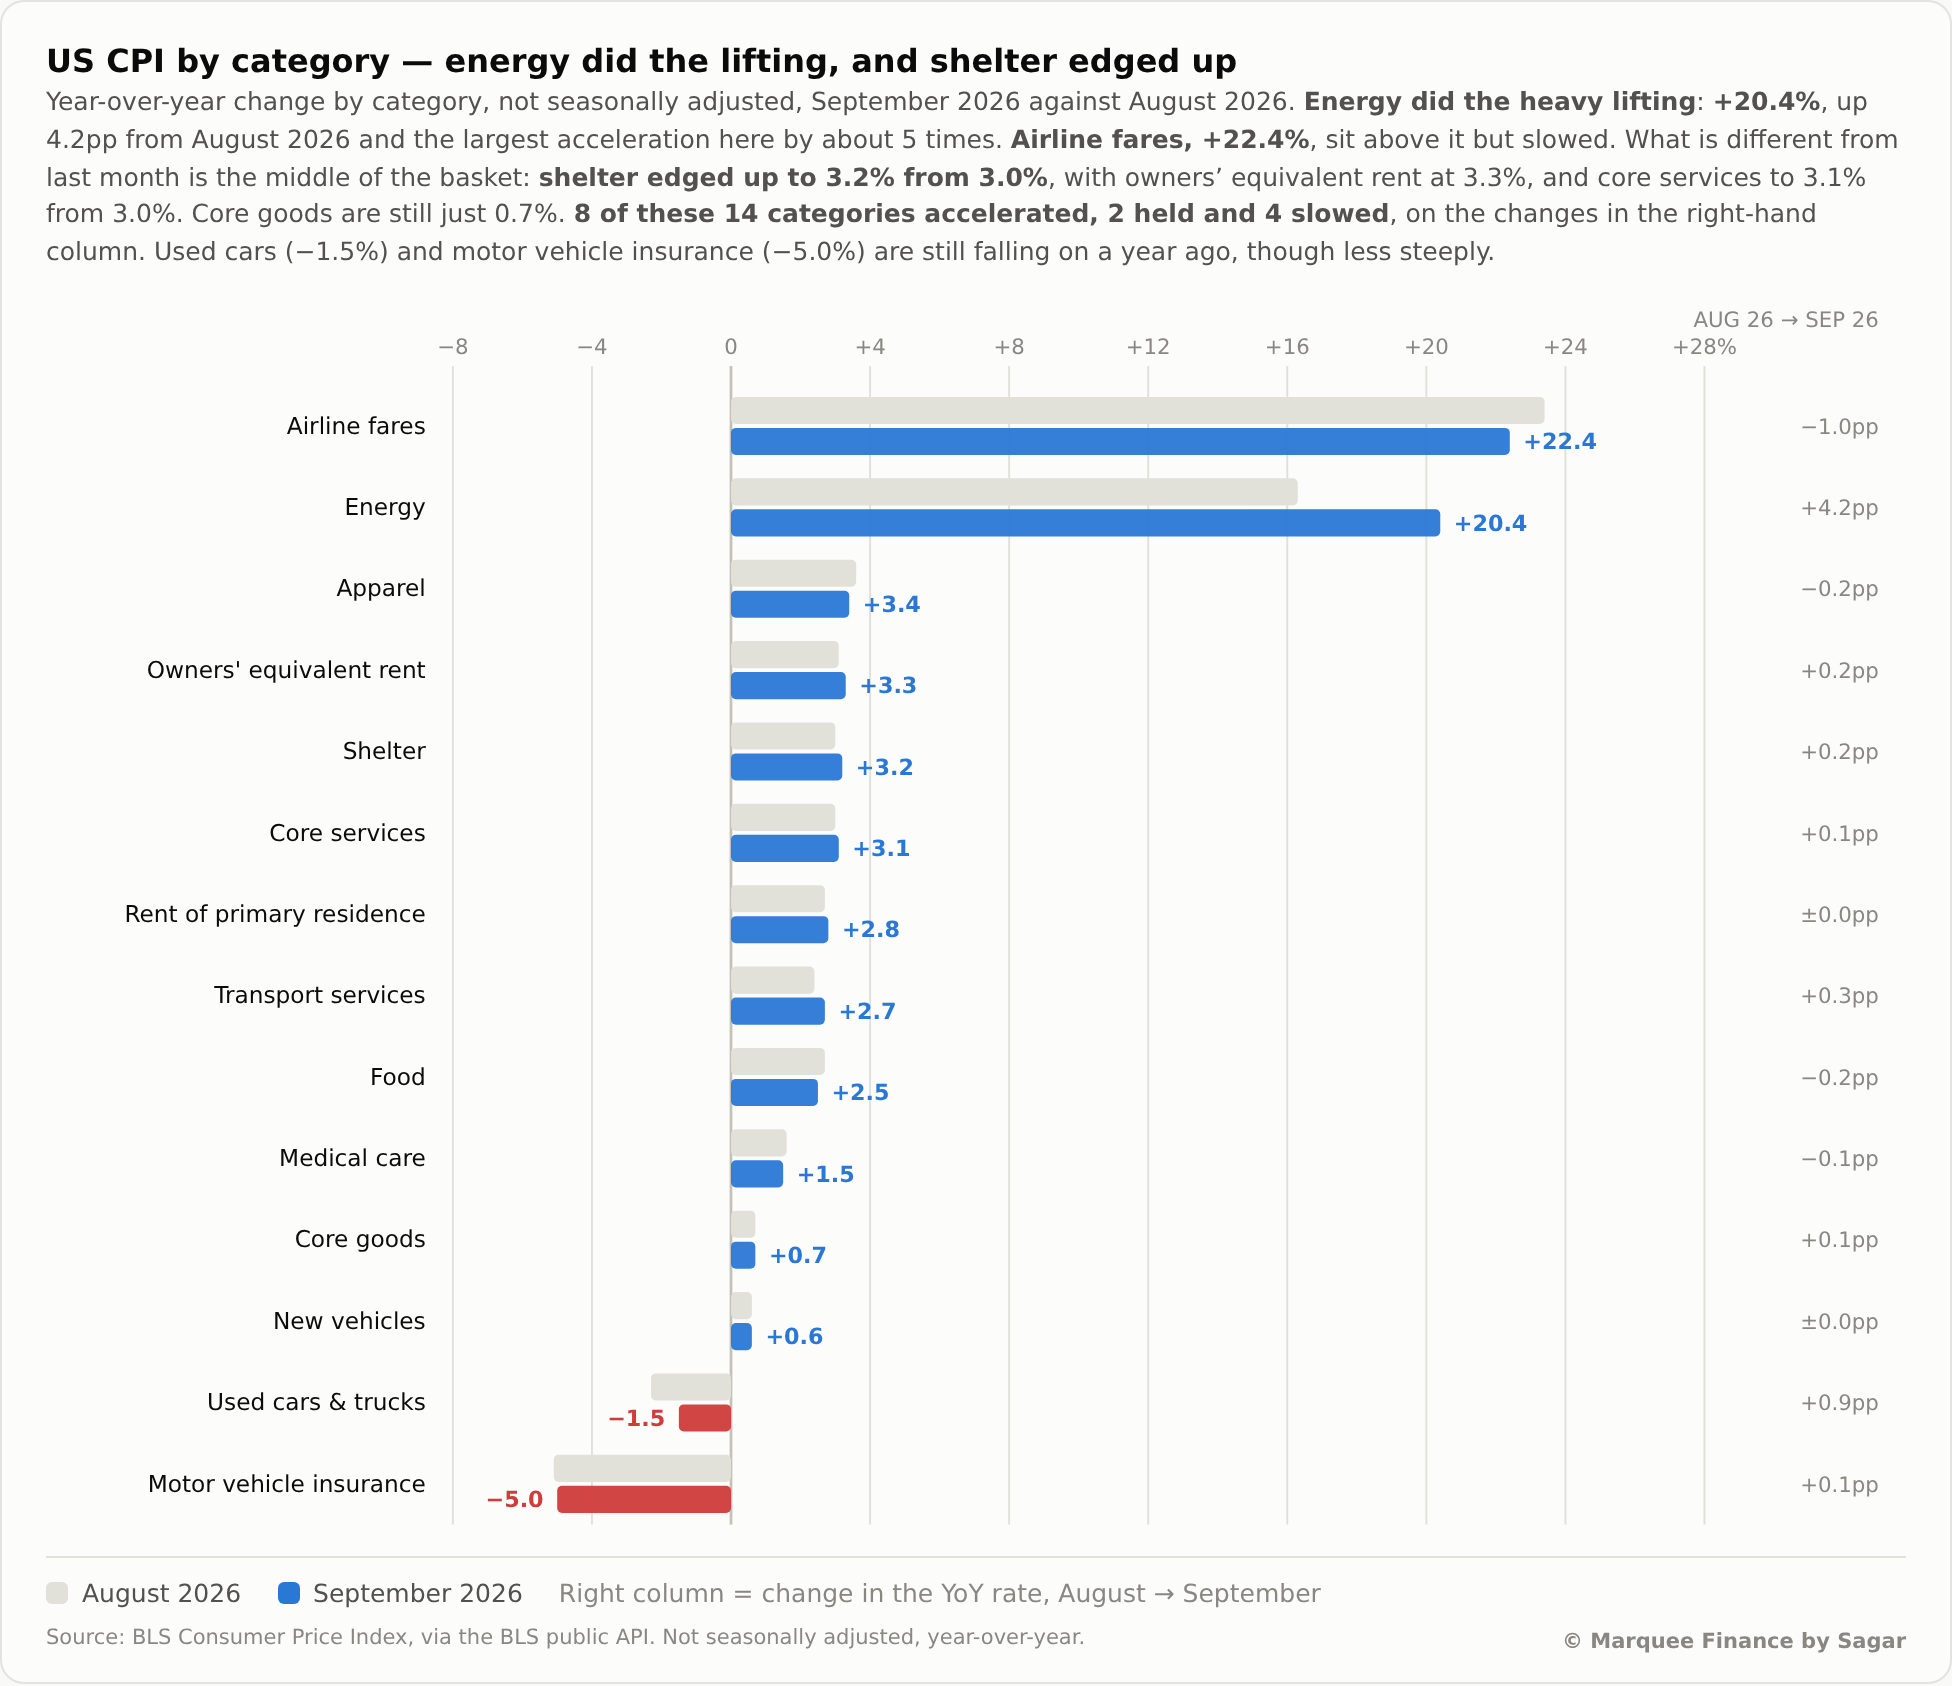
By category, energy added the most, as a surge in diesel and gasoline prices drove a 4.4% MoM jump in Energy inflation.
All other categories, except used cars and trucks and motor vehicle insurance, came in higher YoY.
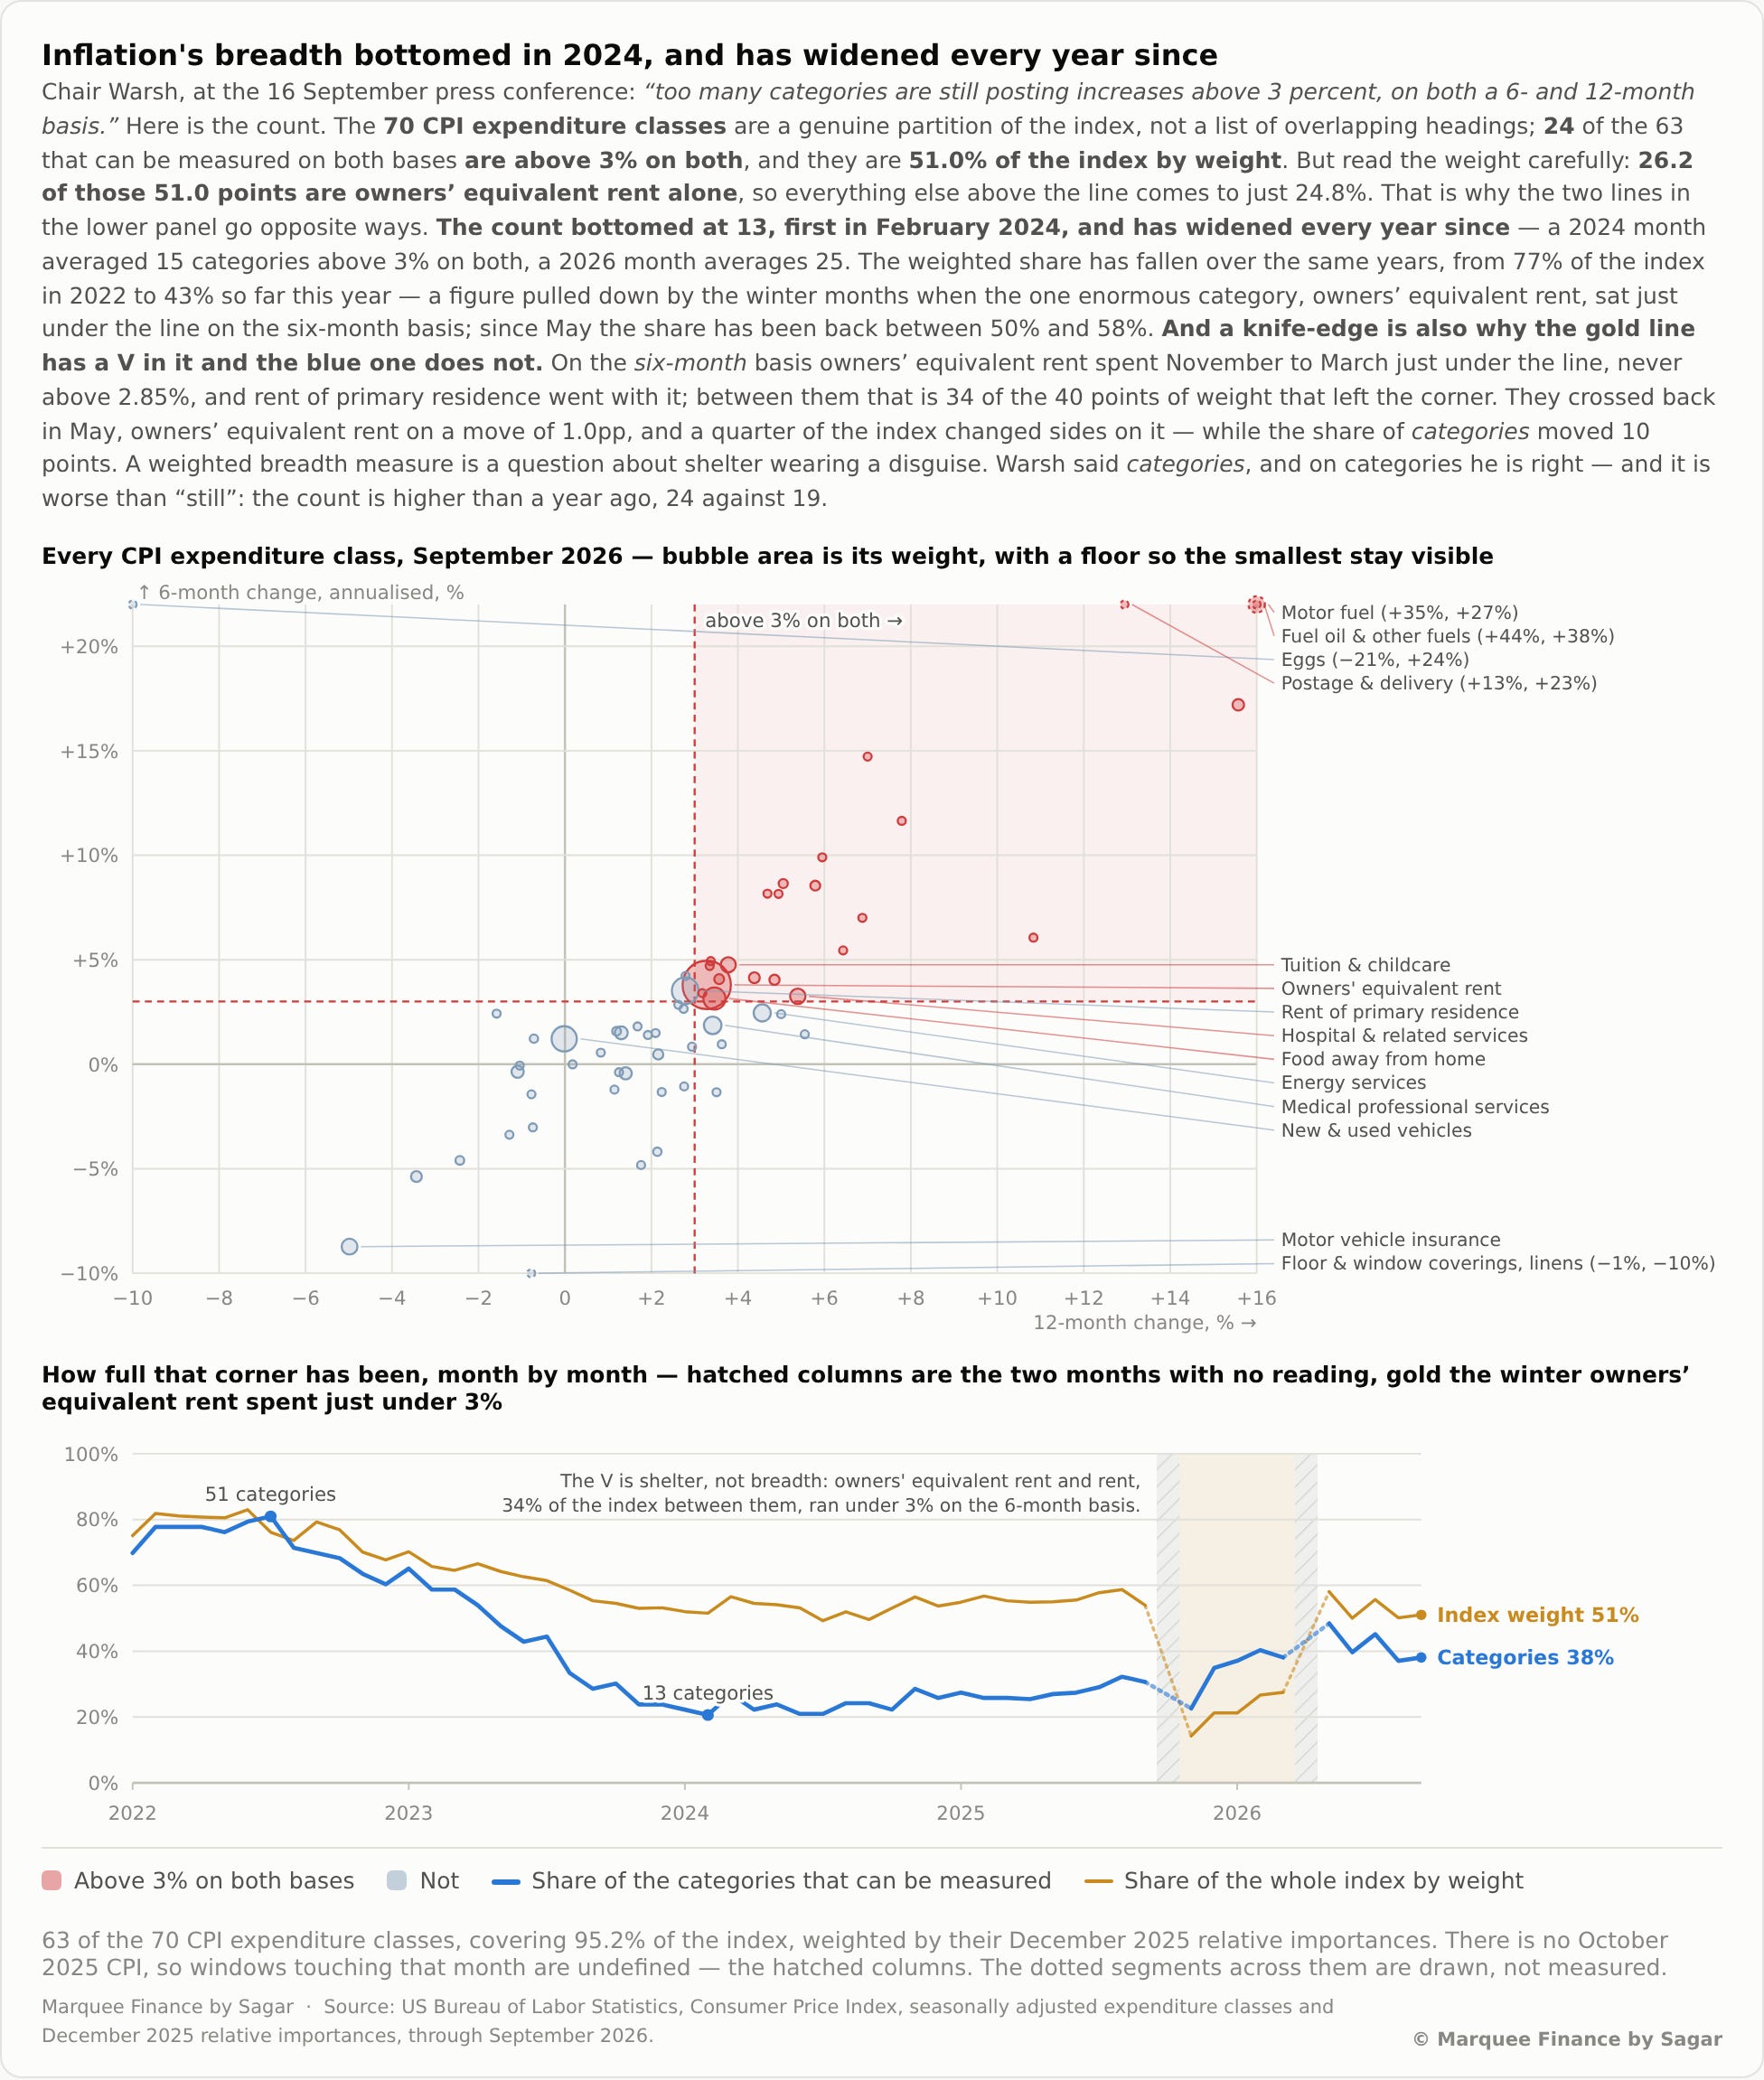
One measure Warsh discussed at last month’s FOMC was the number of categories reporting 3% YoY growth (inflation breadth).
Interestingly, we are slightly off the peak here: only 24 of the 63 categories came in above 3% YoY; however, these categories make up over 50% of the CPI weight.
We got the hottest PPI since 2022, with a massive beat on consensus.
PPI came in at 6.3% YoY vs expected 5.4%, and core PPI came in at 5% YoY vs expected 4.4%.
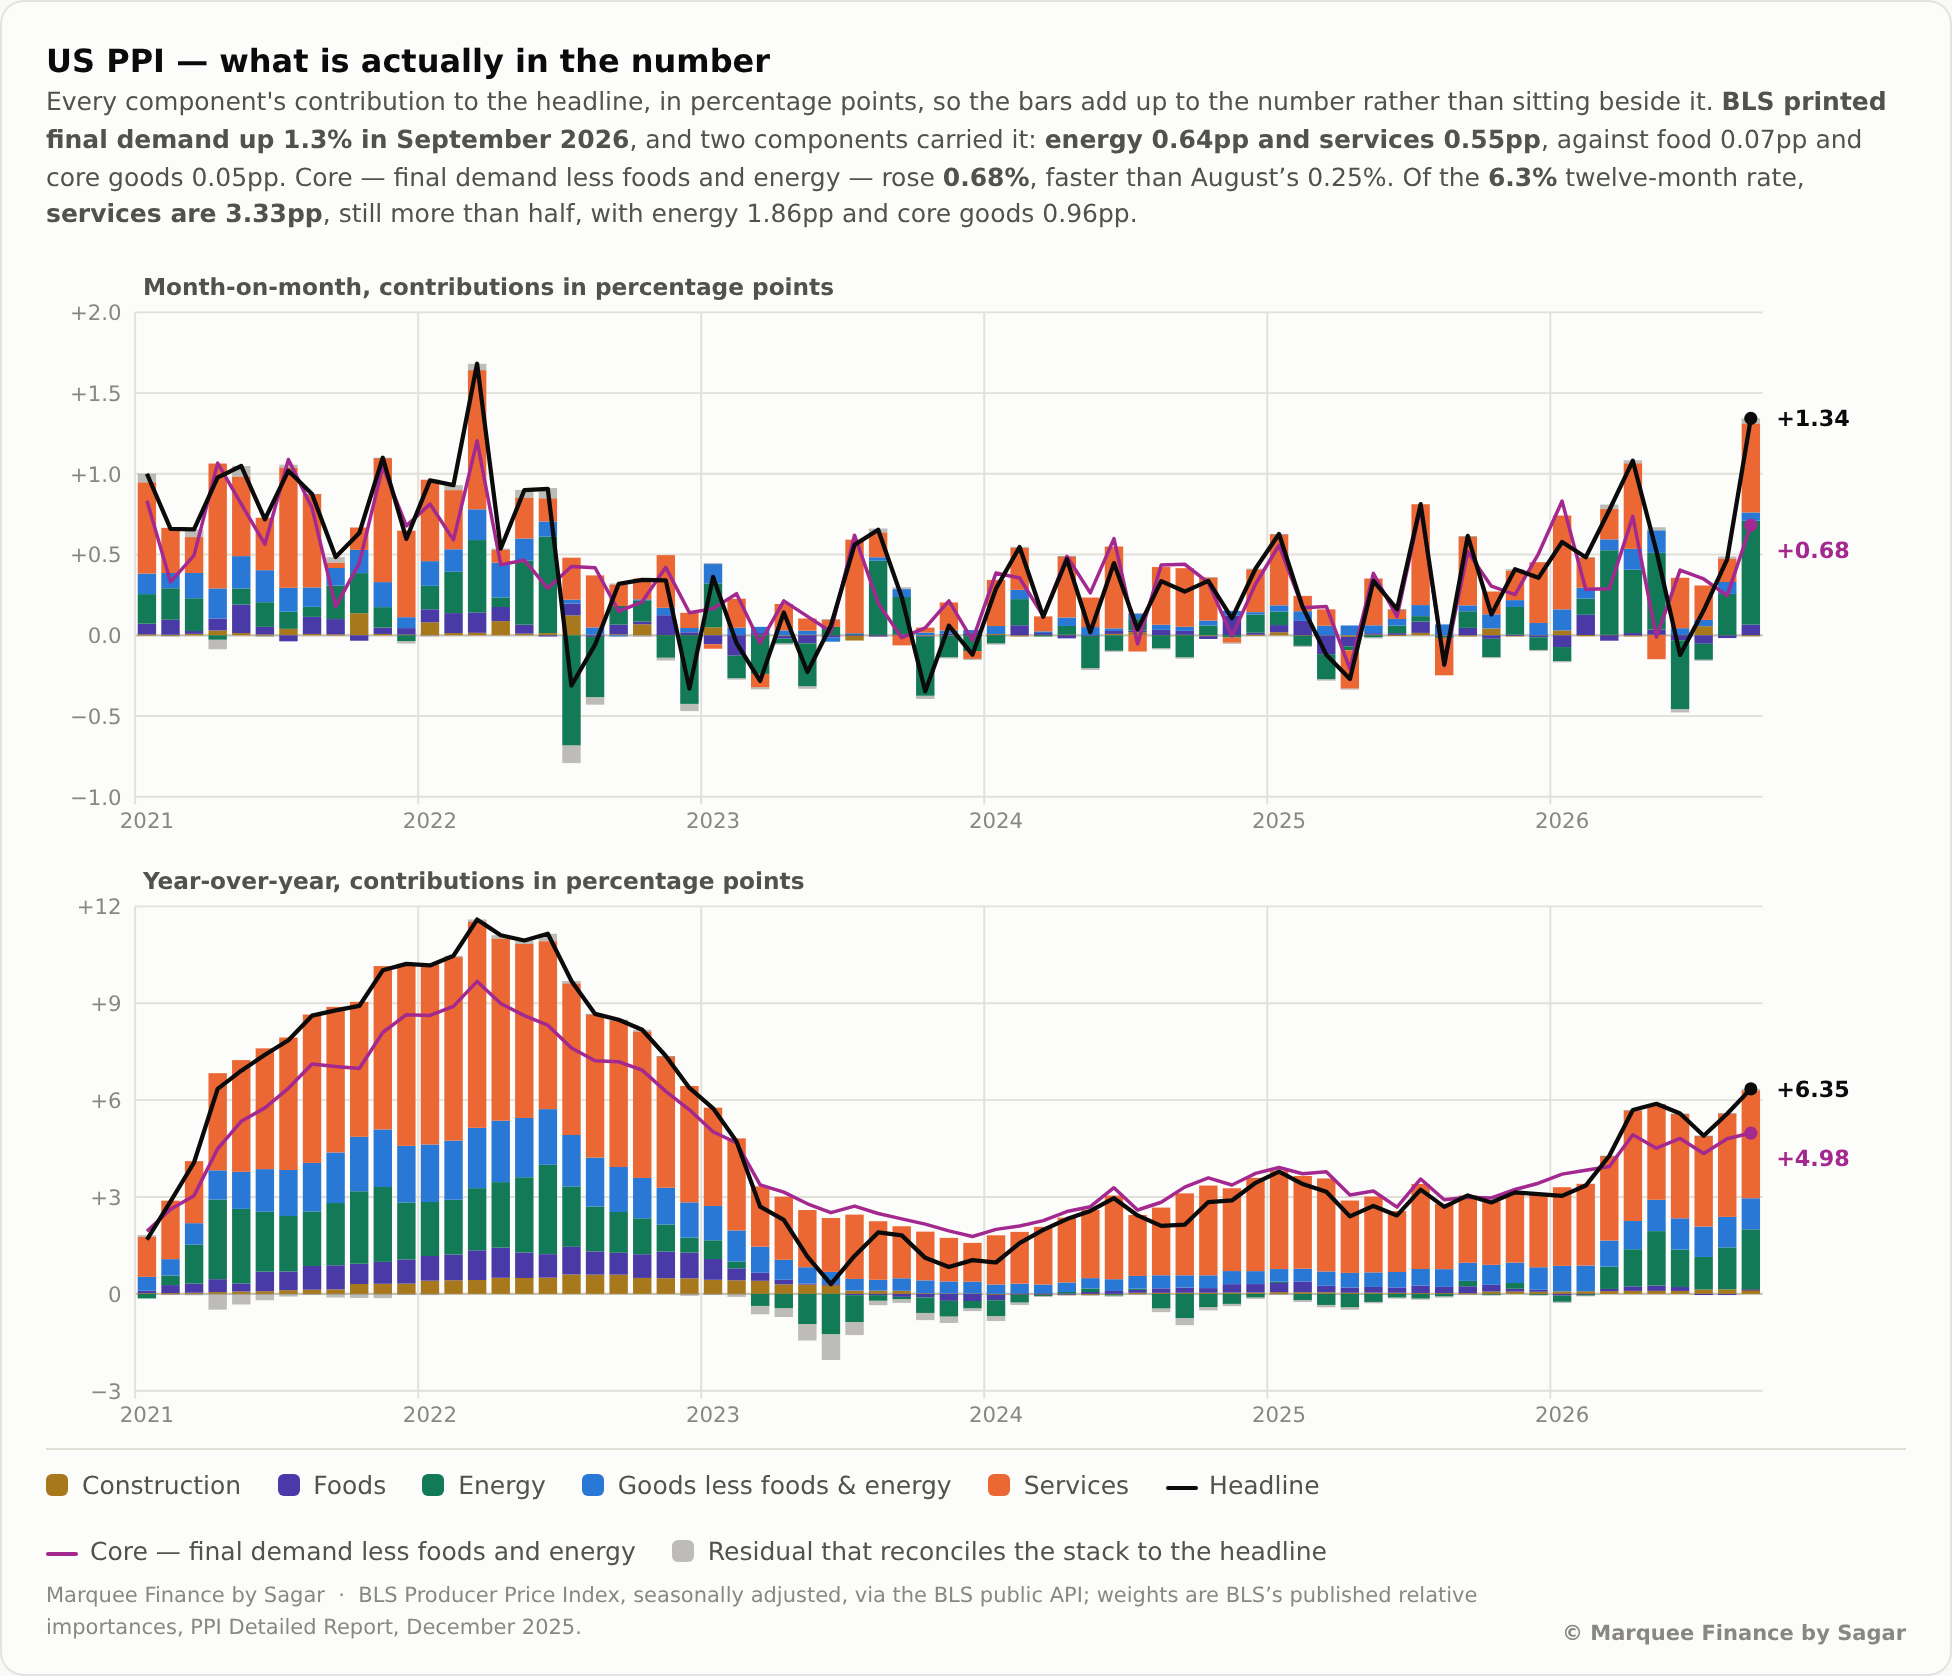
Although energy was the biggest contributor, one can’t deny the fact that services PPI is also stubbornly high.
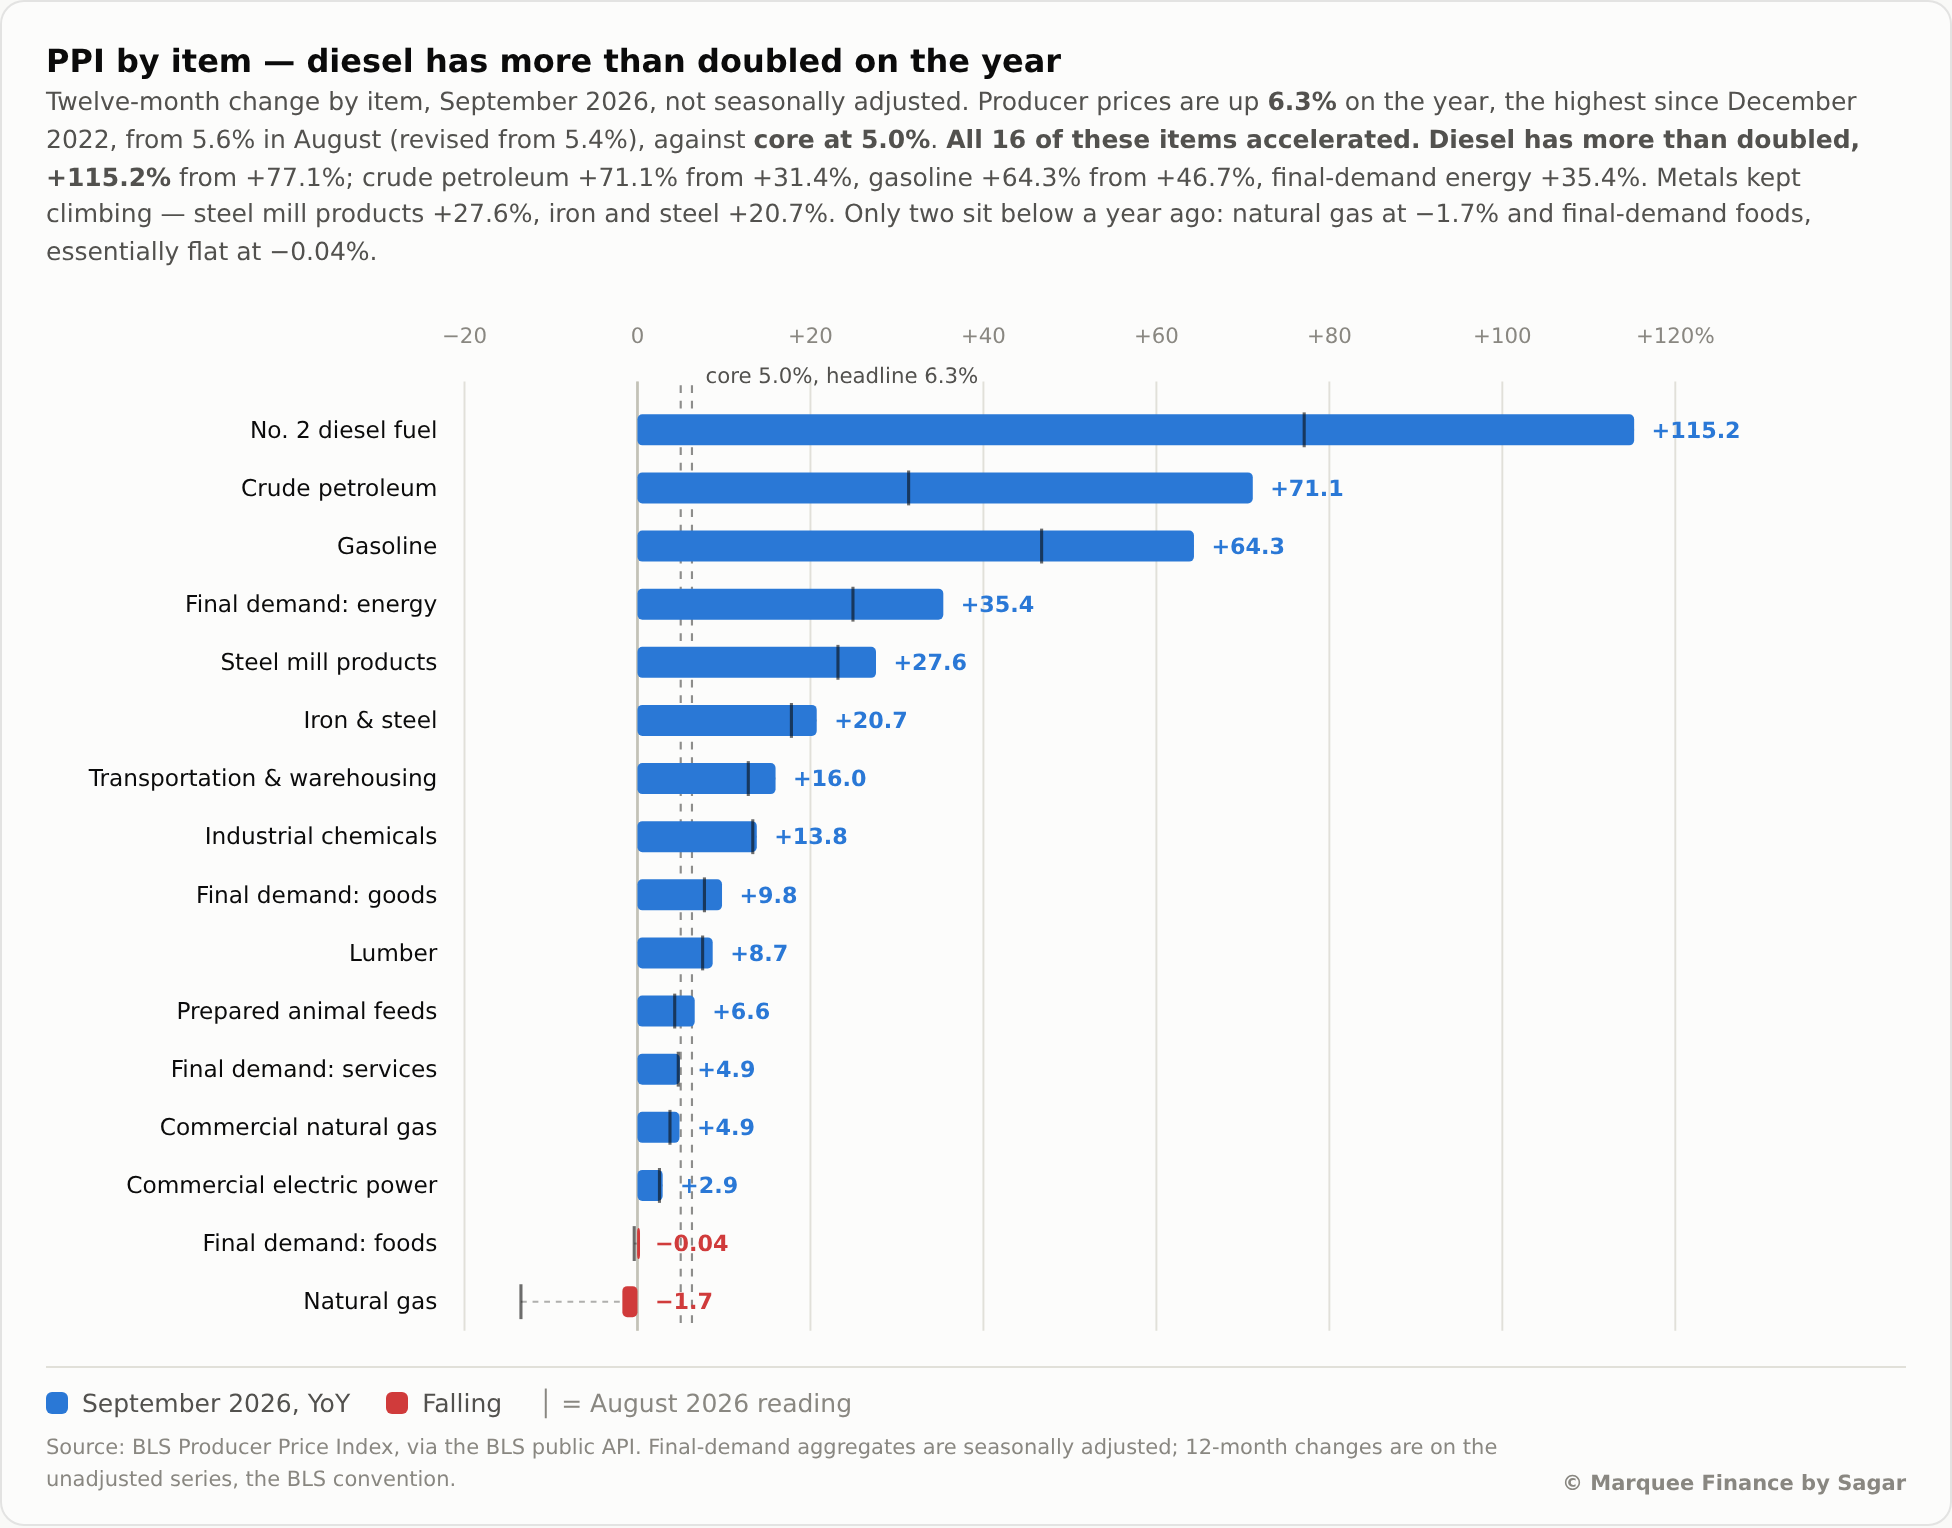
As usual, the devil lies in the details.
Diesel was up a whopping 115% YoY, while Gasoline was up 64% YoY.
The shocker of the month was the US PPI final demand goods, which saw the biggest monthly rise in the last 16 years.
The PPI final demand goods rose by 2.6% MoM.
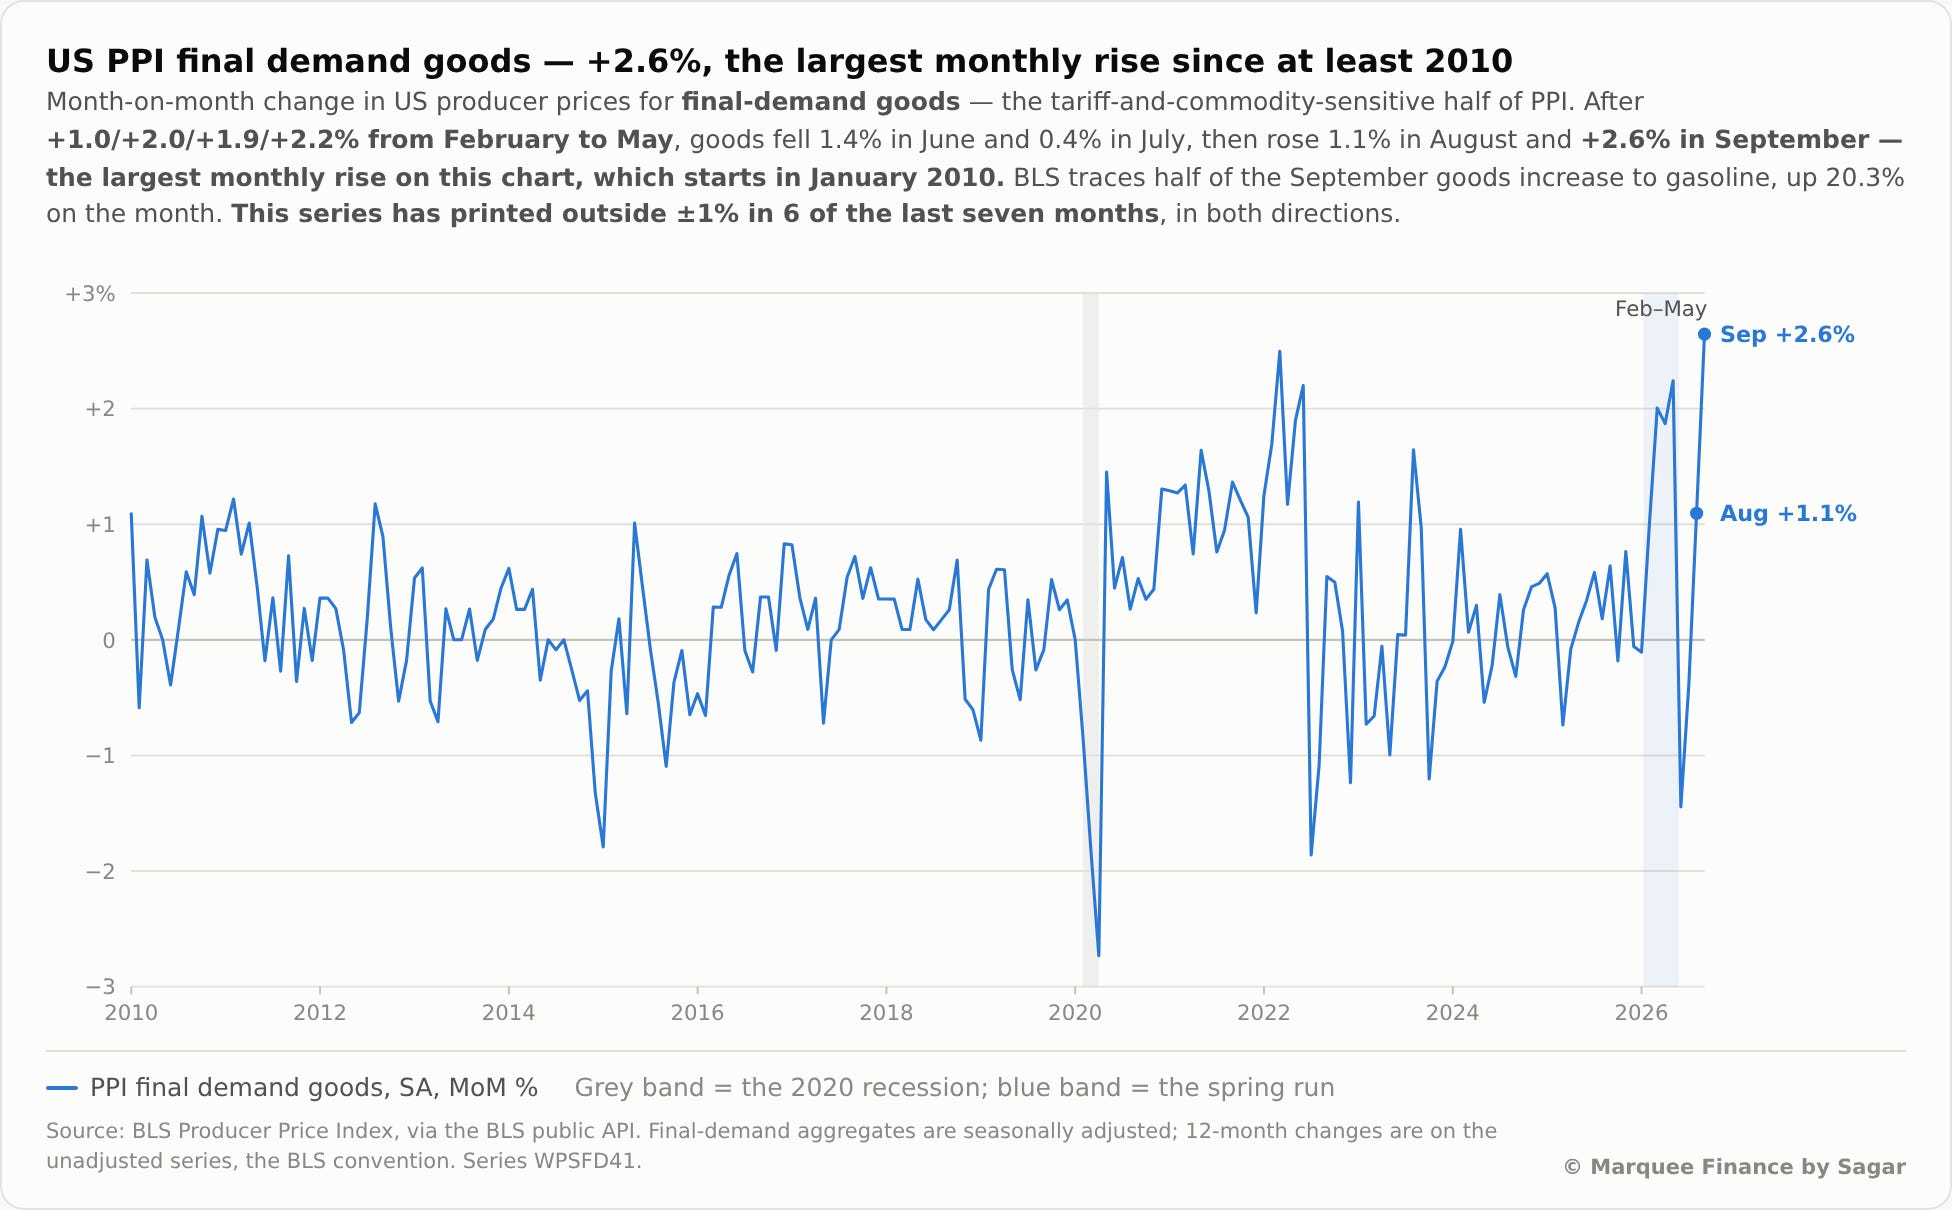
Overall, it was a red-hot PPI, and we will not be surprised to see a similar trend in the CPI.
We also got the NFIB Small Business Survey, which we track closely, considering small businesses remain the biggest employers in the US.
It was an overall shocker: quality of labour and inflation as the single most important problem jumped significantly.
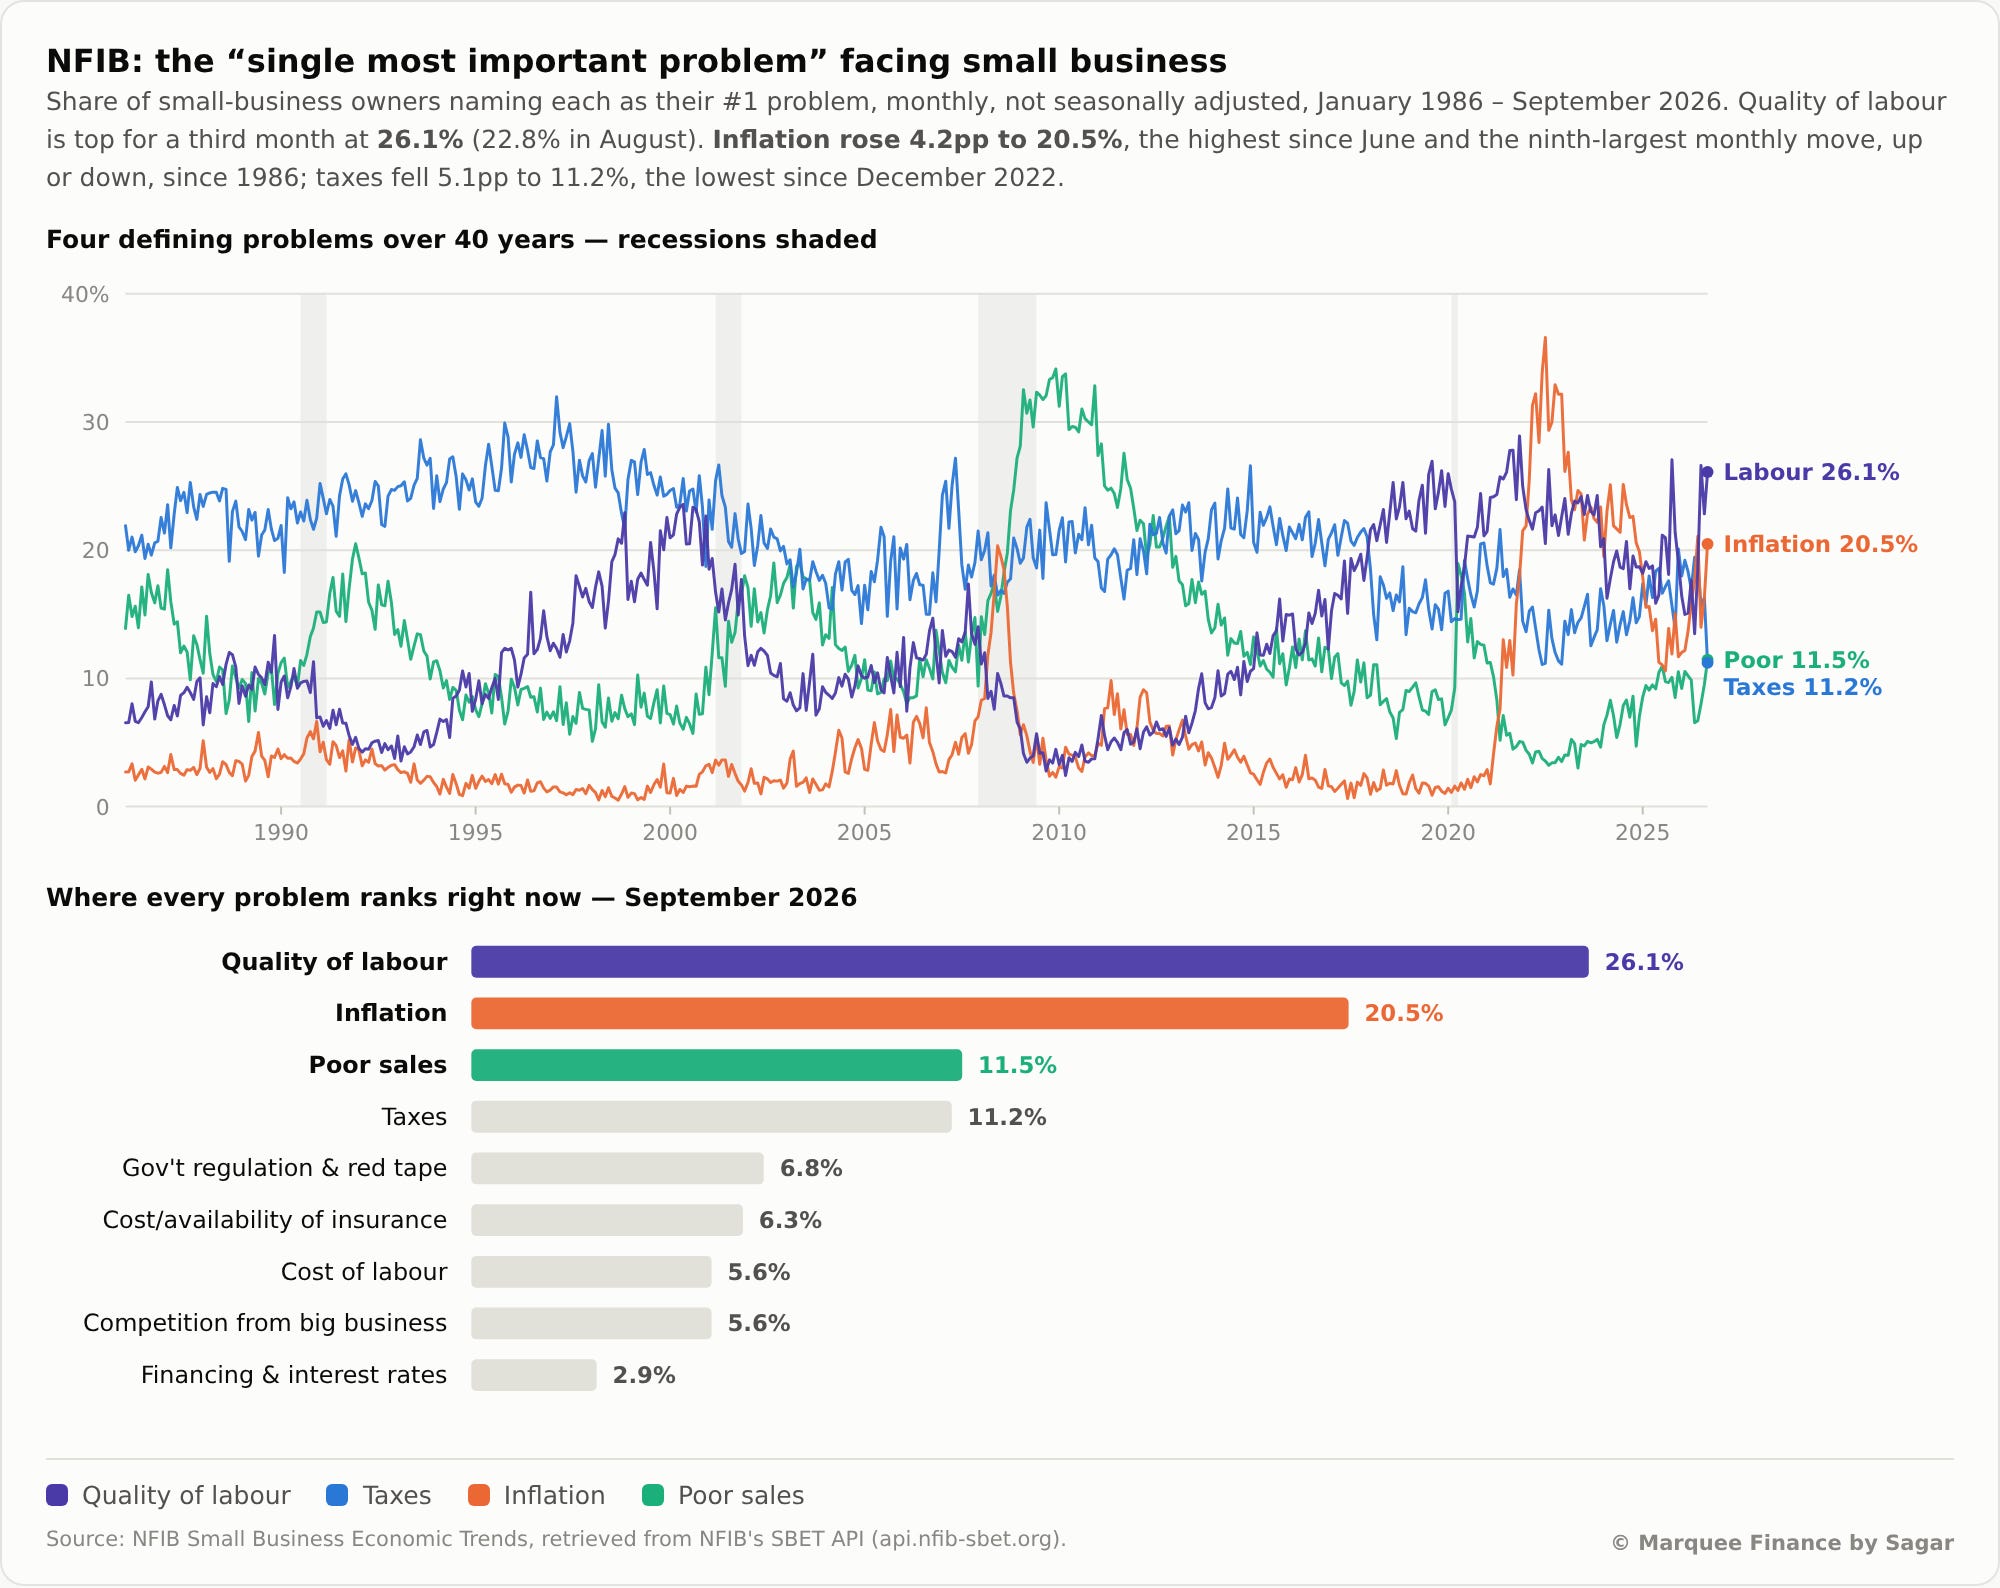
For us, poor sales as the single most important problem rising higher rang alarm bells, as it suggests higher prices are now slowing sales, which could lead to lower consumption in the future.
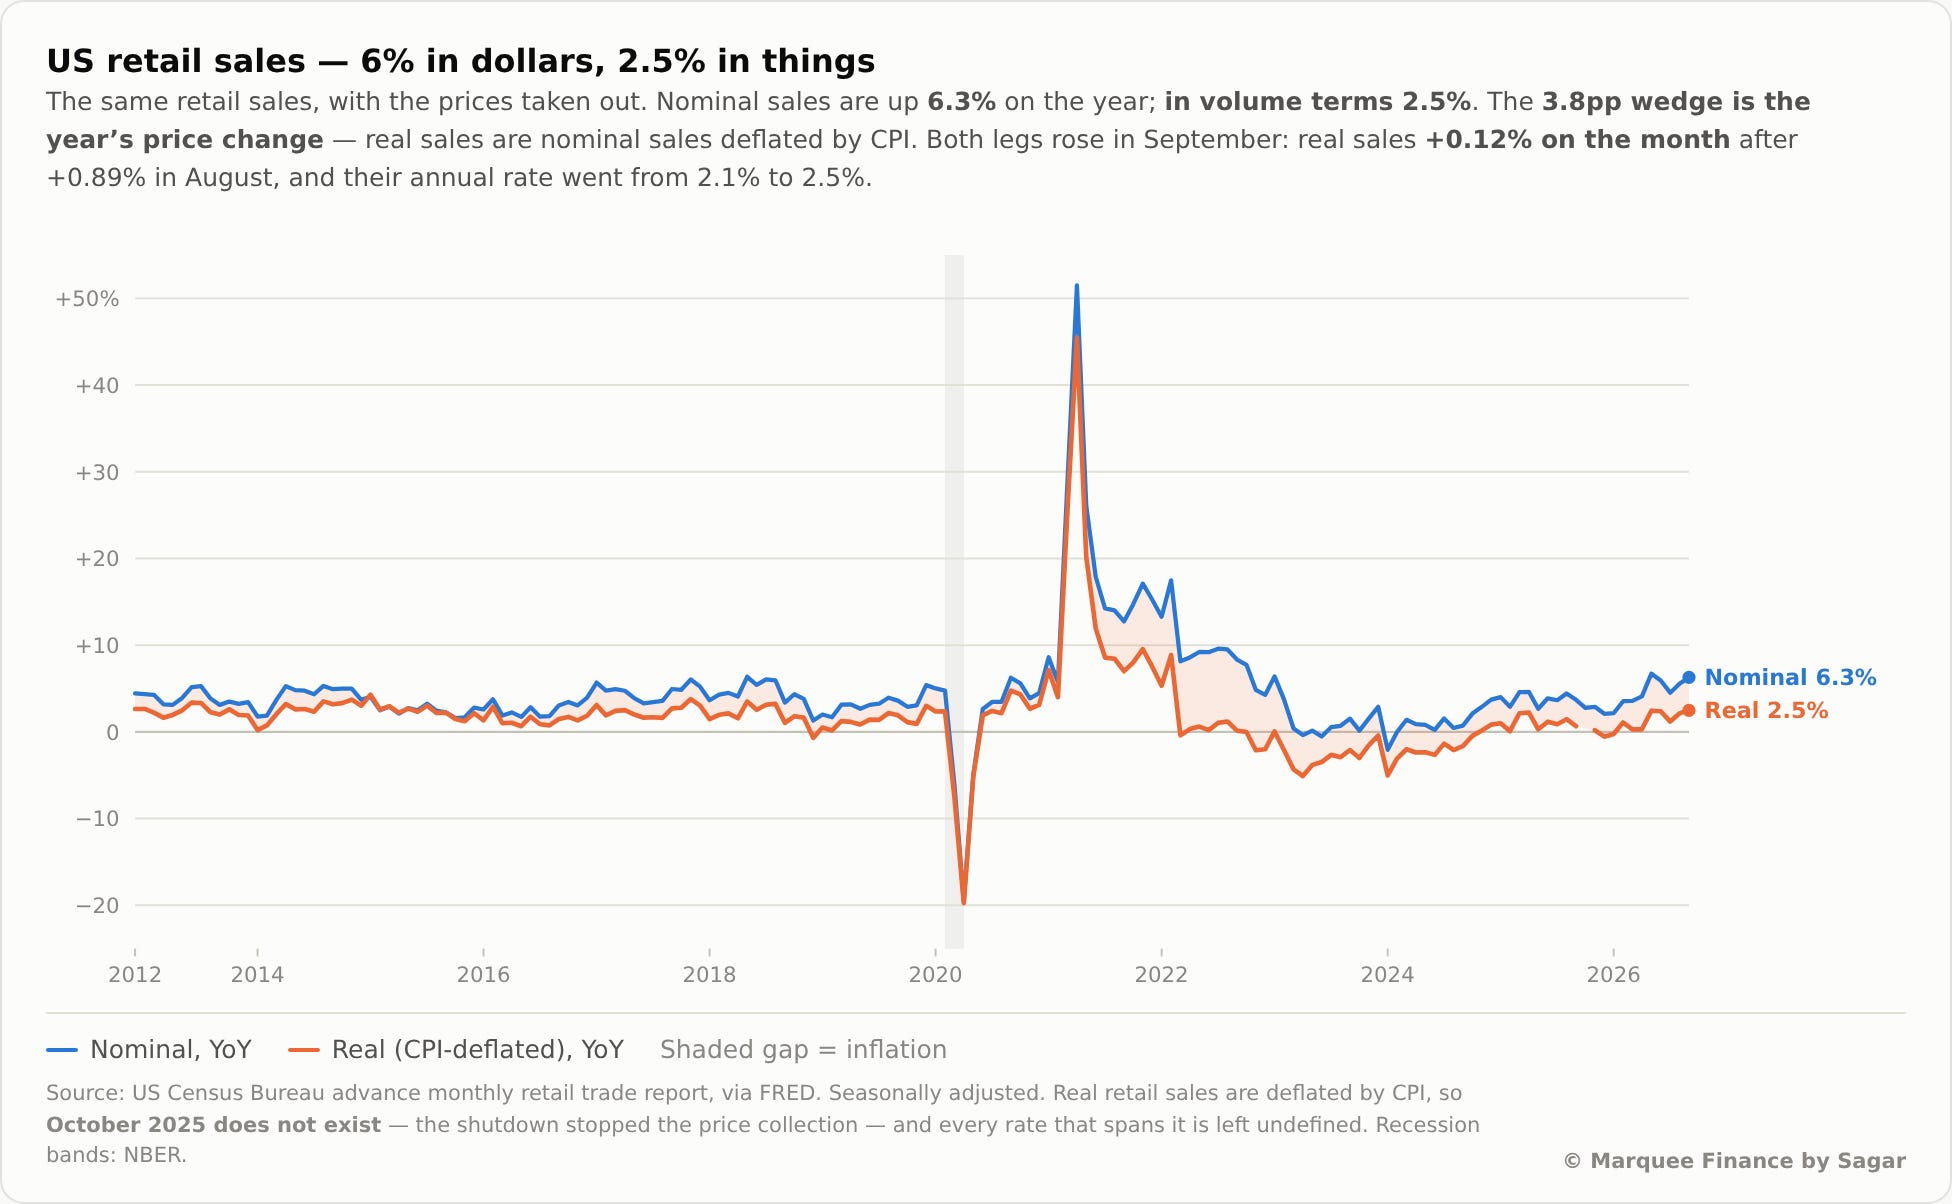
Nonetheless, as of now, consumption is holding out, with retail sales up 6.5% YoY.
However, real retail sales, adjusted for inflation, rose 2.5% YoY.
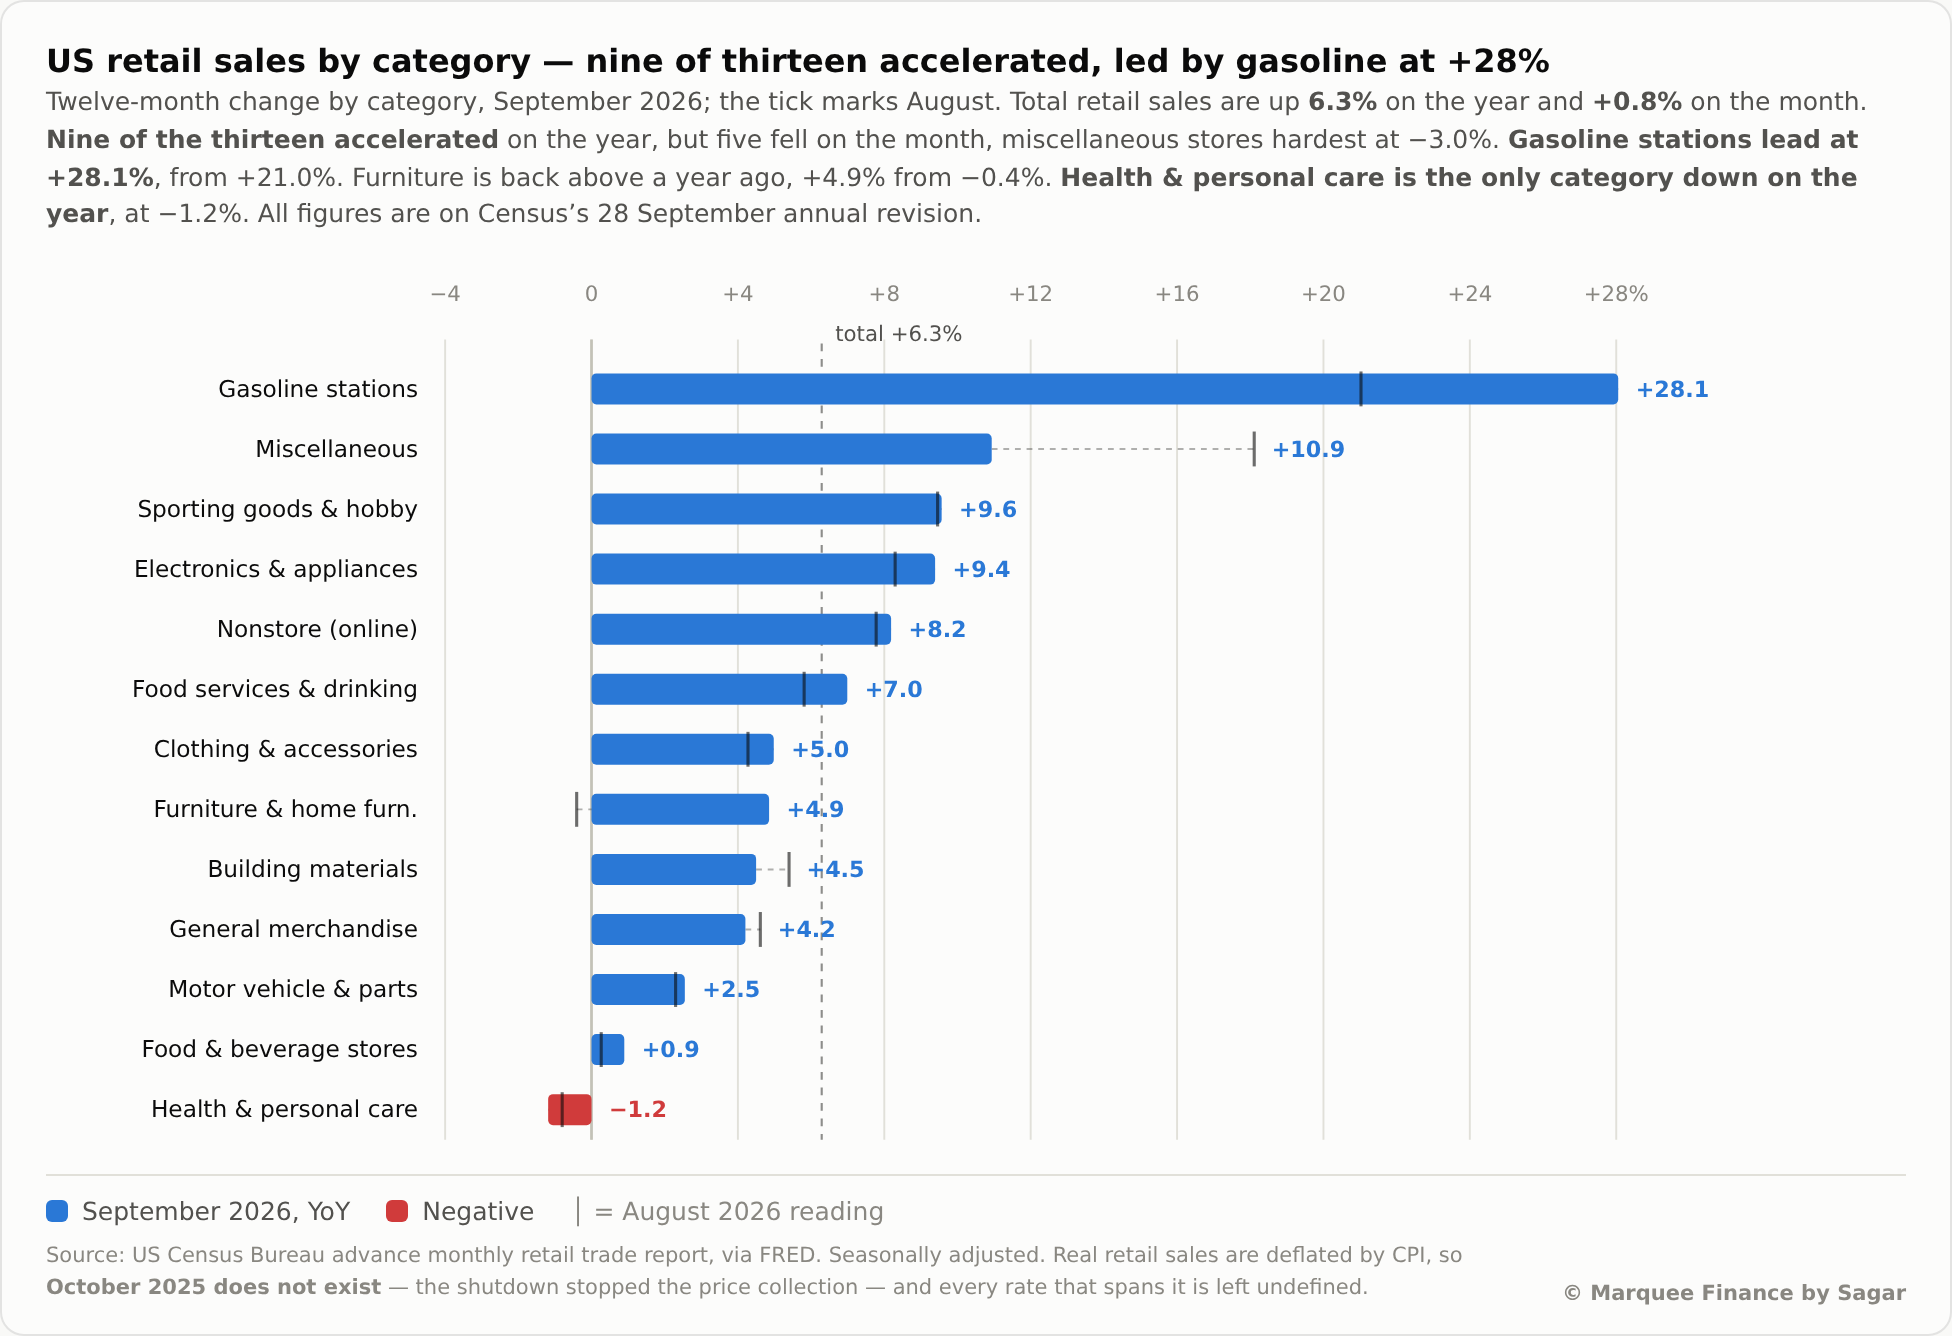
Unsurprisingly, Gasoline stations surged by 28% (thanks to higher prices).
All other goods and services segments rose, while health and personal care fell YoY.
Equities!
Multiple indicators on SPX confirm that there is a high probability we