

Last week we wrote about the unprecedented energy crisis as product prices (diesel, gasoline, jet fuel, etc.) continue to rise.
According to the data, diesel prices are more than $200/barrel; thus, WTI/Brent crude doesn’t reflect the energy crisis the world is undergoing.
Furthermore, VLCC tankers, which transport oil from the Middle East to Asia, have seen prices explode.
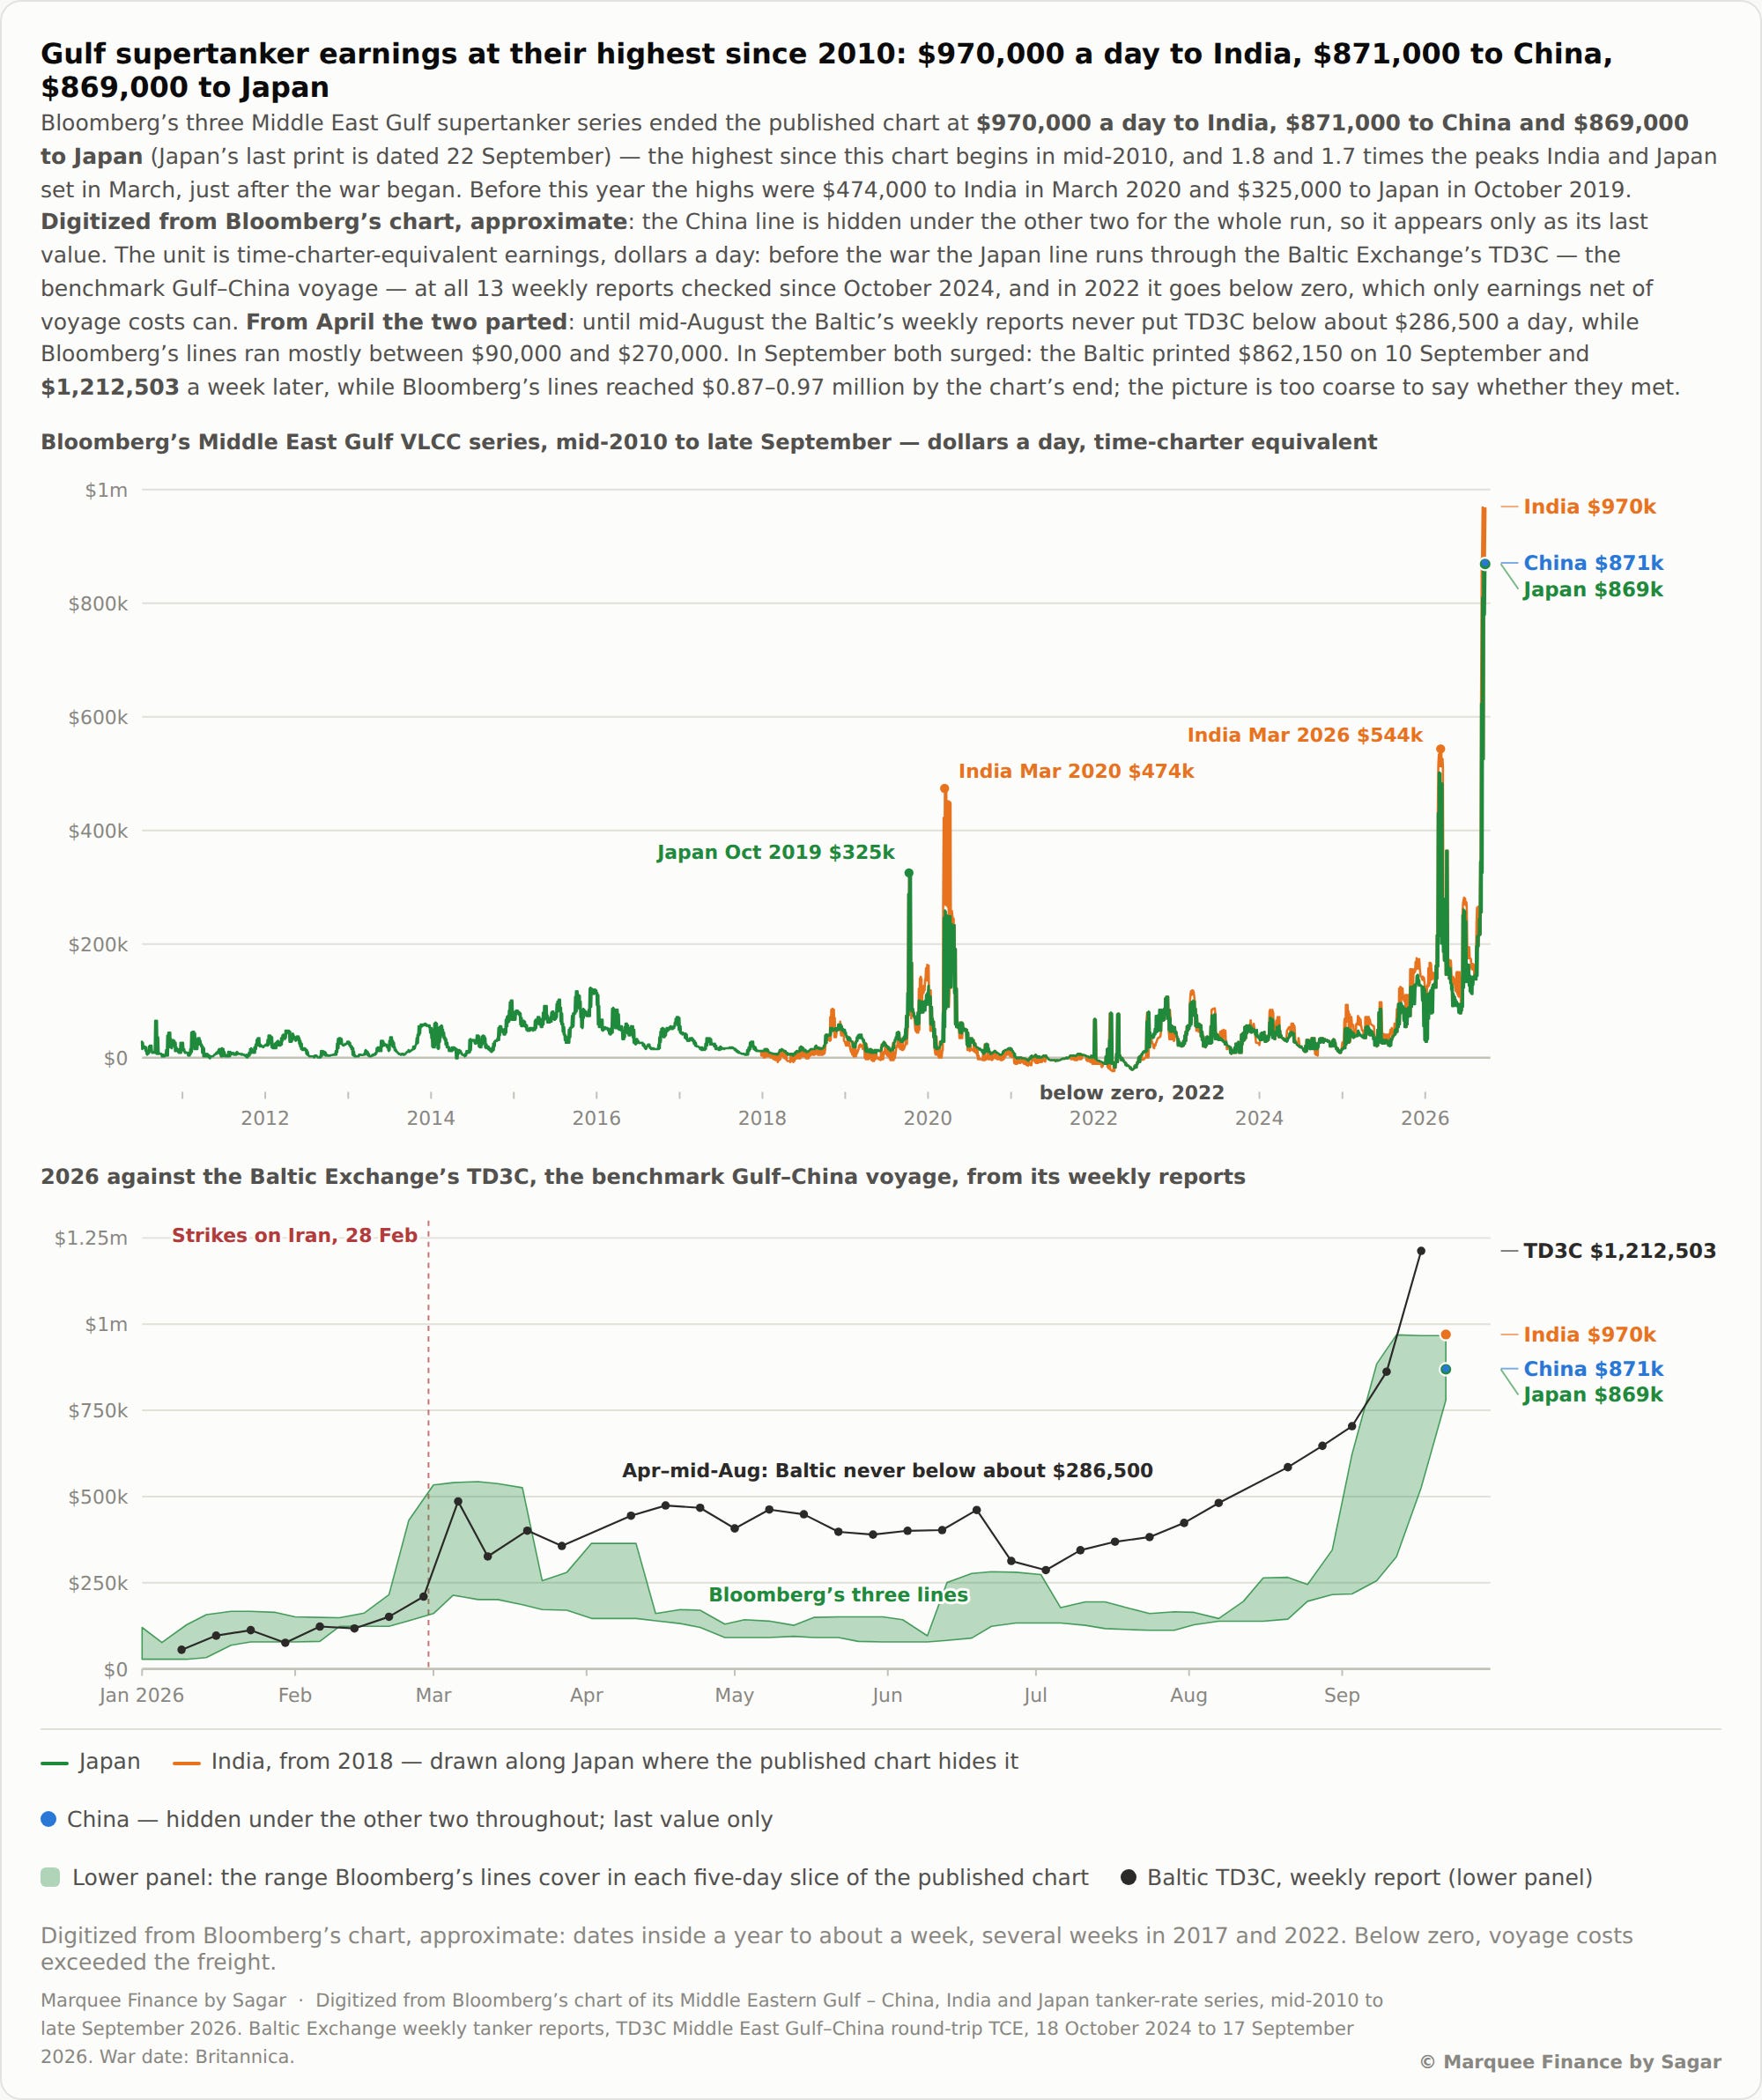
The relentless attacks on the refining infrastructure from Russia to Saudi Arabia continue.
As a result, there is no magic wand to increase refined-product production overnight.
The million-dollar question becomes: how much more will prices rise before demand takes a hit?
Previous episodes of the energy crisis show that spikes in energy prices end in a recessionary/stagflationary episode.
Will it be the same this time?
It all depends on how long the crisis lasts; thus, it’s too uncertain to predict anything today.
On the AI front, we are witnessing a historic price war as open-source models' popularity rises manifold.
AI’s price fall in the last 18 months is the fastest ever for a new technology.
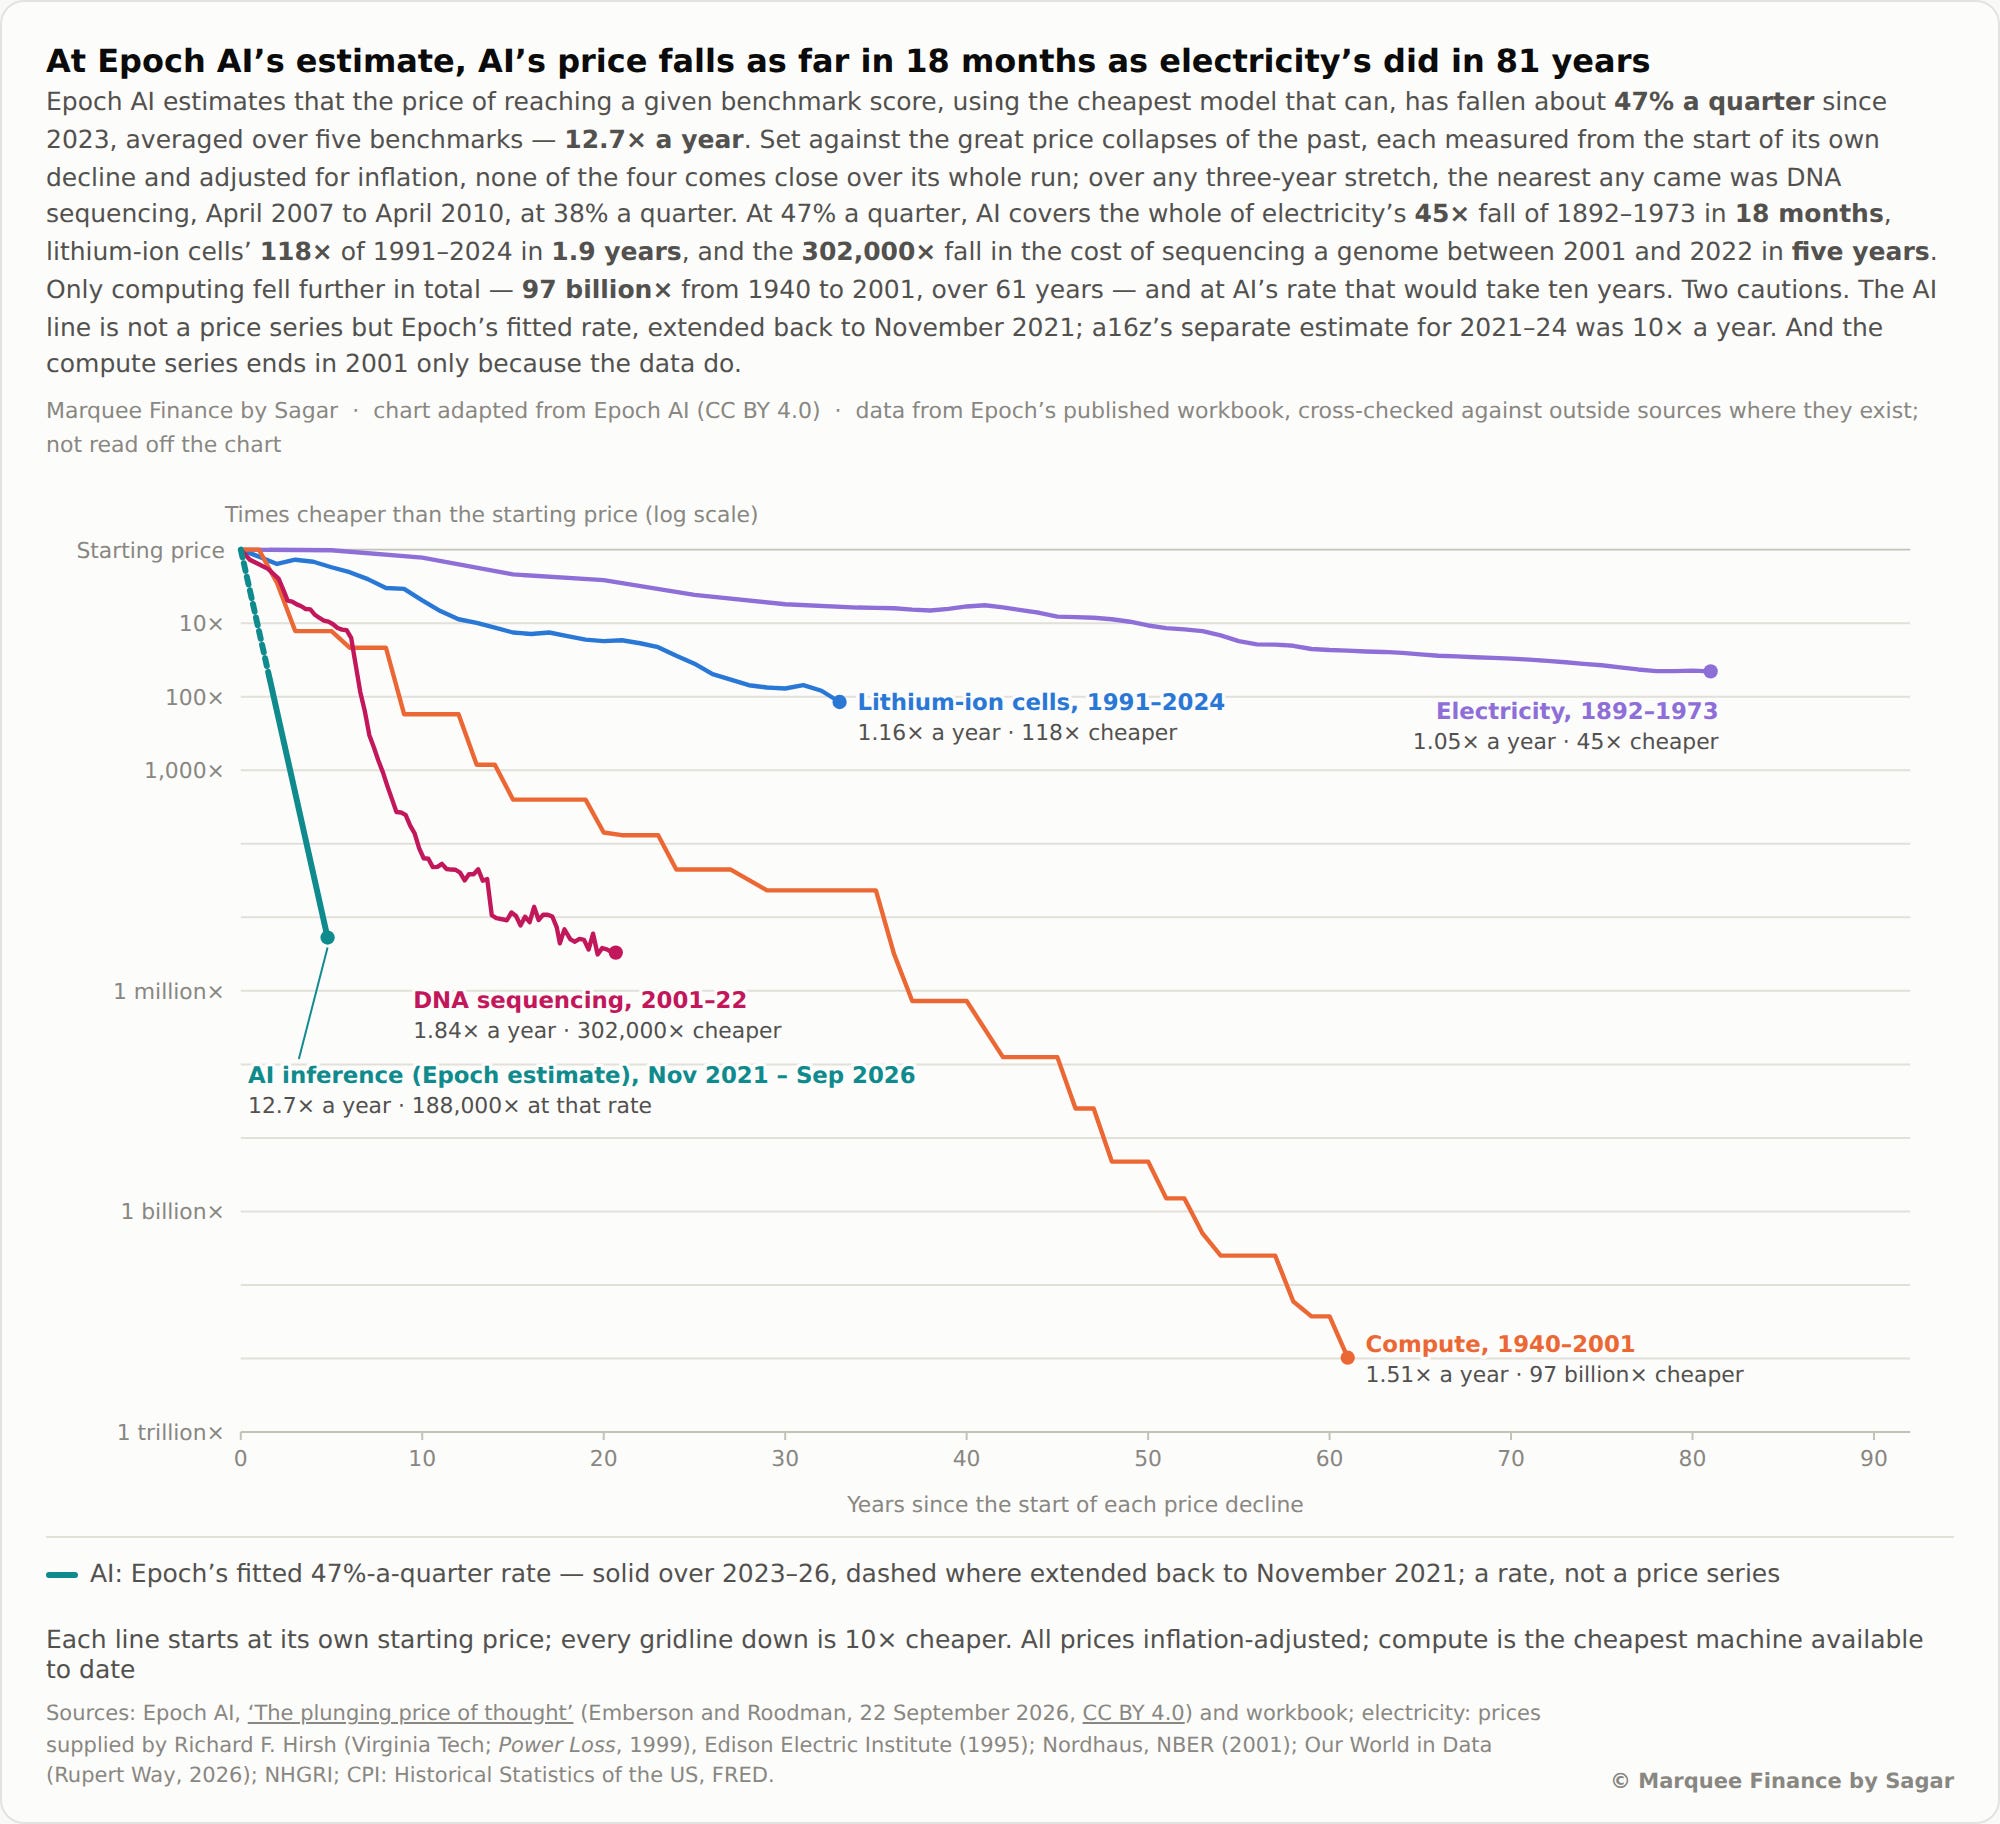
We expect the fall to continue, especially post Meta’s Muse compute offering.
Market participants suggest Meta has excess compute and is offering nearly “unlimited” tokens.
Nonetheless, with saturation in model development (in terms of intelligence), the focus will now shift to competitive intensity and profitability, along with AI enterprise adoption, which is still in single digits.
2026 has been one of the toughest years for investors and traders alike as historical macro correlations broke in real time.
We are at a 60% hit rate, with an average winner at 6.96% and an average loser at -4.14%.
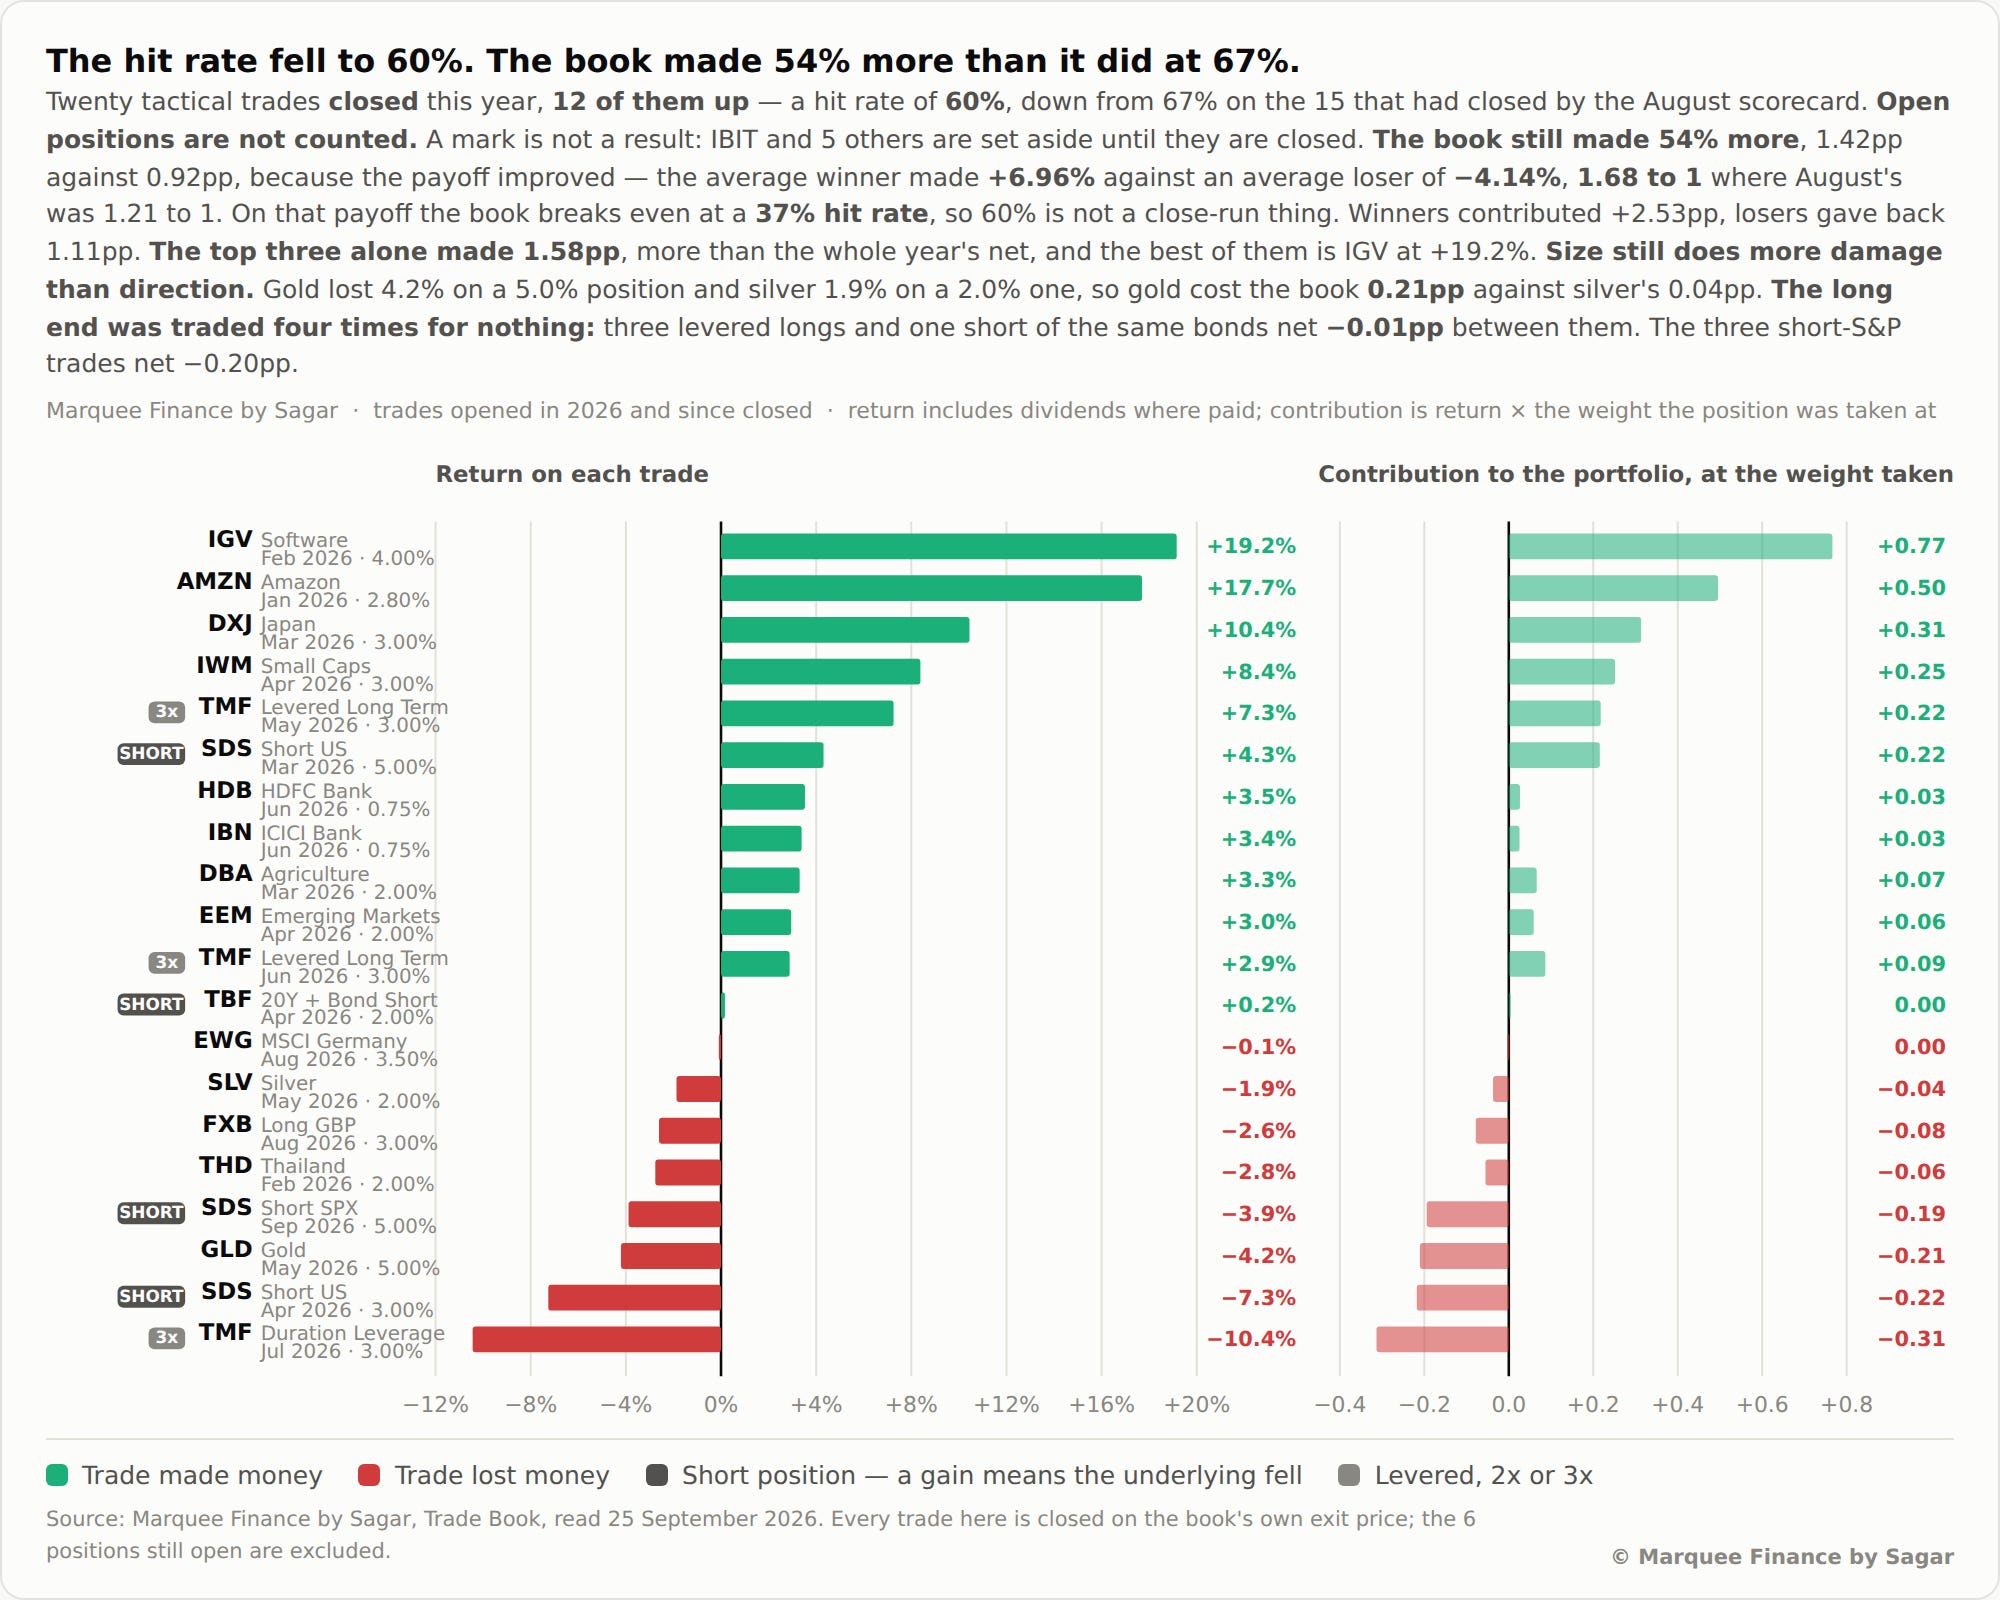
We are up 4.72% YTD, and September has been one of the worst months, as equity markets have disappointed, with the index up only due to a handful of stocks while broader markets have underperformed.

Let us take a deep dive into the macro universe and comprehend the cross-asset price action.
Macro!
US!
It was a data-light week, and ex-housing data; one of the most important data point was durable goods data.
Durable goods non-defence ex-air came in at 1.6% v/s 0.6 expected and surged to a record $87.6 billion.
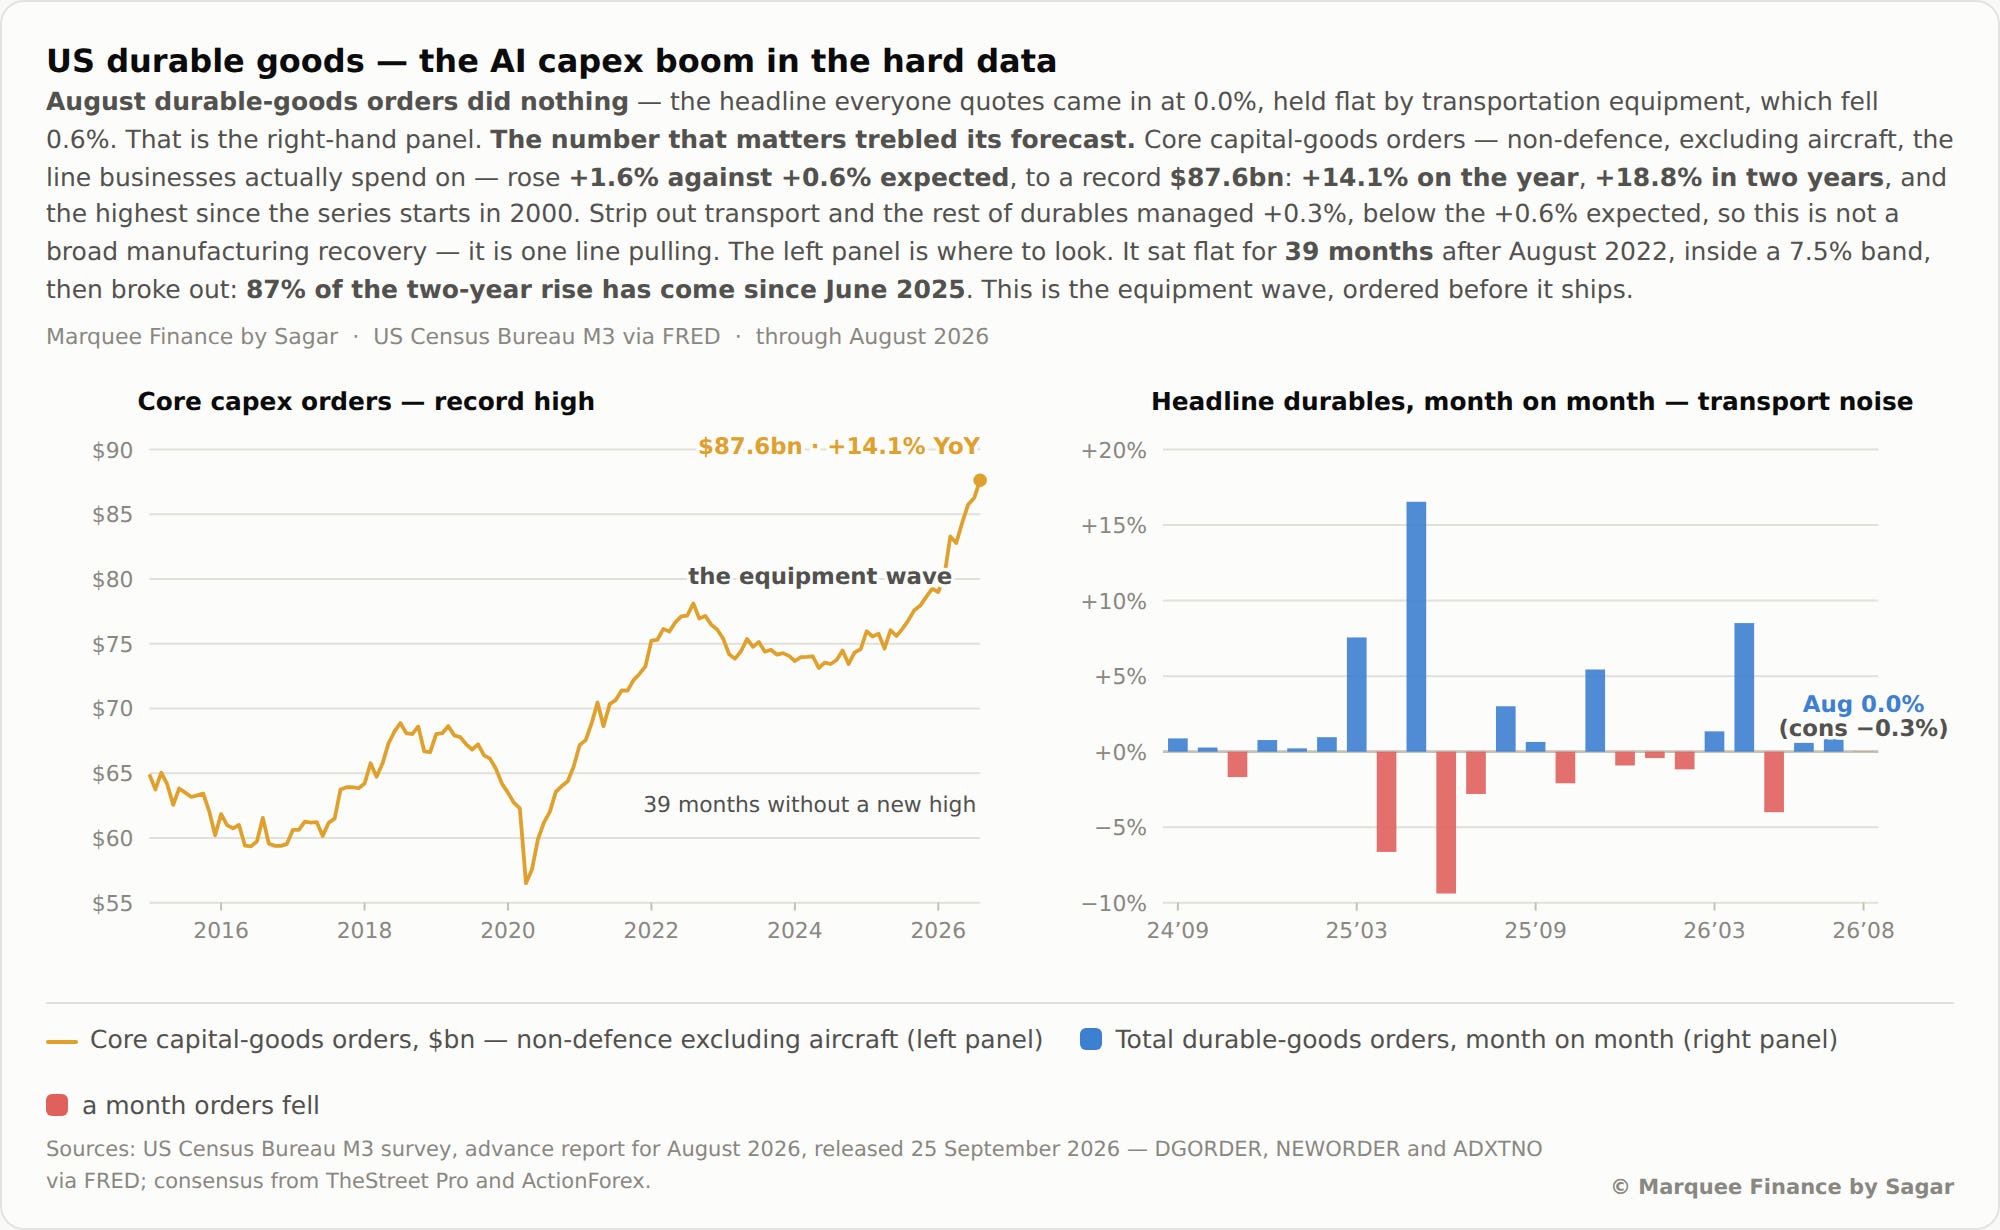
The surge, as we have been indicating in the past months, is led by the AI wave.
Since hyperscaler capex has not slowed yet, we expect durable goods orders to continue moving higher in the coming months.
Germany!
Soft data in Germany continues to improve, and higher energy prices have yet to dampen sentiment.
The IFO business climate moved further higher to 89.9.
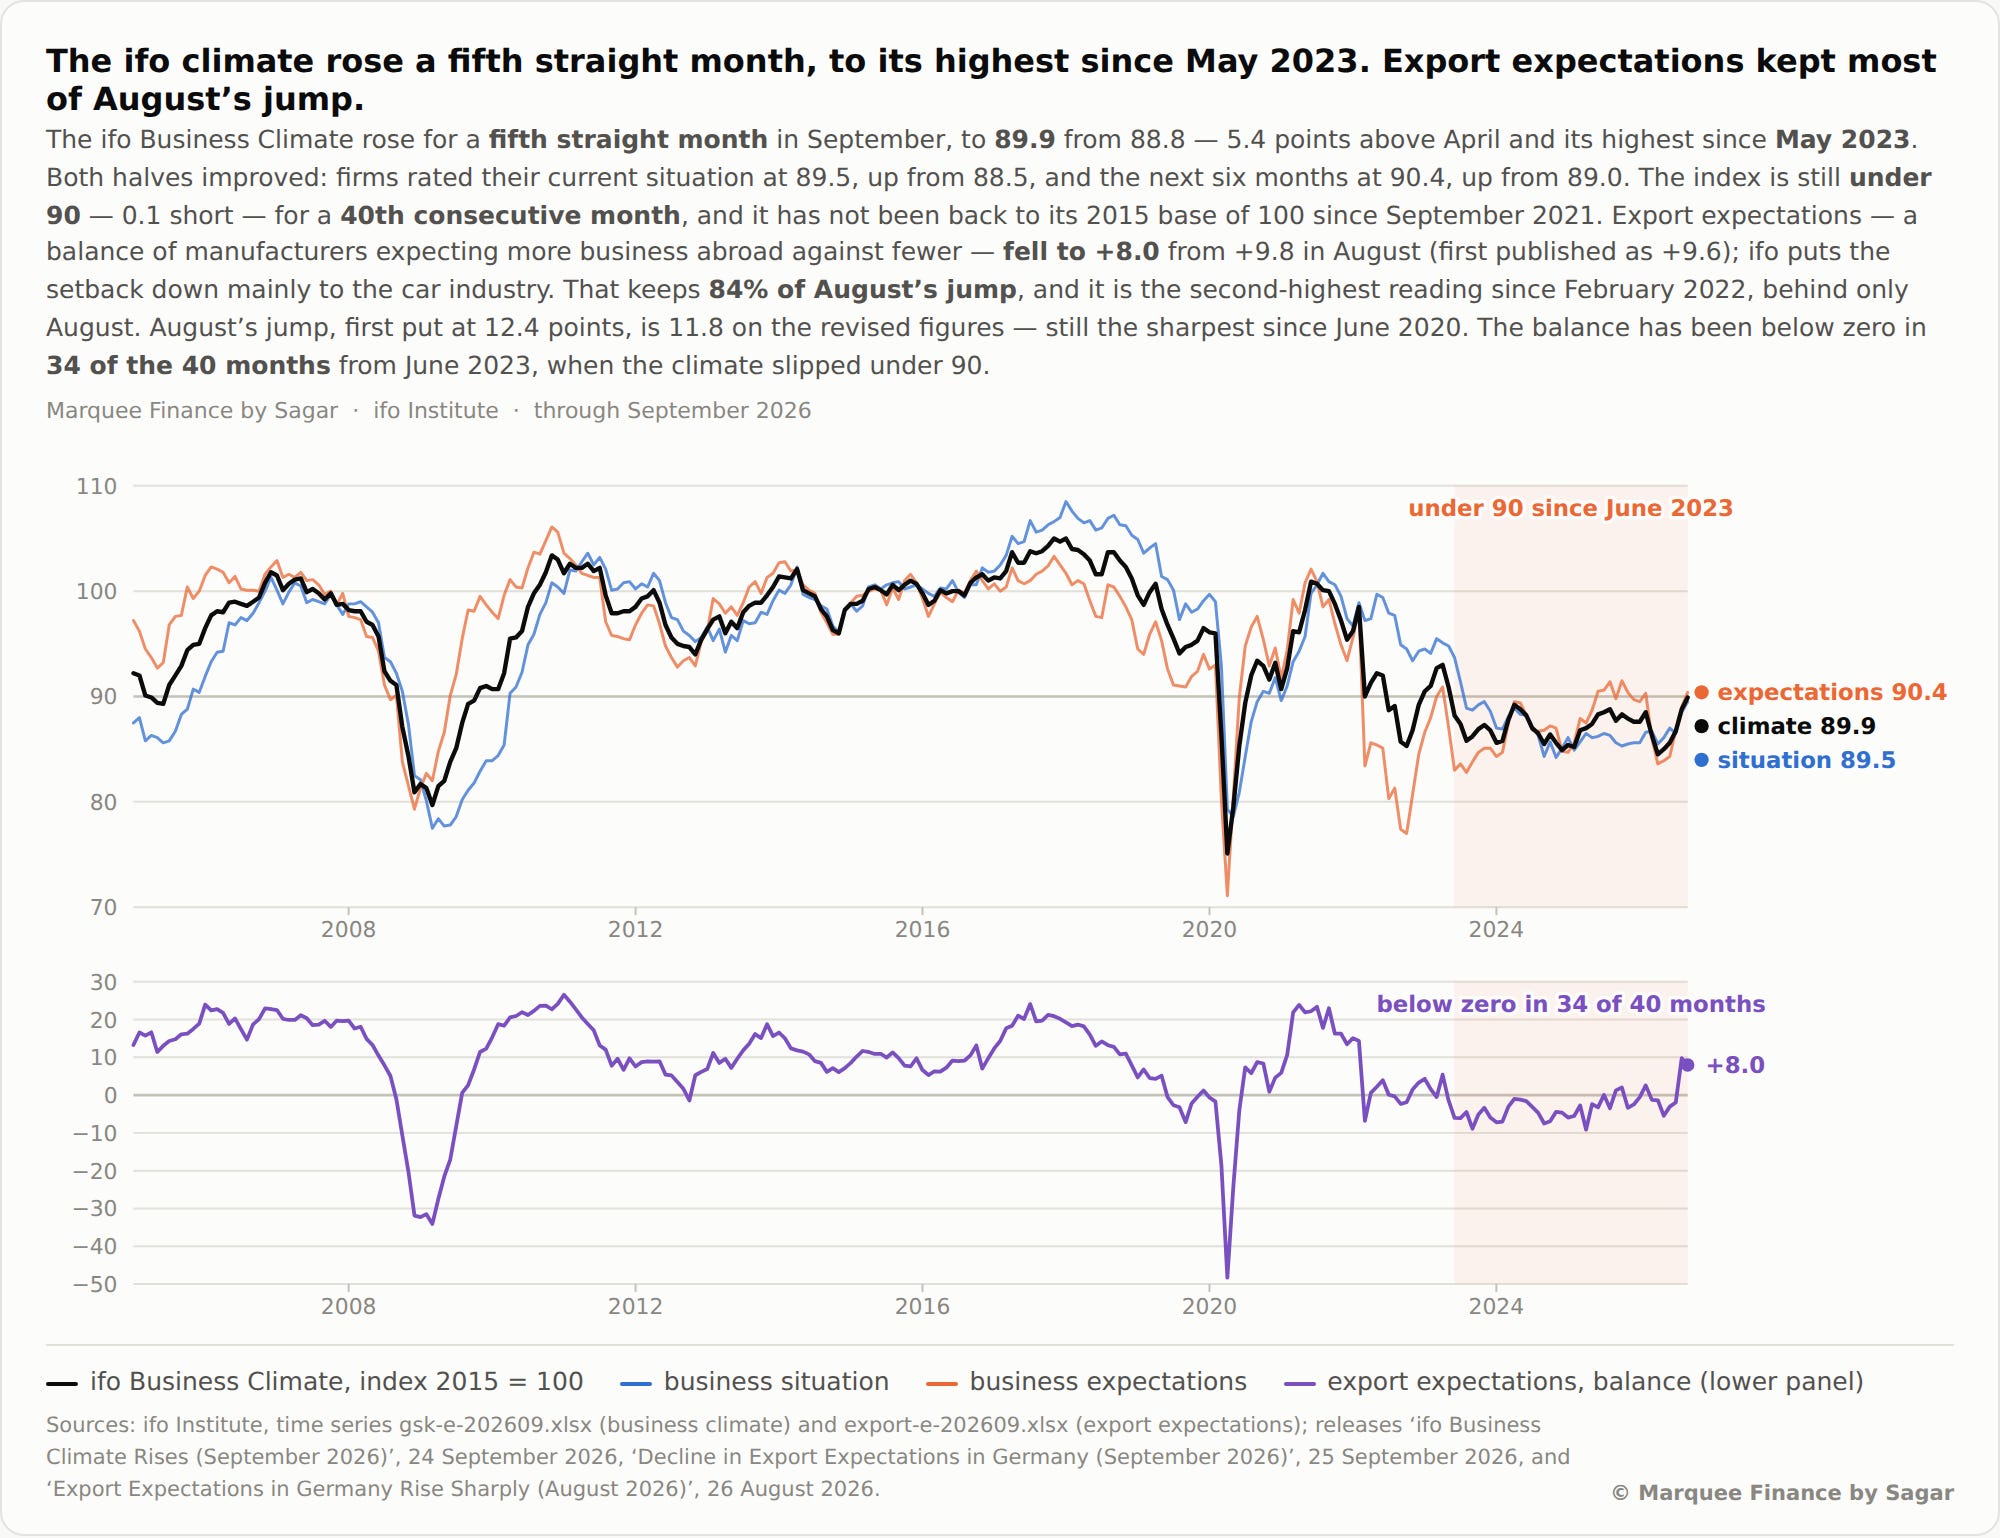
With a sustained rise in refined products and natural gas prices, we expect the sentiment to turn sour in the coming months.
On the flip side, if energy prices move lower (resolution of Russia/Iran conflicts), expect the IFO to surpass the 90 threshold.
Equities!
Before we discuss our PF and returns YTD, we would like to shed some light on the AI bubble and market breadth.
The hyperscalers' off-balance-sheet commitments have now skyrocketed to more than $3 trillion.
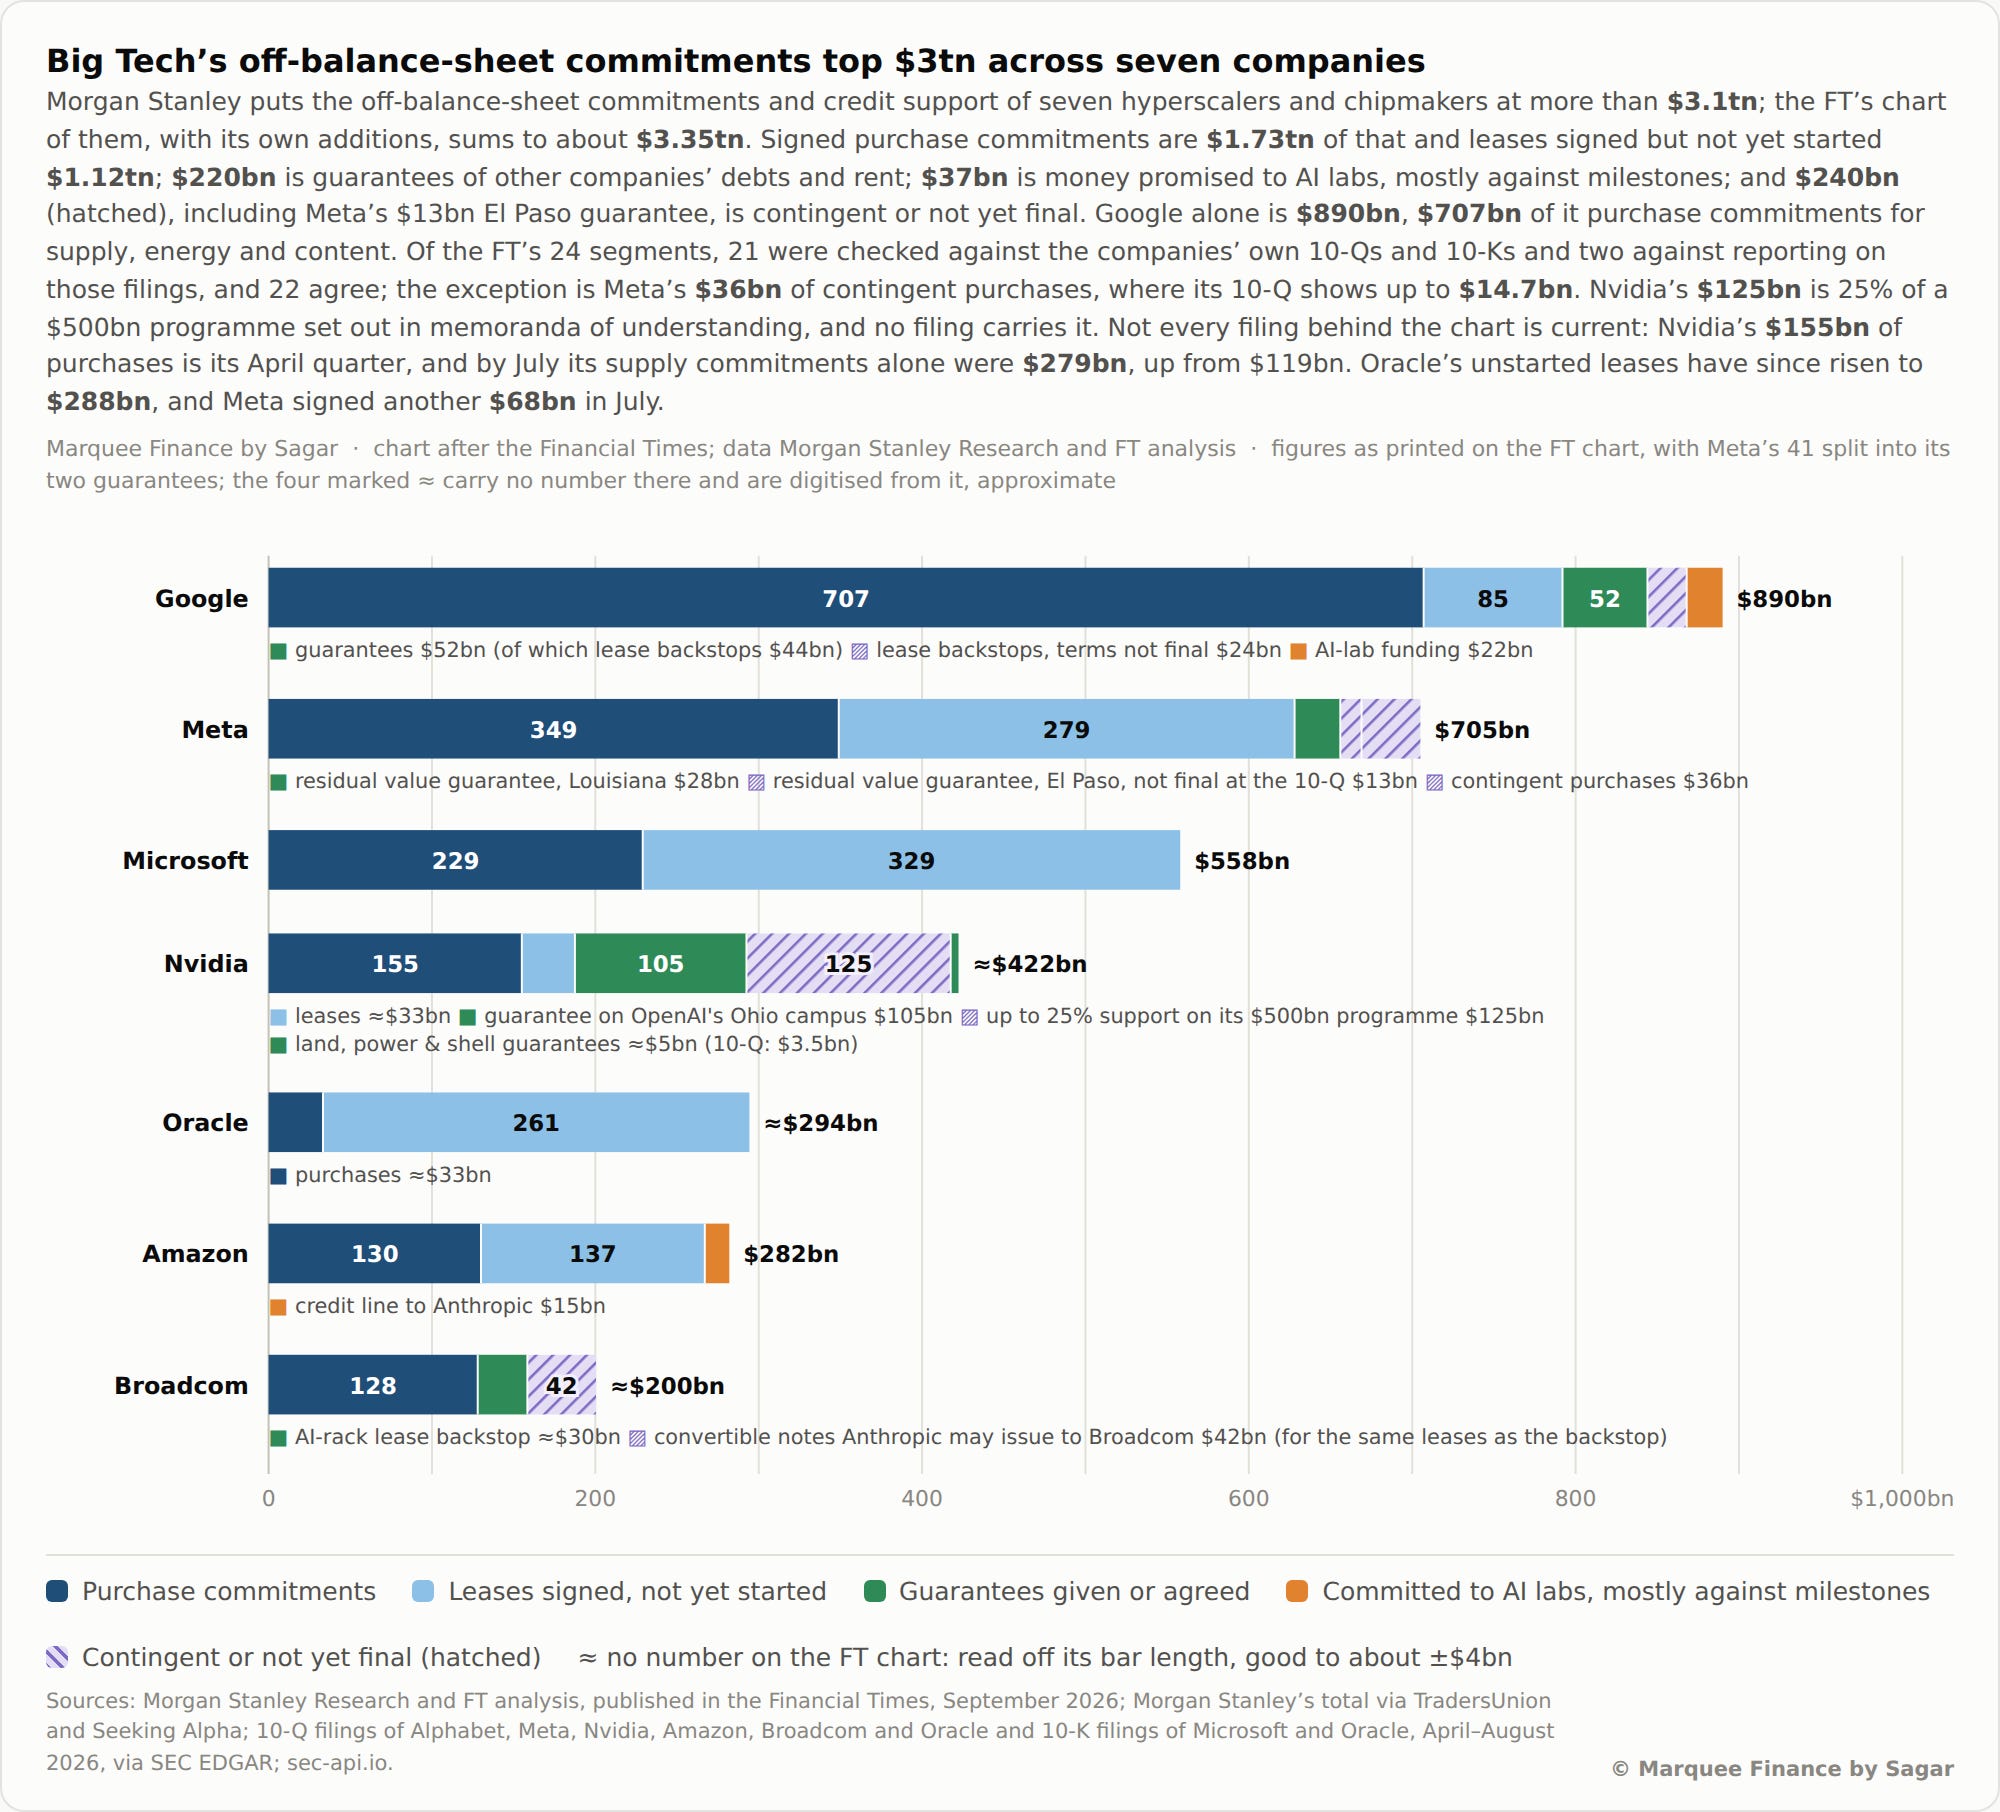
This, along with prospects of lower ROI on the enormous capex, remains the biggest risk to the US equity markets.
Furthermore, CDS on hyperscaler debt remains elevated as market participants continue to hedge AI equity and debt exposure via CDS.
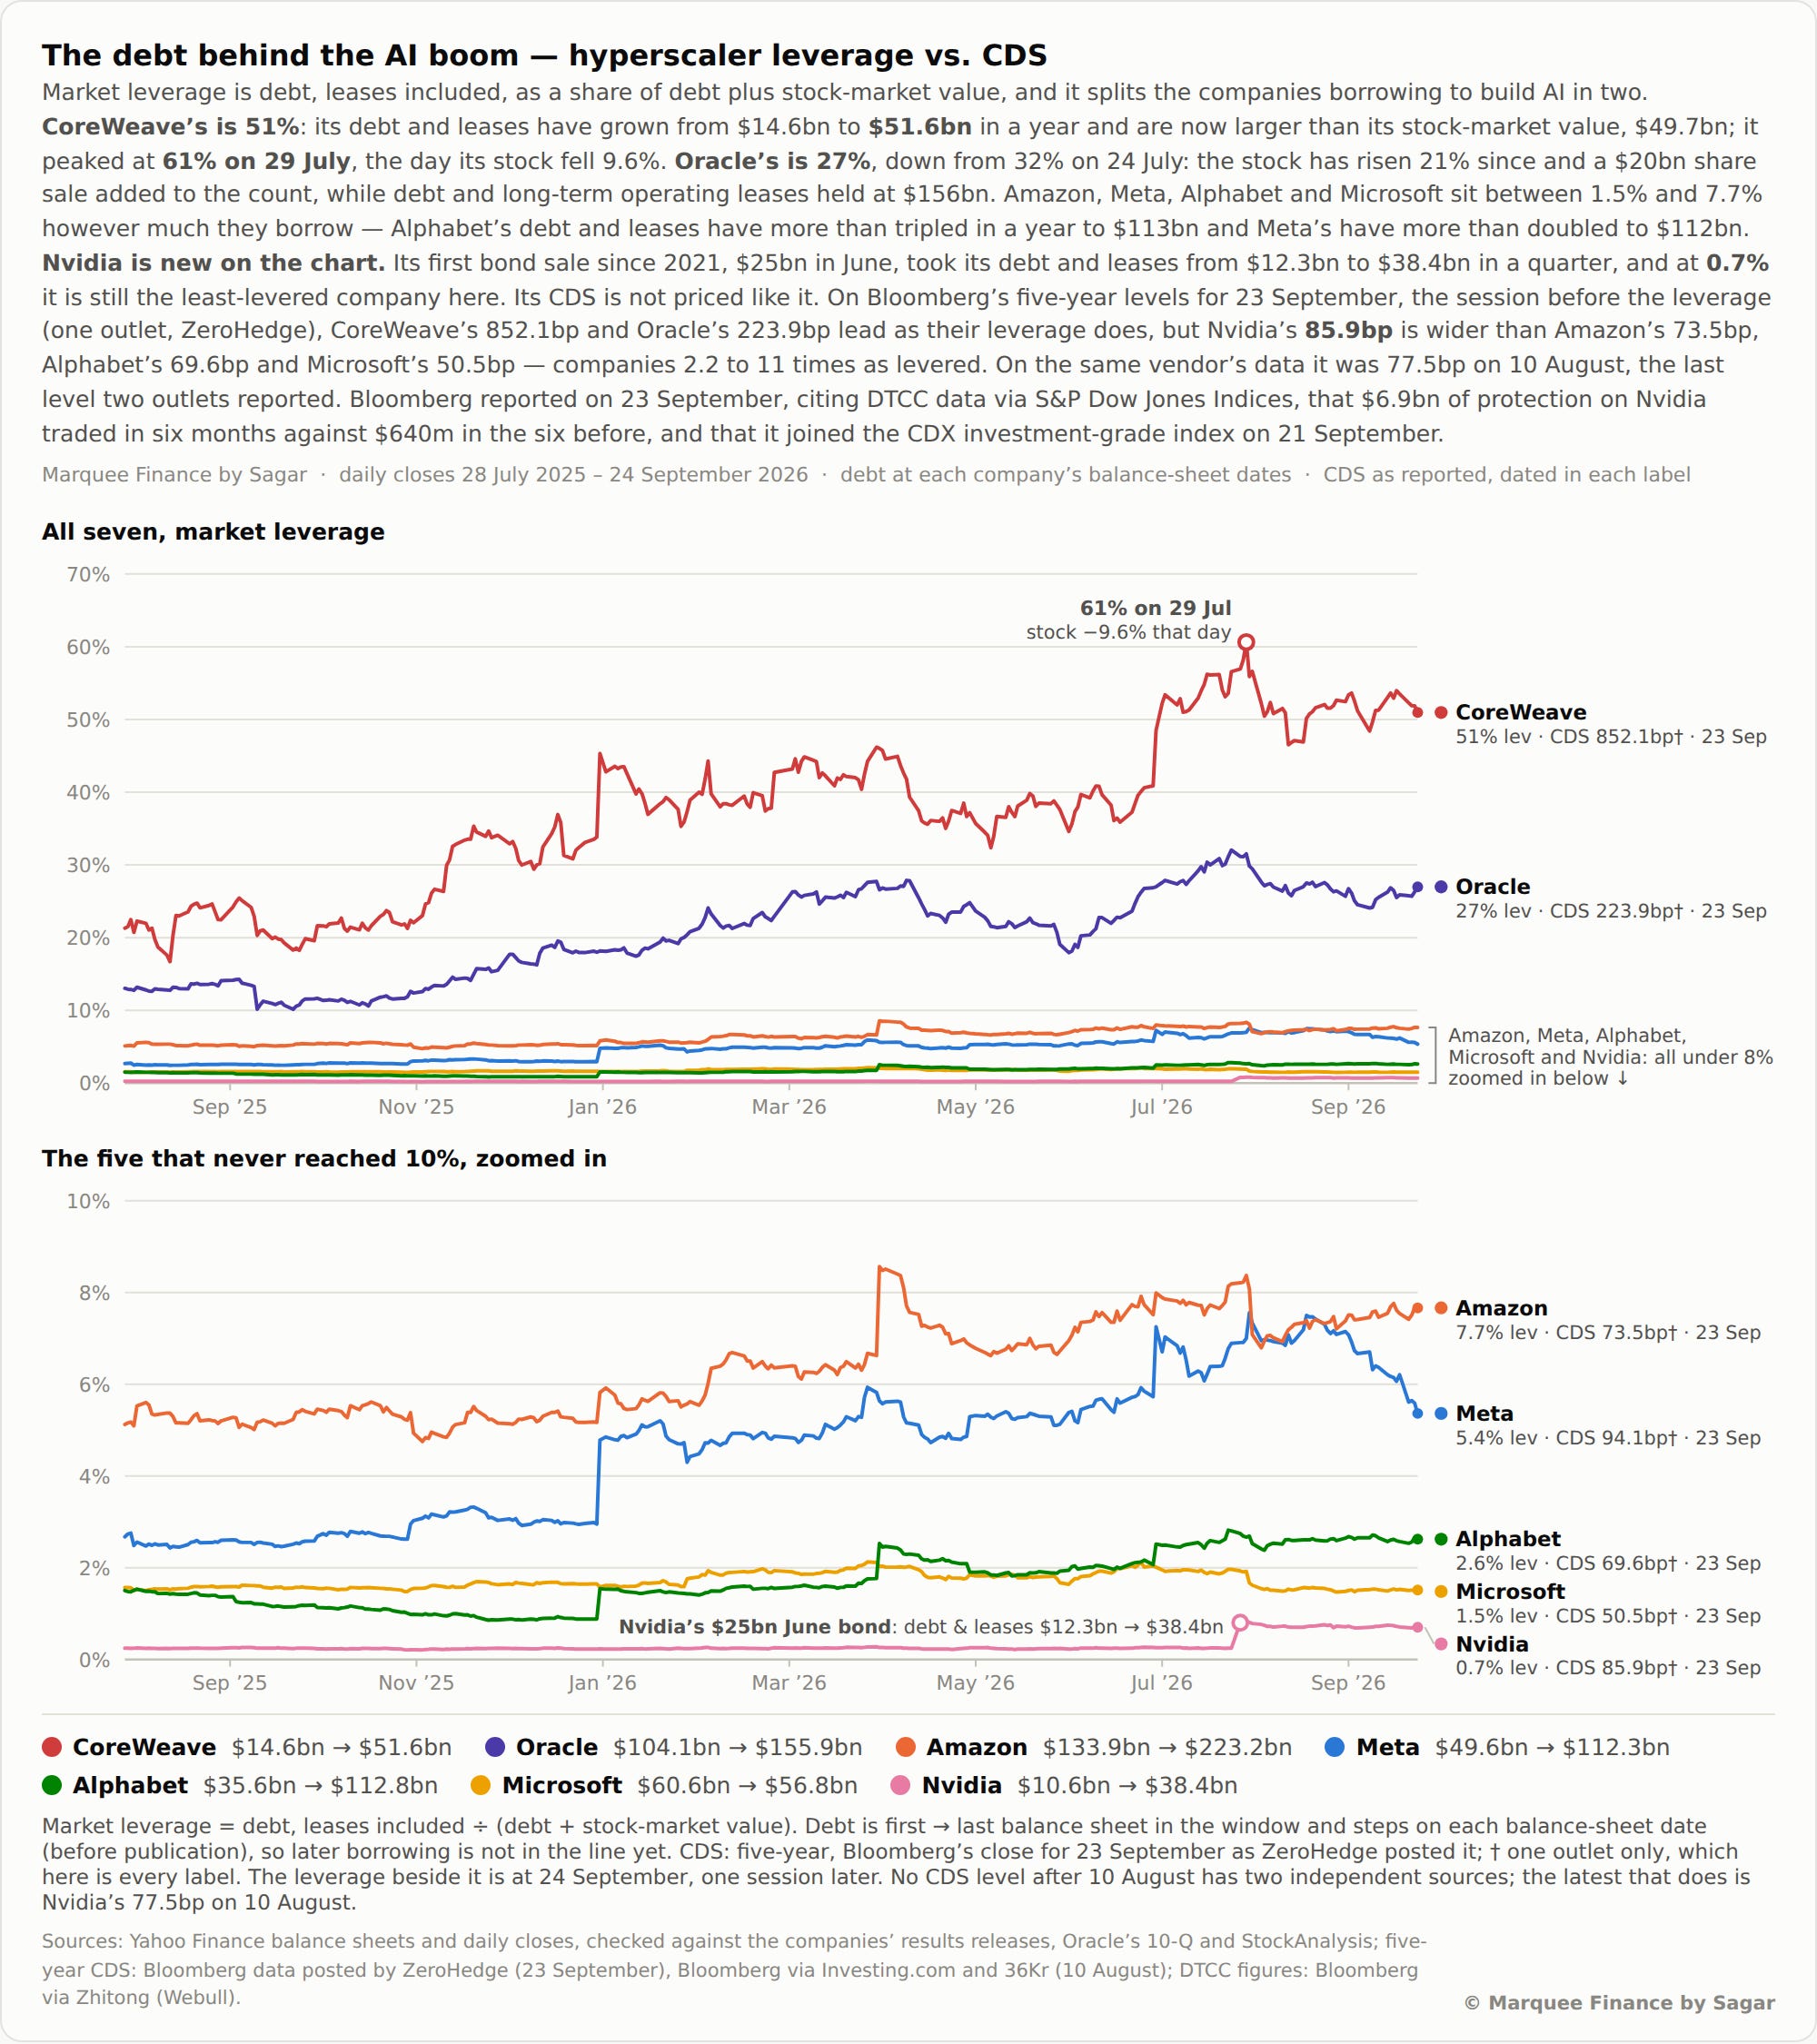
We remain well hedged, as our paid subscribers are aware and as our PF shows.
As of Thursday's close, the market breadth has deteriorated to alarming levels.
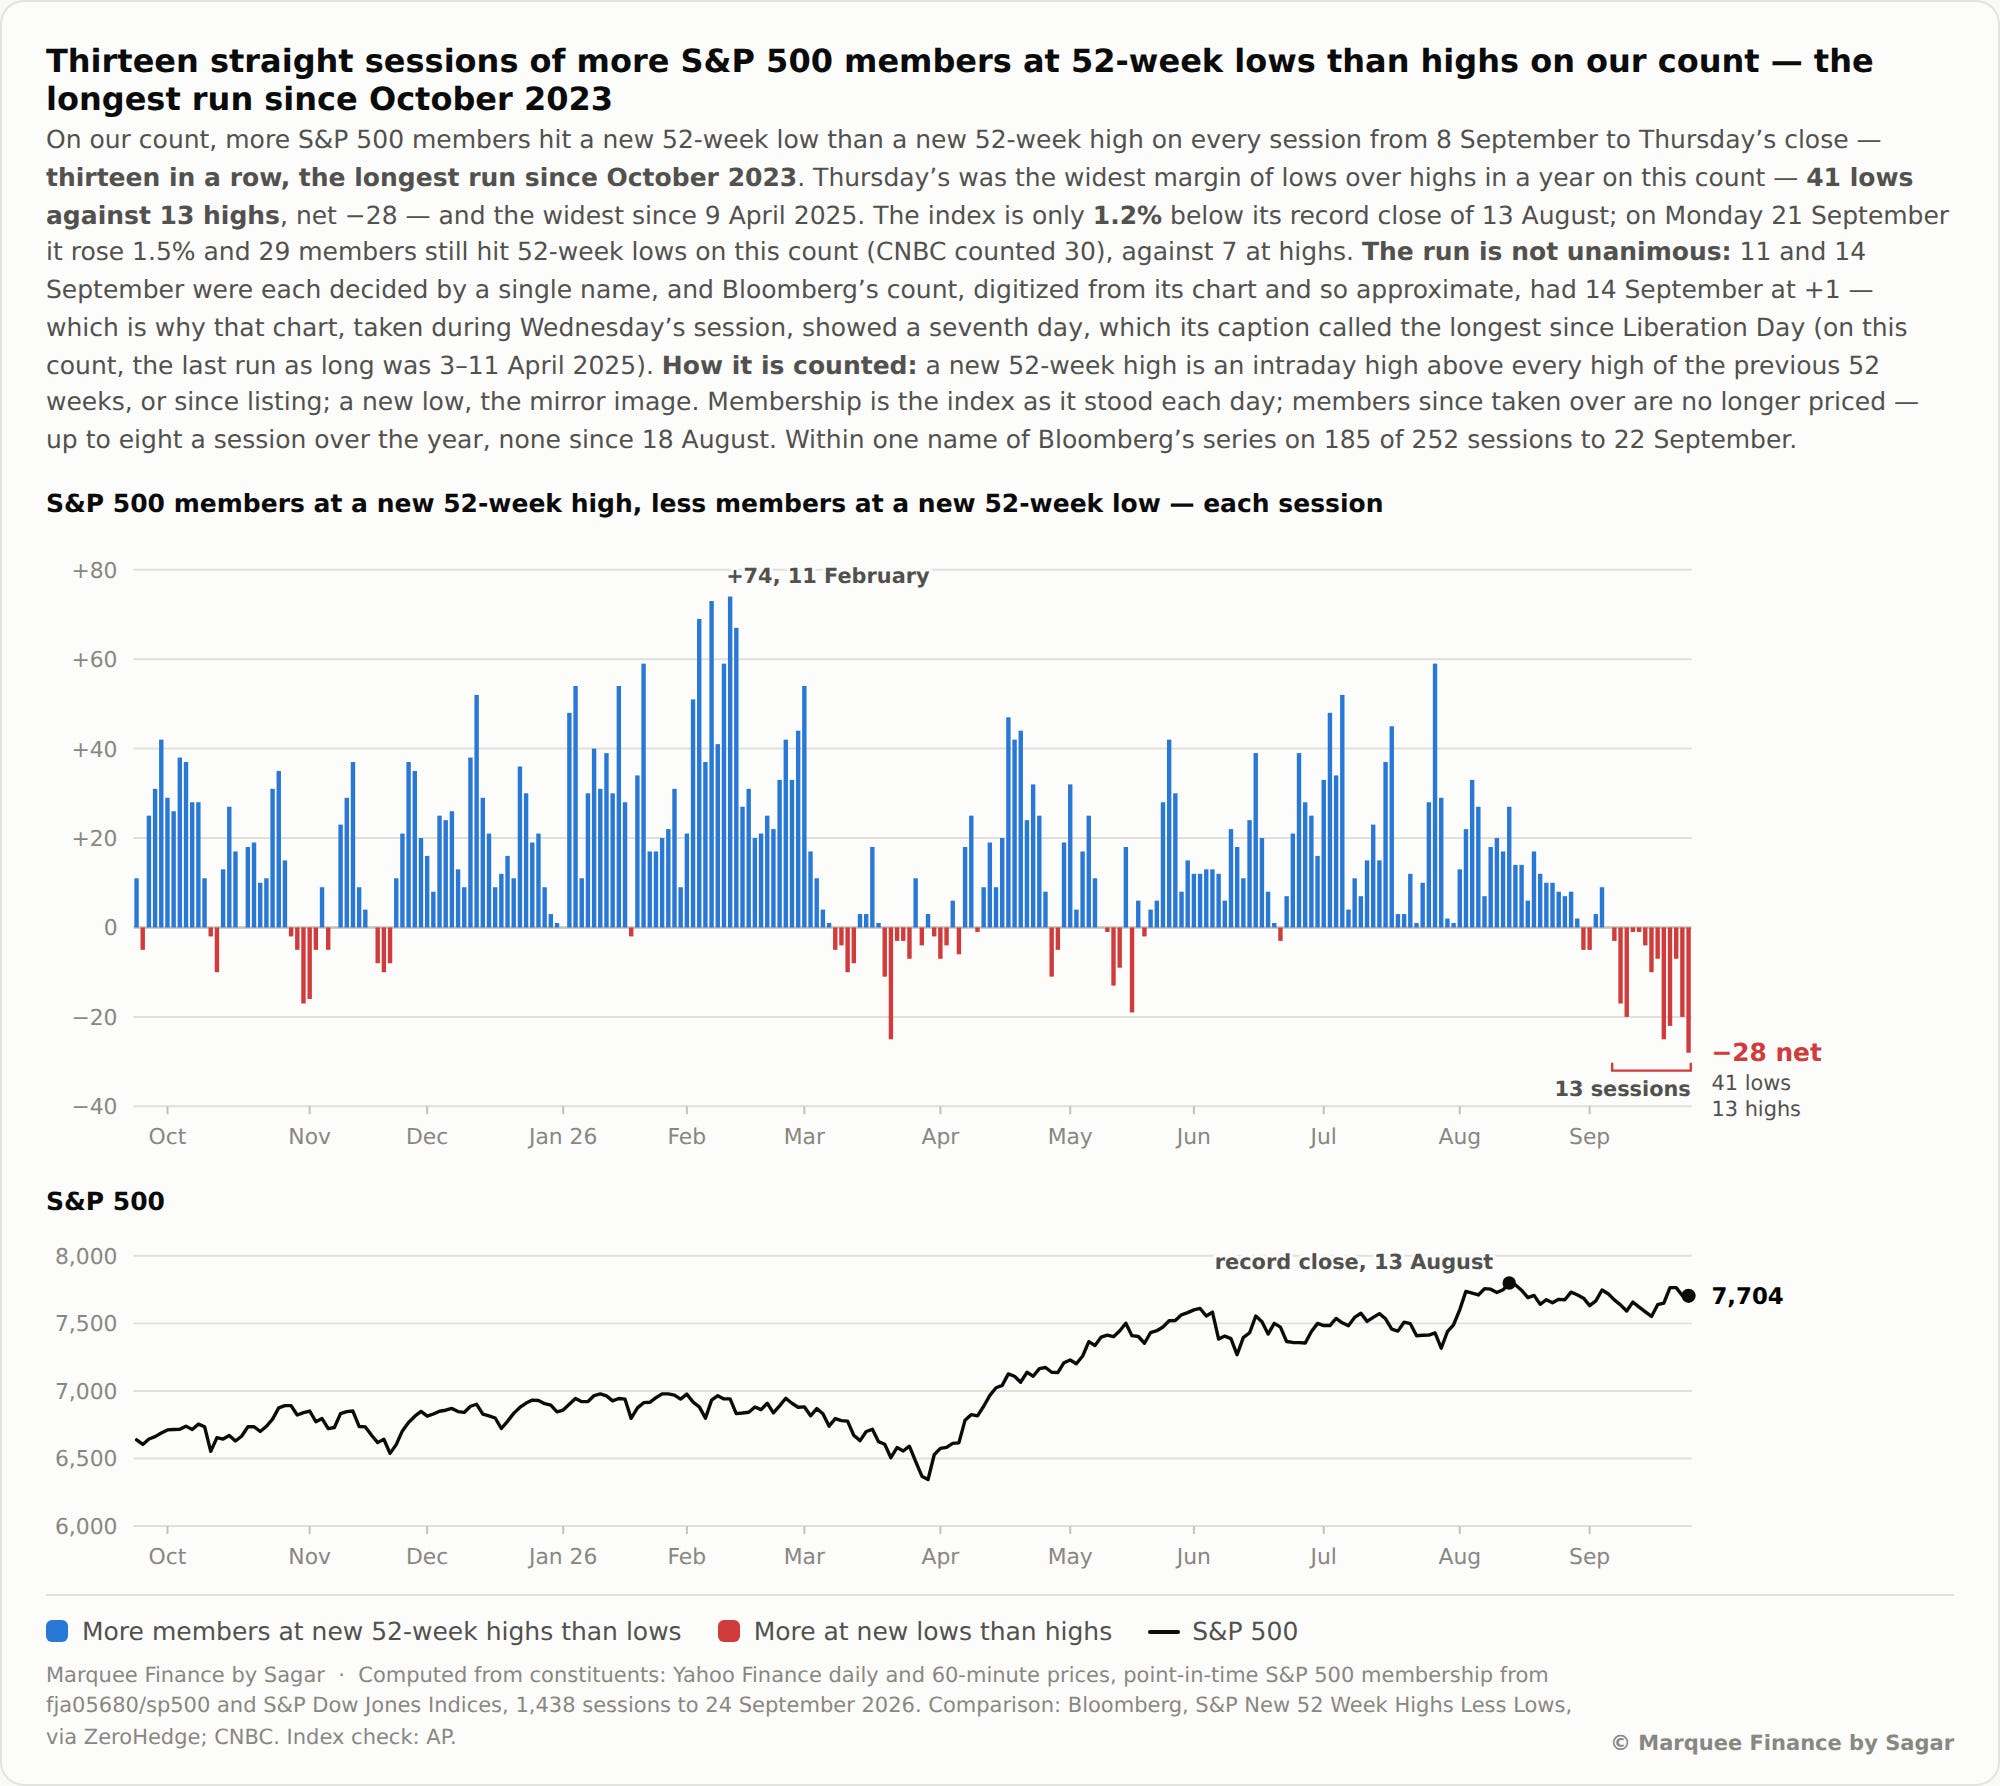
For thirteen consecutive sessions, more S&P500 members hit new 52 Week lows than a new 52 Week high.
The equity book as of yesterday's close: