

In 2022, we saw a tech winter driven by the “fear” that higher rates would lower earnings for big Tech firms and that the US economy would enter a recession.
Nonetheless, the bear market gave rise to a mega bull market as higher rates became a blessing in disguise for cash-rich tech companies.
Furthermore, the launch of ChatGPT and the subsequent AI wave drove trillions of dollars in hyperscalers’ spending, creating generational wealth across a spectrum of companies, from semis to cables to HVAC.
We are now at an inflection point as competitive intensity erodes frontier models' profitability.
We've seen this over the past few months, as open-source Chinese models took the AI ecosystem by storm.
While AI token usage has continued to surge and hit a record high, token spend is down 10% from the 27th July peak.
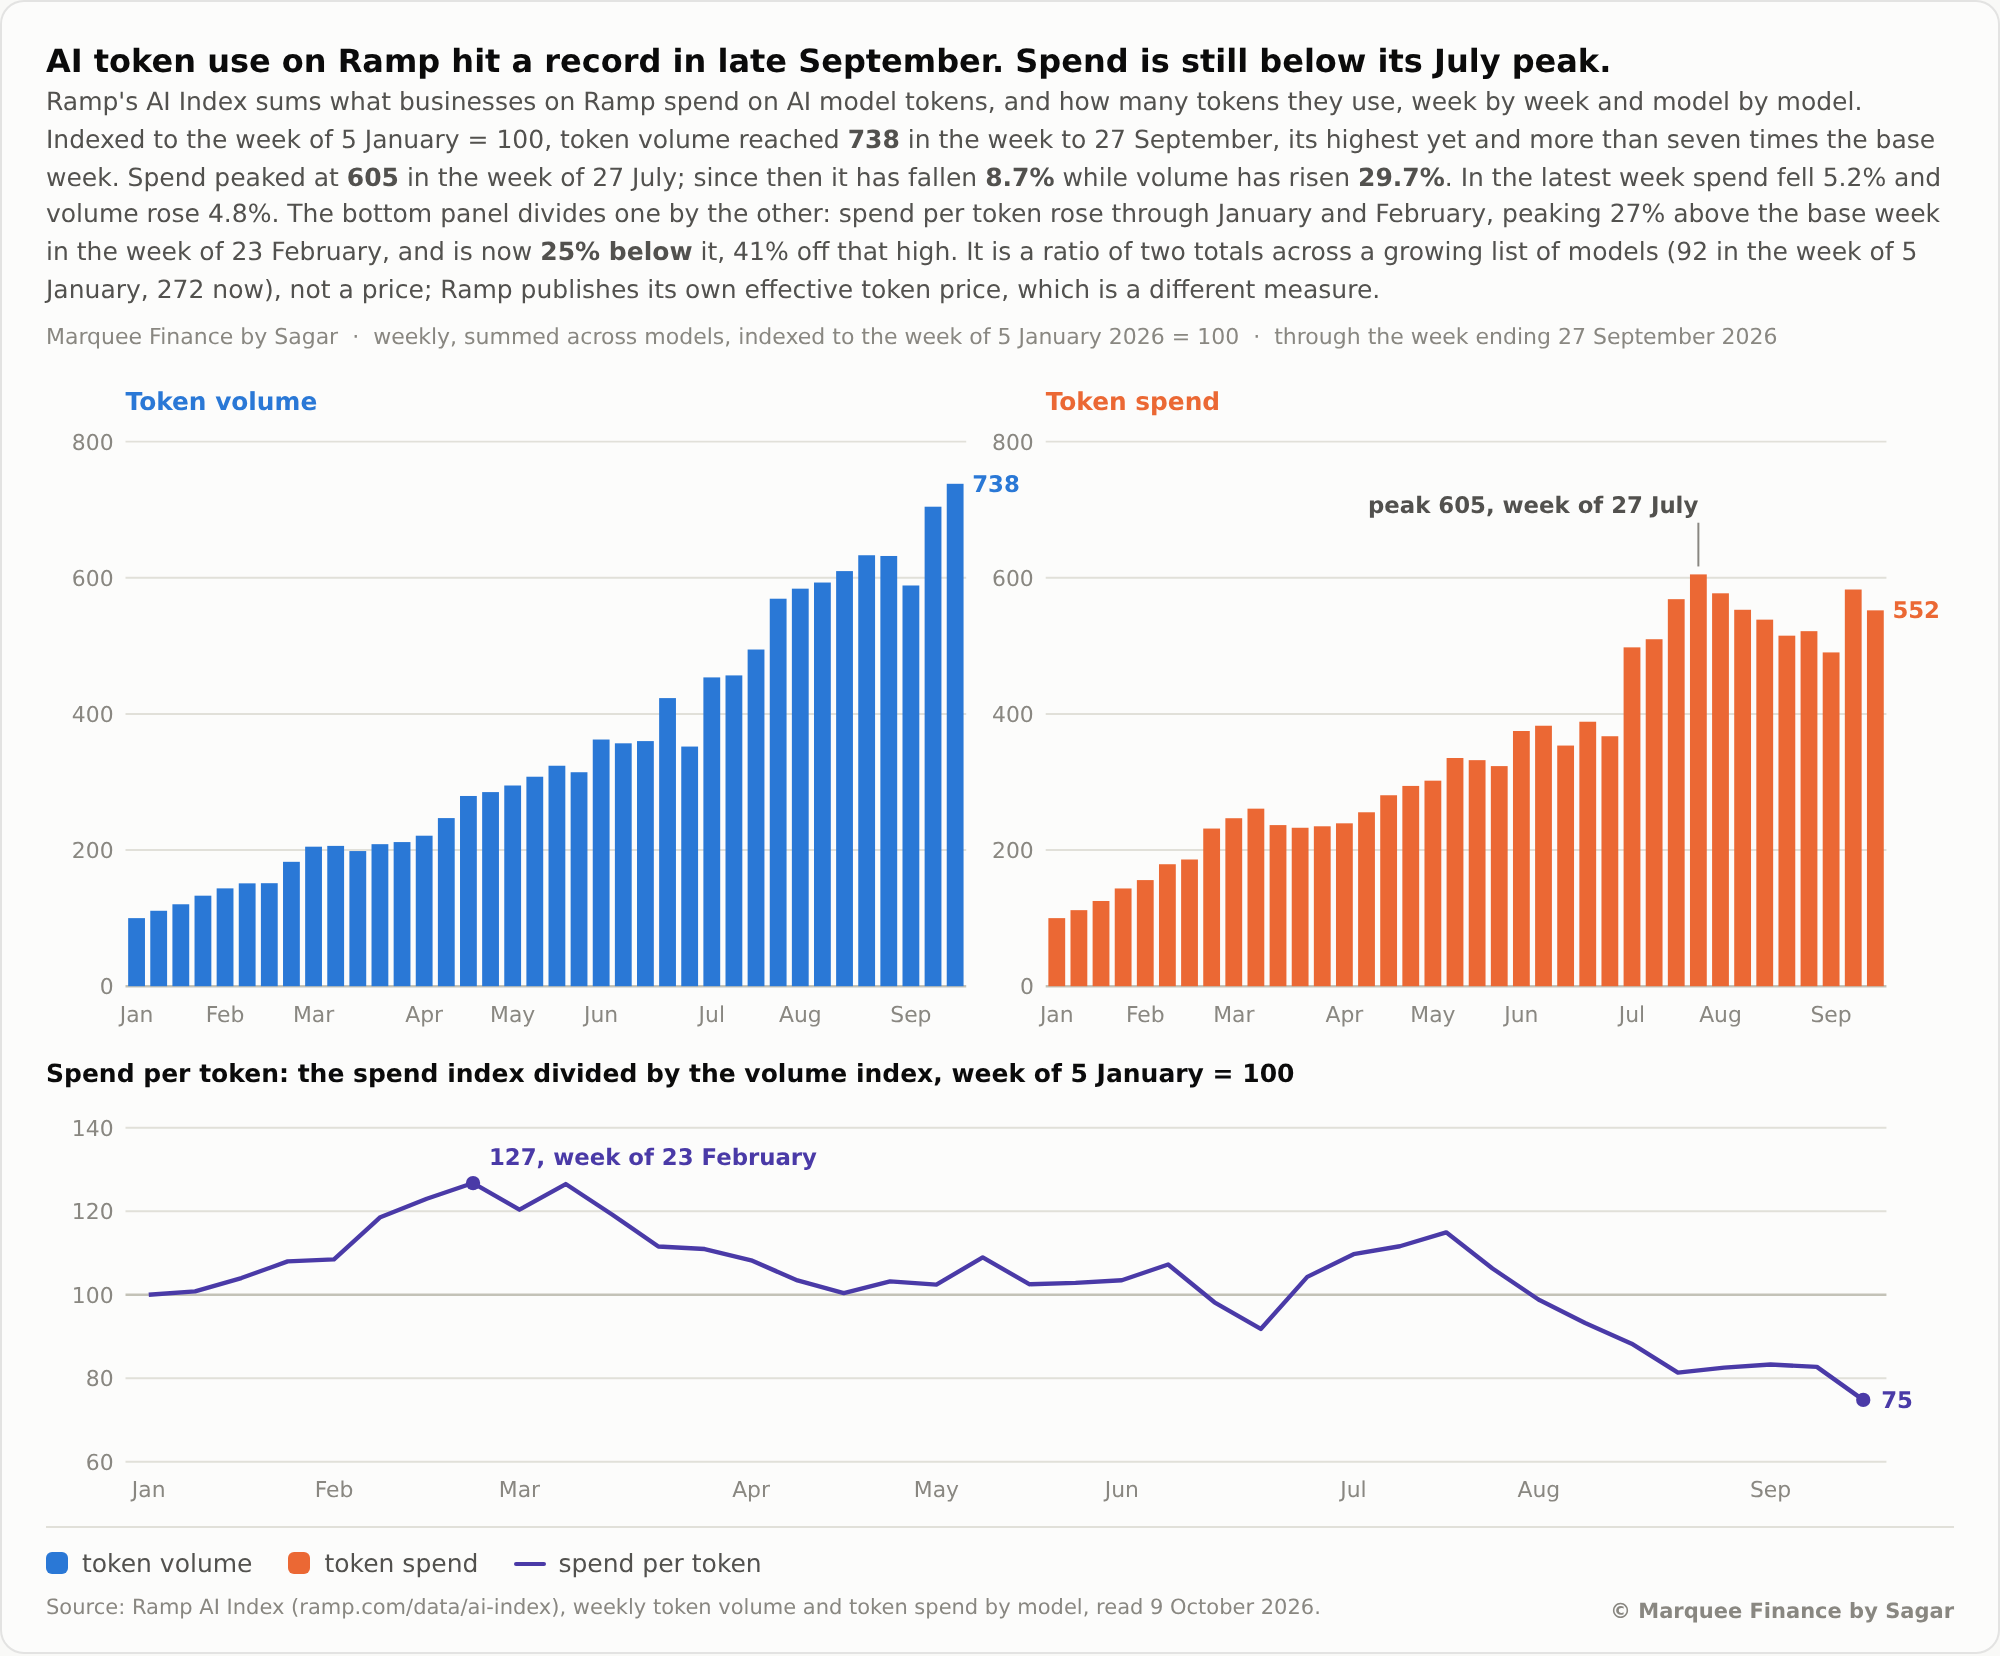
Notably, the spend per token is down 40% from the peak as token prices have crashed.
Furthermore, the credit market is in full-blown panic, with markets now pricing in a 20% probability of default for Oracle.
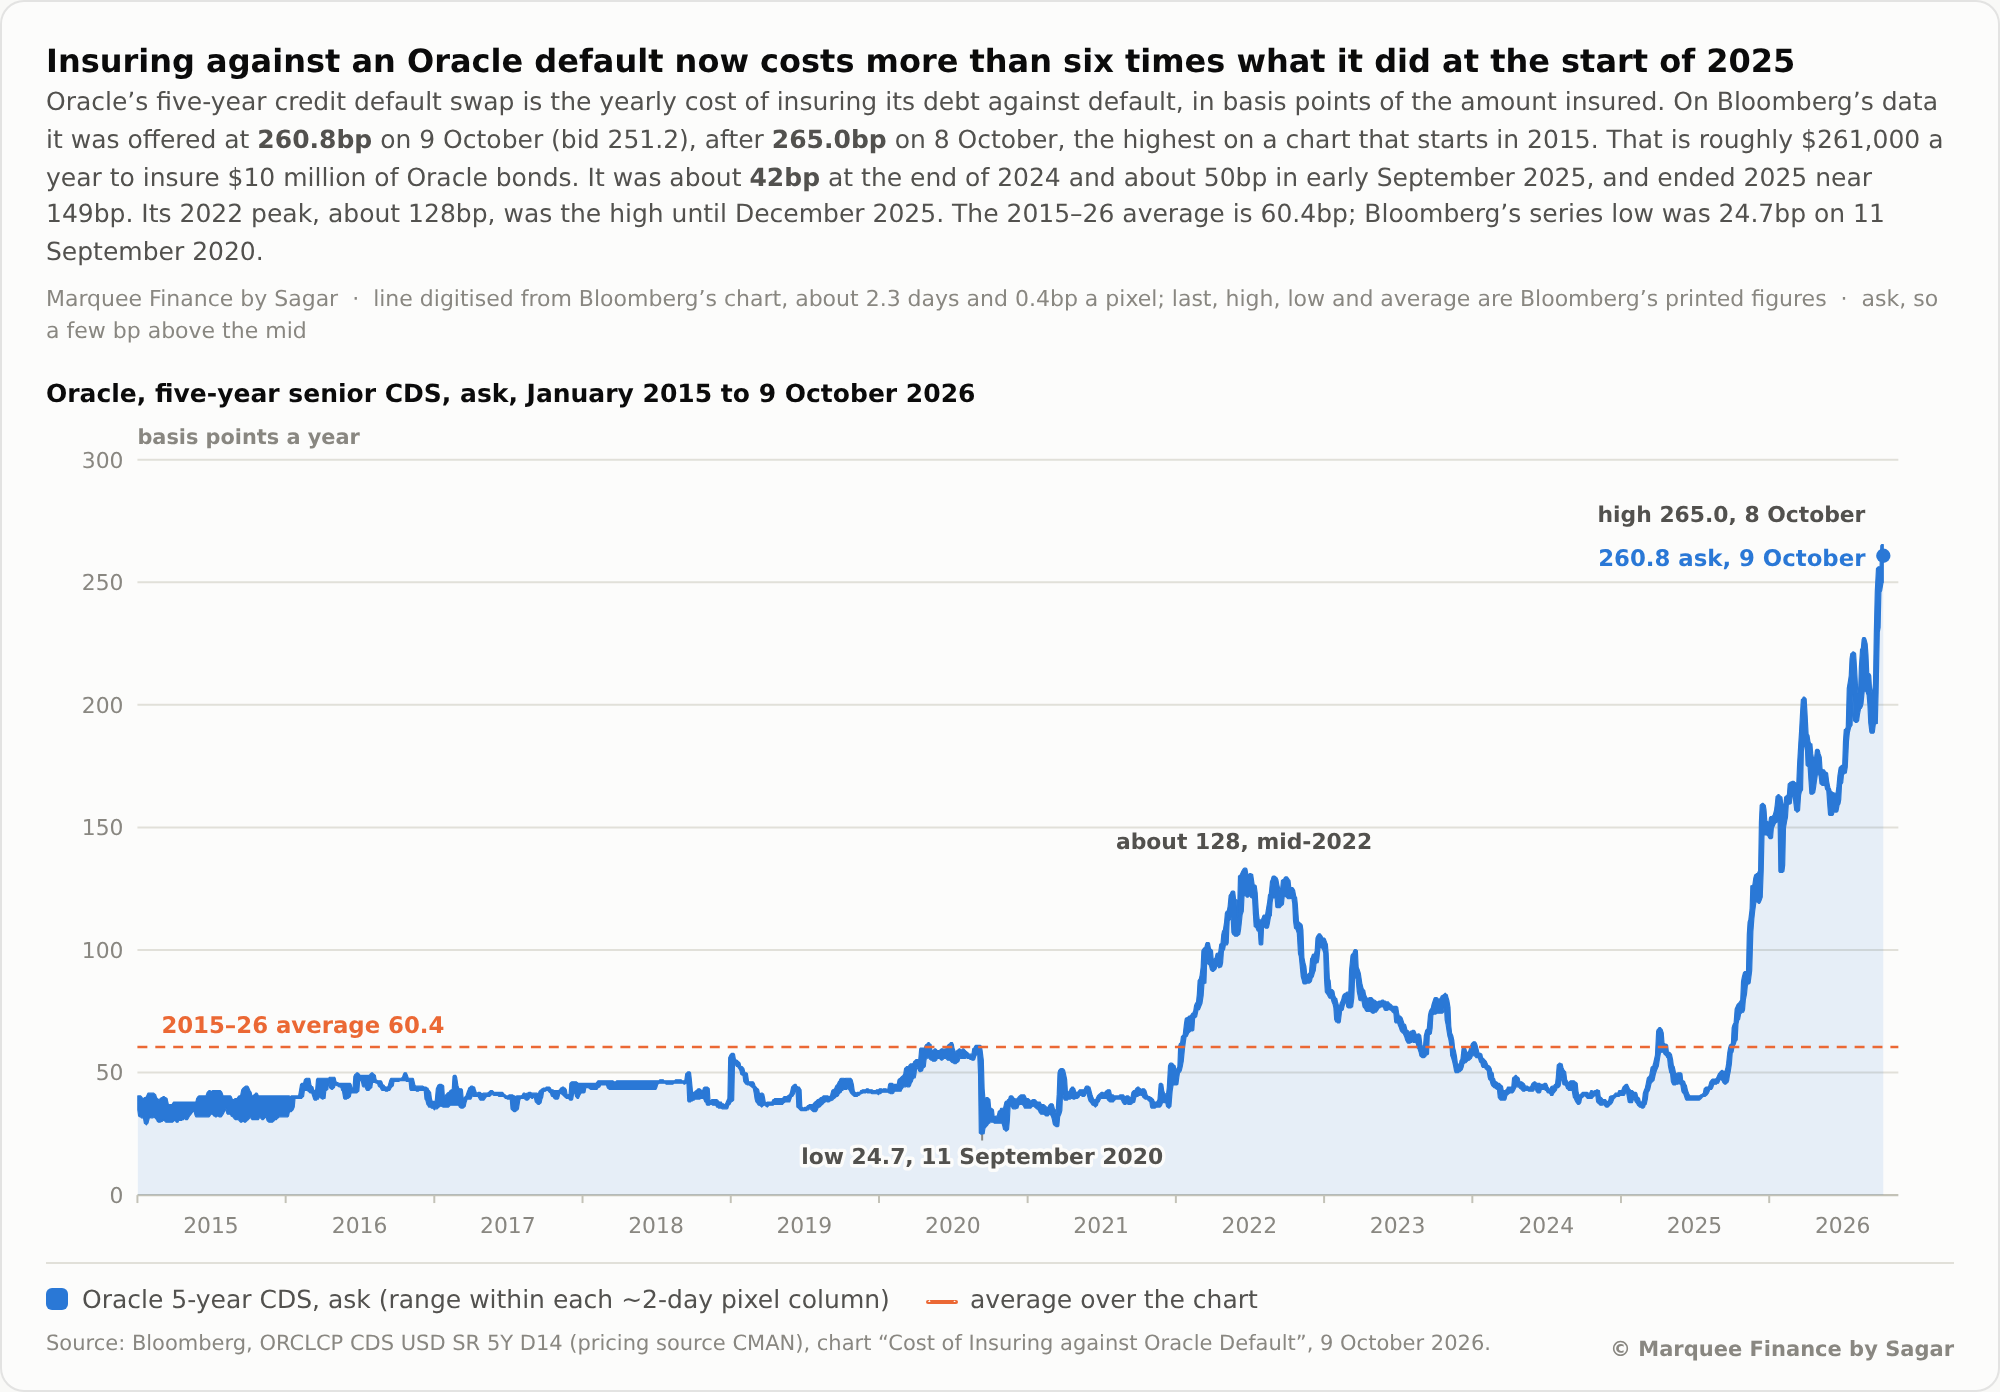
Oracle’s CDS has surged to a record high as market participants continue to hedge their equity exposure via CDS.
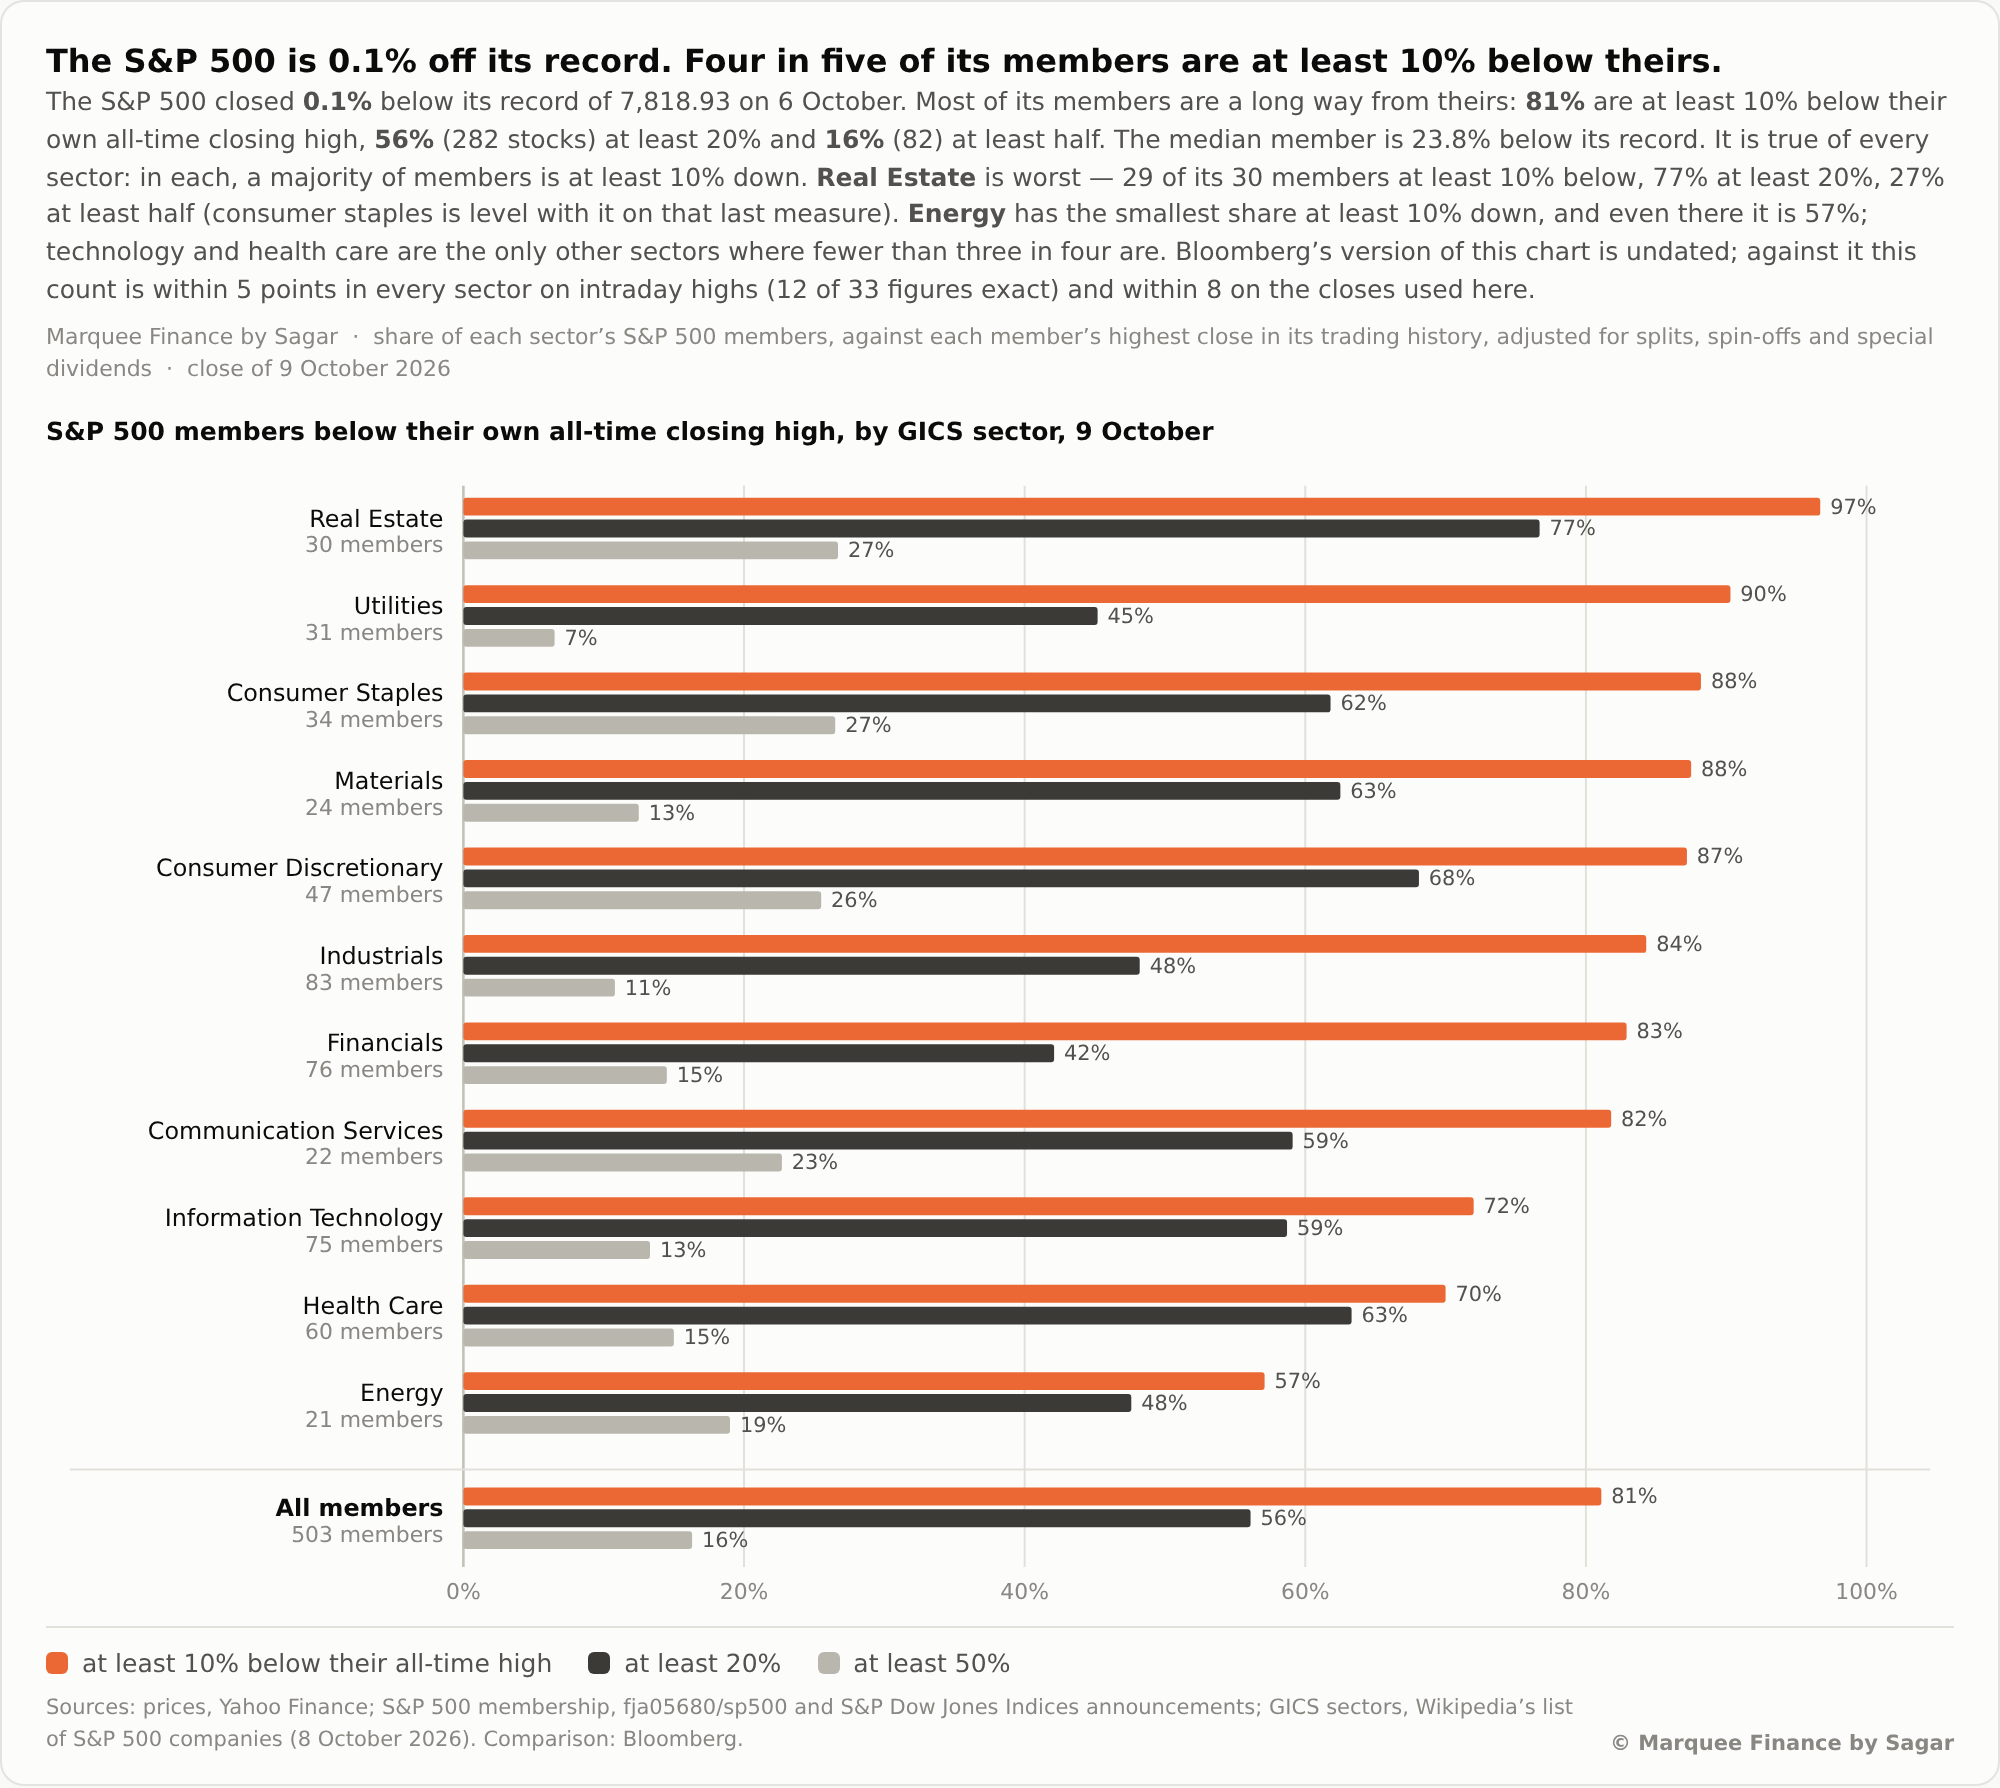
Meanwhile, in a mind-blowing stat, more than half of S&P 500 stocks are in a bear market, and 80% are 10% off their peak.
As tech problems abound and equity market internals weaken, freight costs for transporting oil have reached unprecedented levels.
The tanker crisis has rattled energy markets, and no end is in sight; there is no magic wand to solve it.
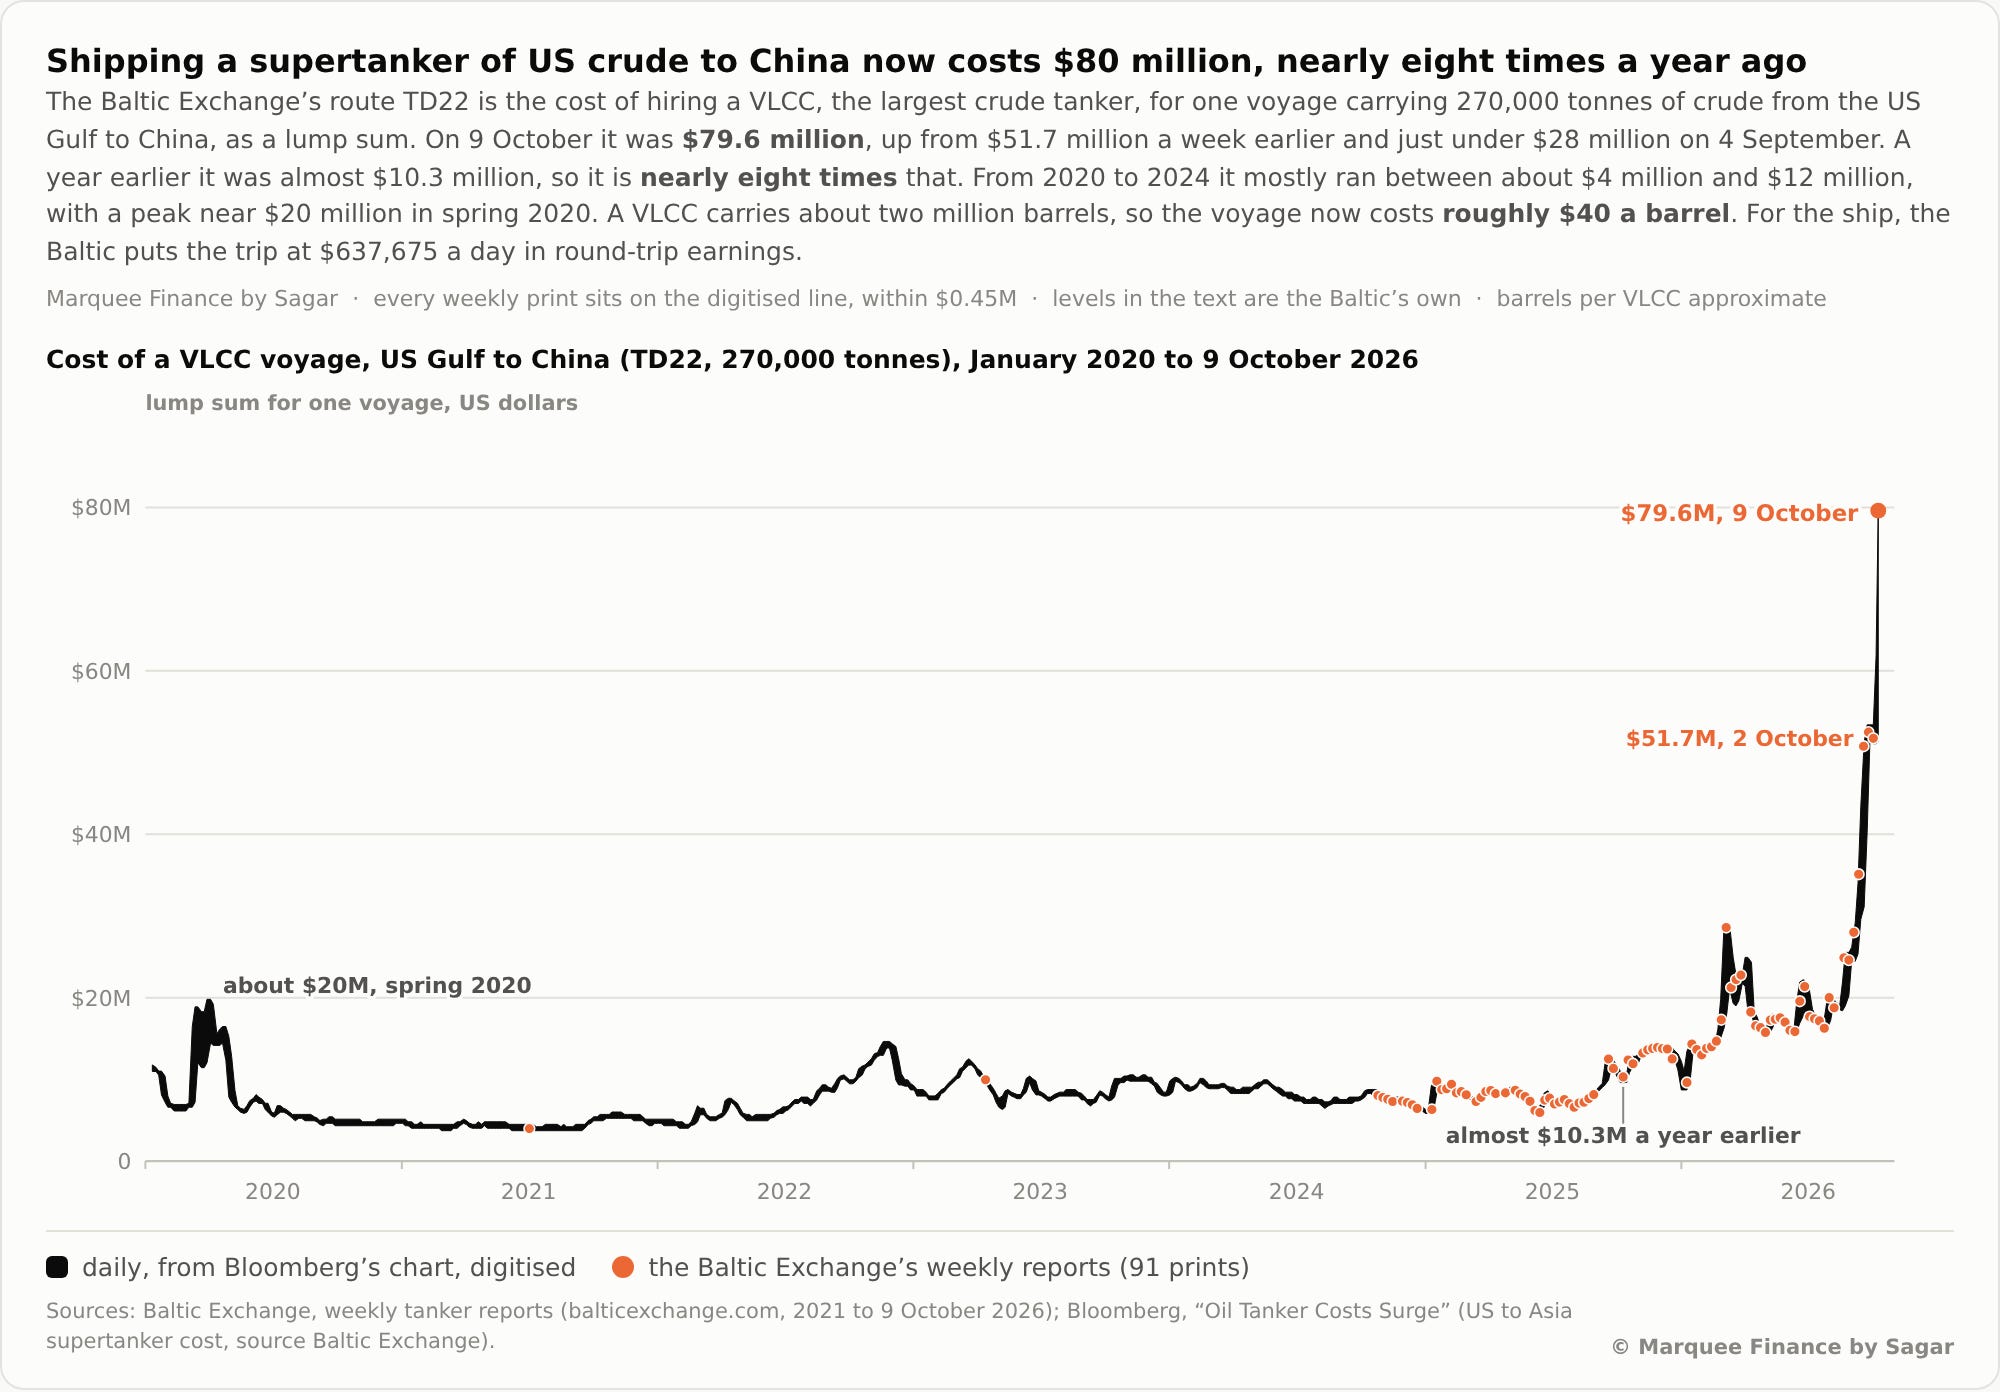
We may be on the verge of an energy crisis similar to the 70s, and the geopolitical deadlock needs to end immediately, or the supply-chain rupture will take months to heal.
October is turning out much better than September, and we are hopeful for a great end to the year.

Let us take a deep dive into the macro universe and comprehend the cross-asset moves.
US/Equities/Bonds/Gold/Silver/Oil/Dollar!
Before we begin analysing the macro data, we want to look at the upcoming mid-term elections.
We believe Republicans are likely to lose, given Trump's record-low approval rating.
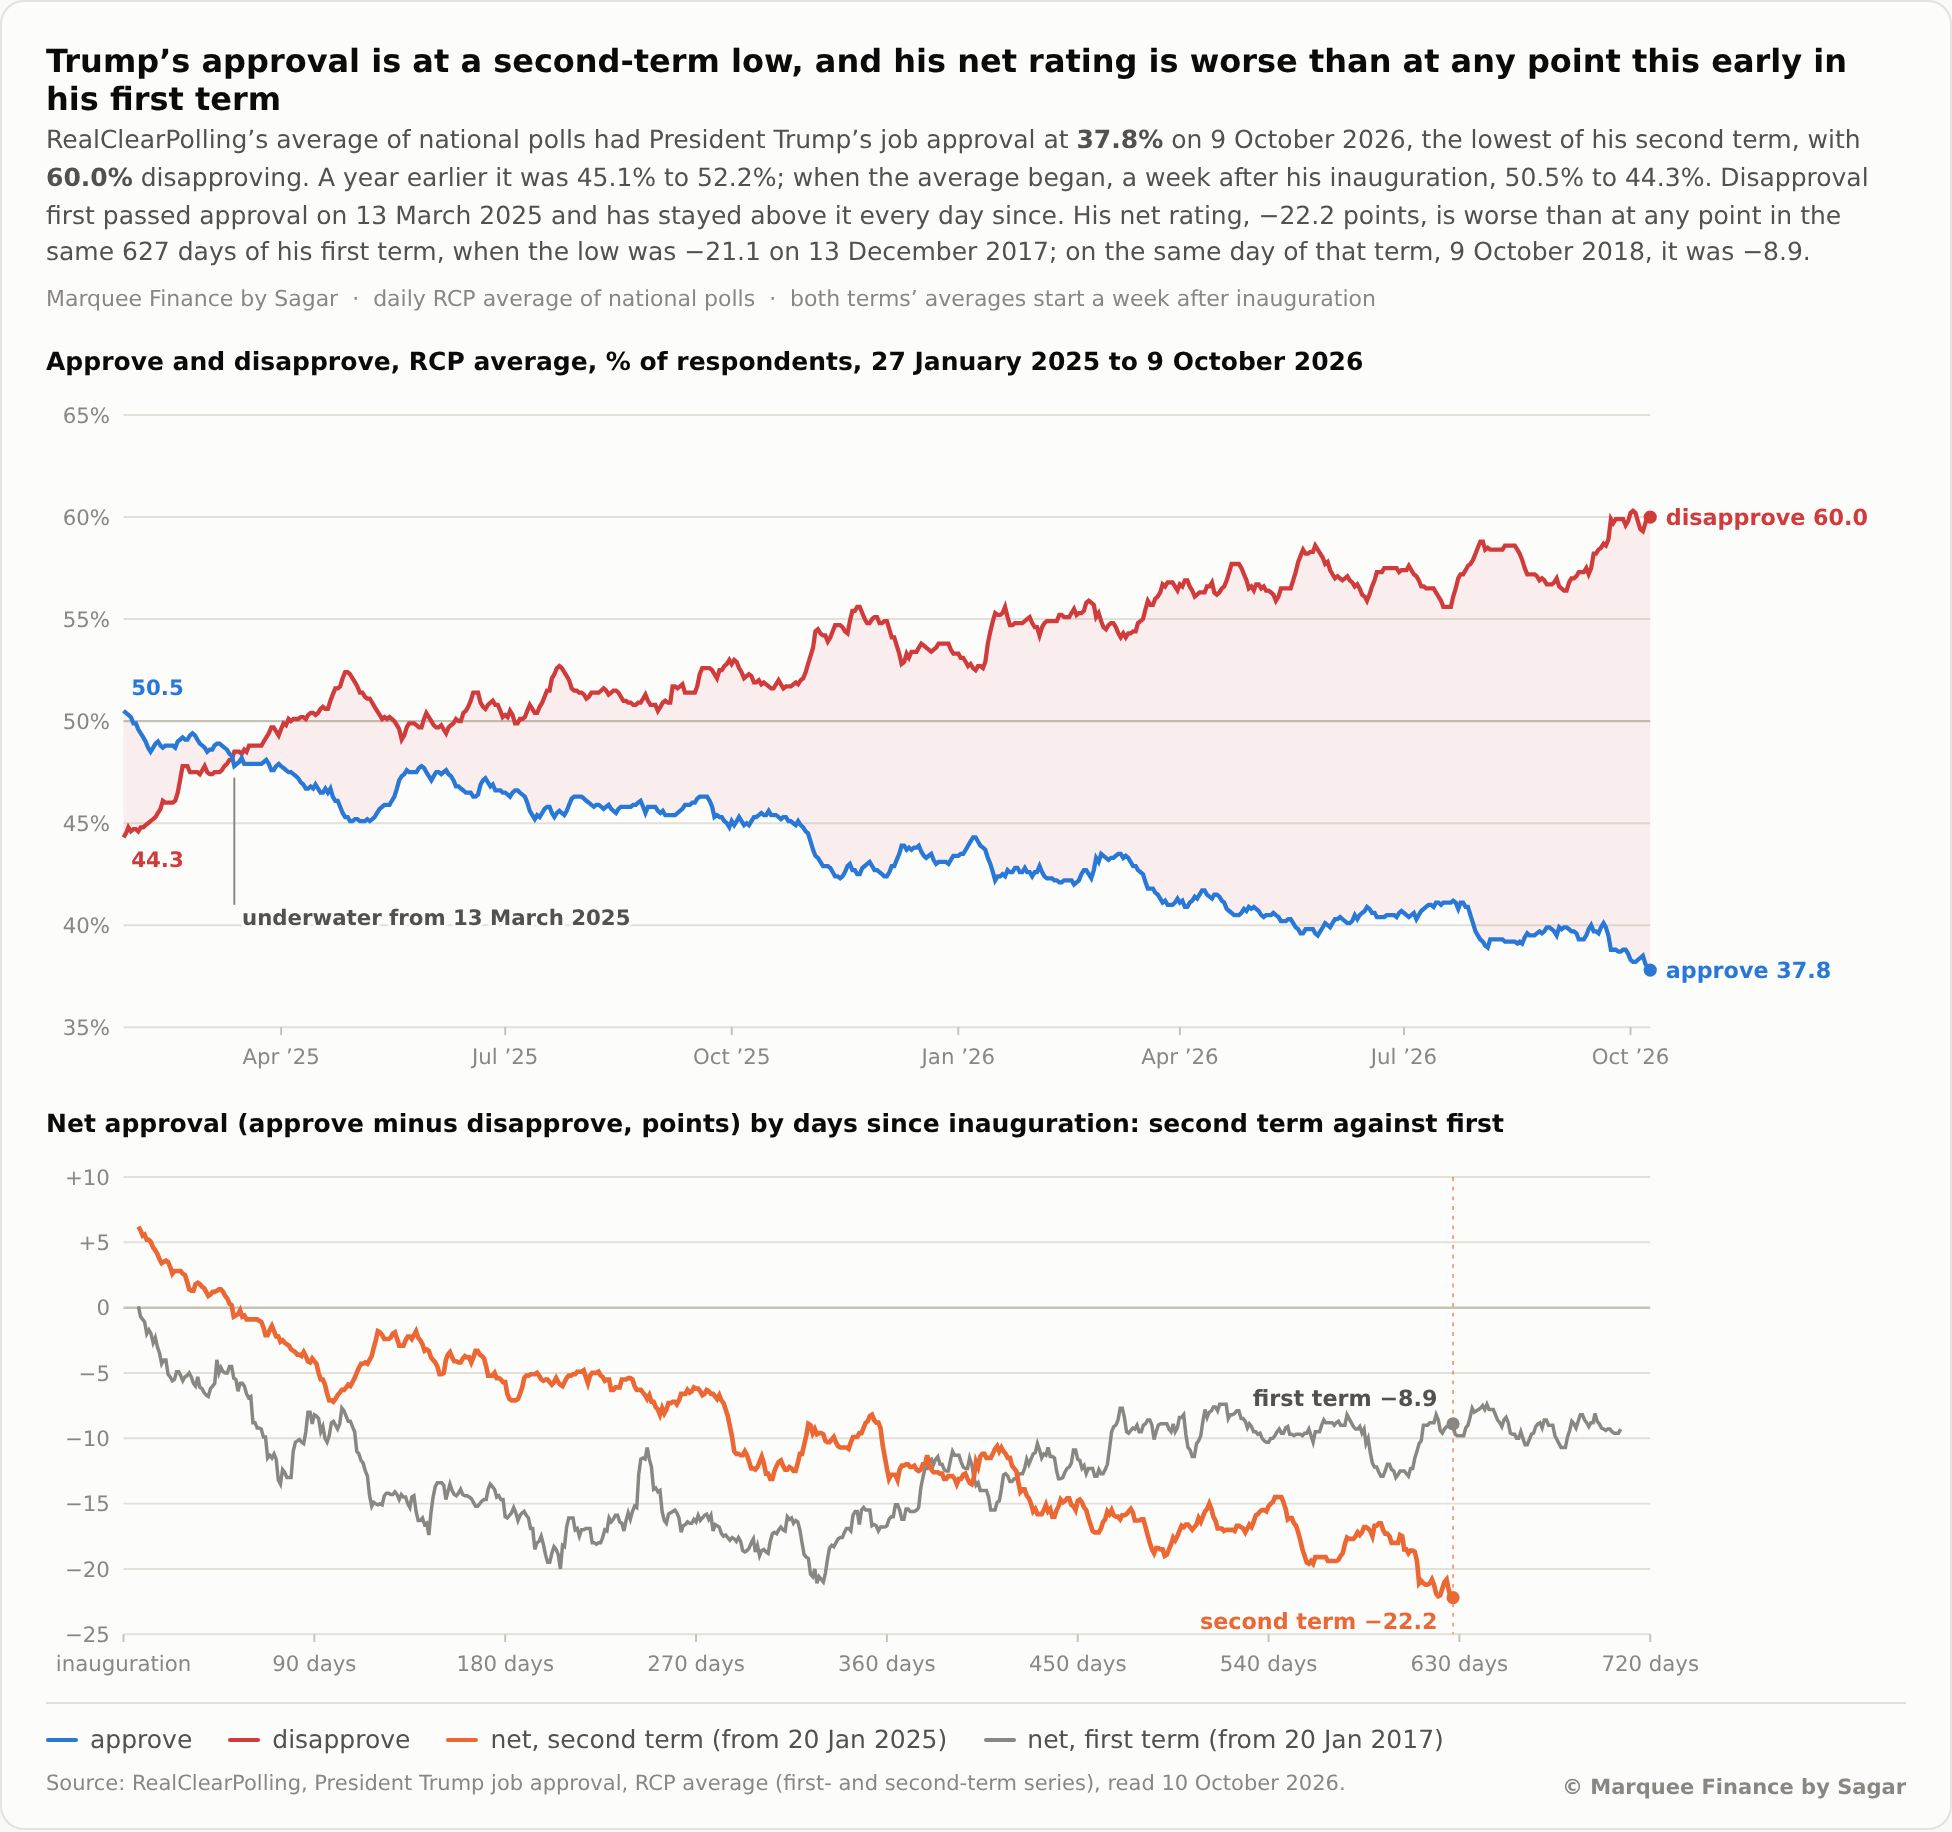
We don’t expect anything to change overnight, and with only 3 weeks to the election, an ATH stock market won't save the Republicans.
ISM Services was the only major macro release we tracked closely this week.
ISM Services came in at 54.9, a tad lower than expectations at 55.
Respondent comments suggest that while demand is resilient, pricing pressures are widespread across industries.
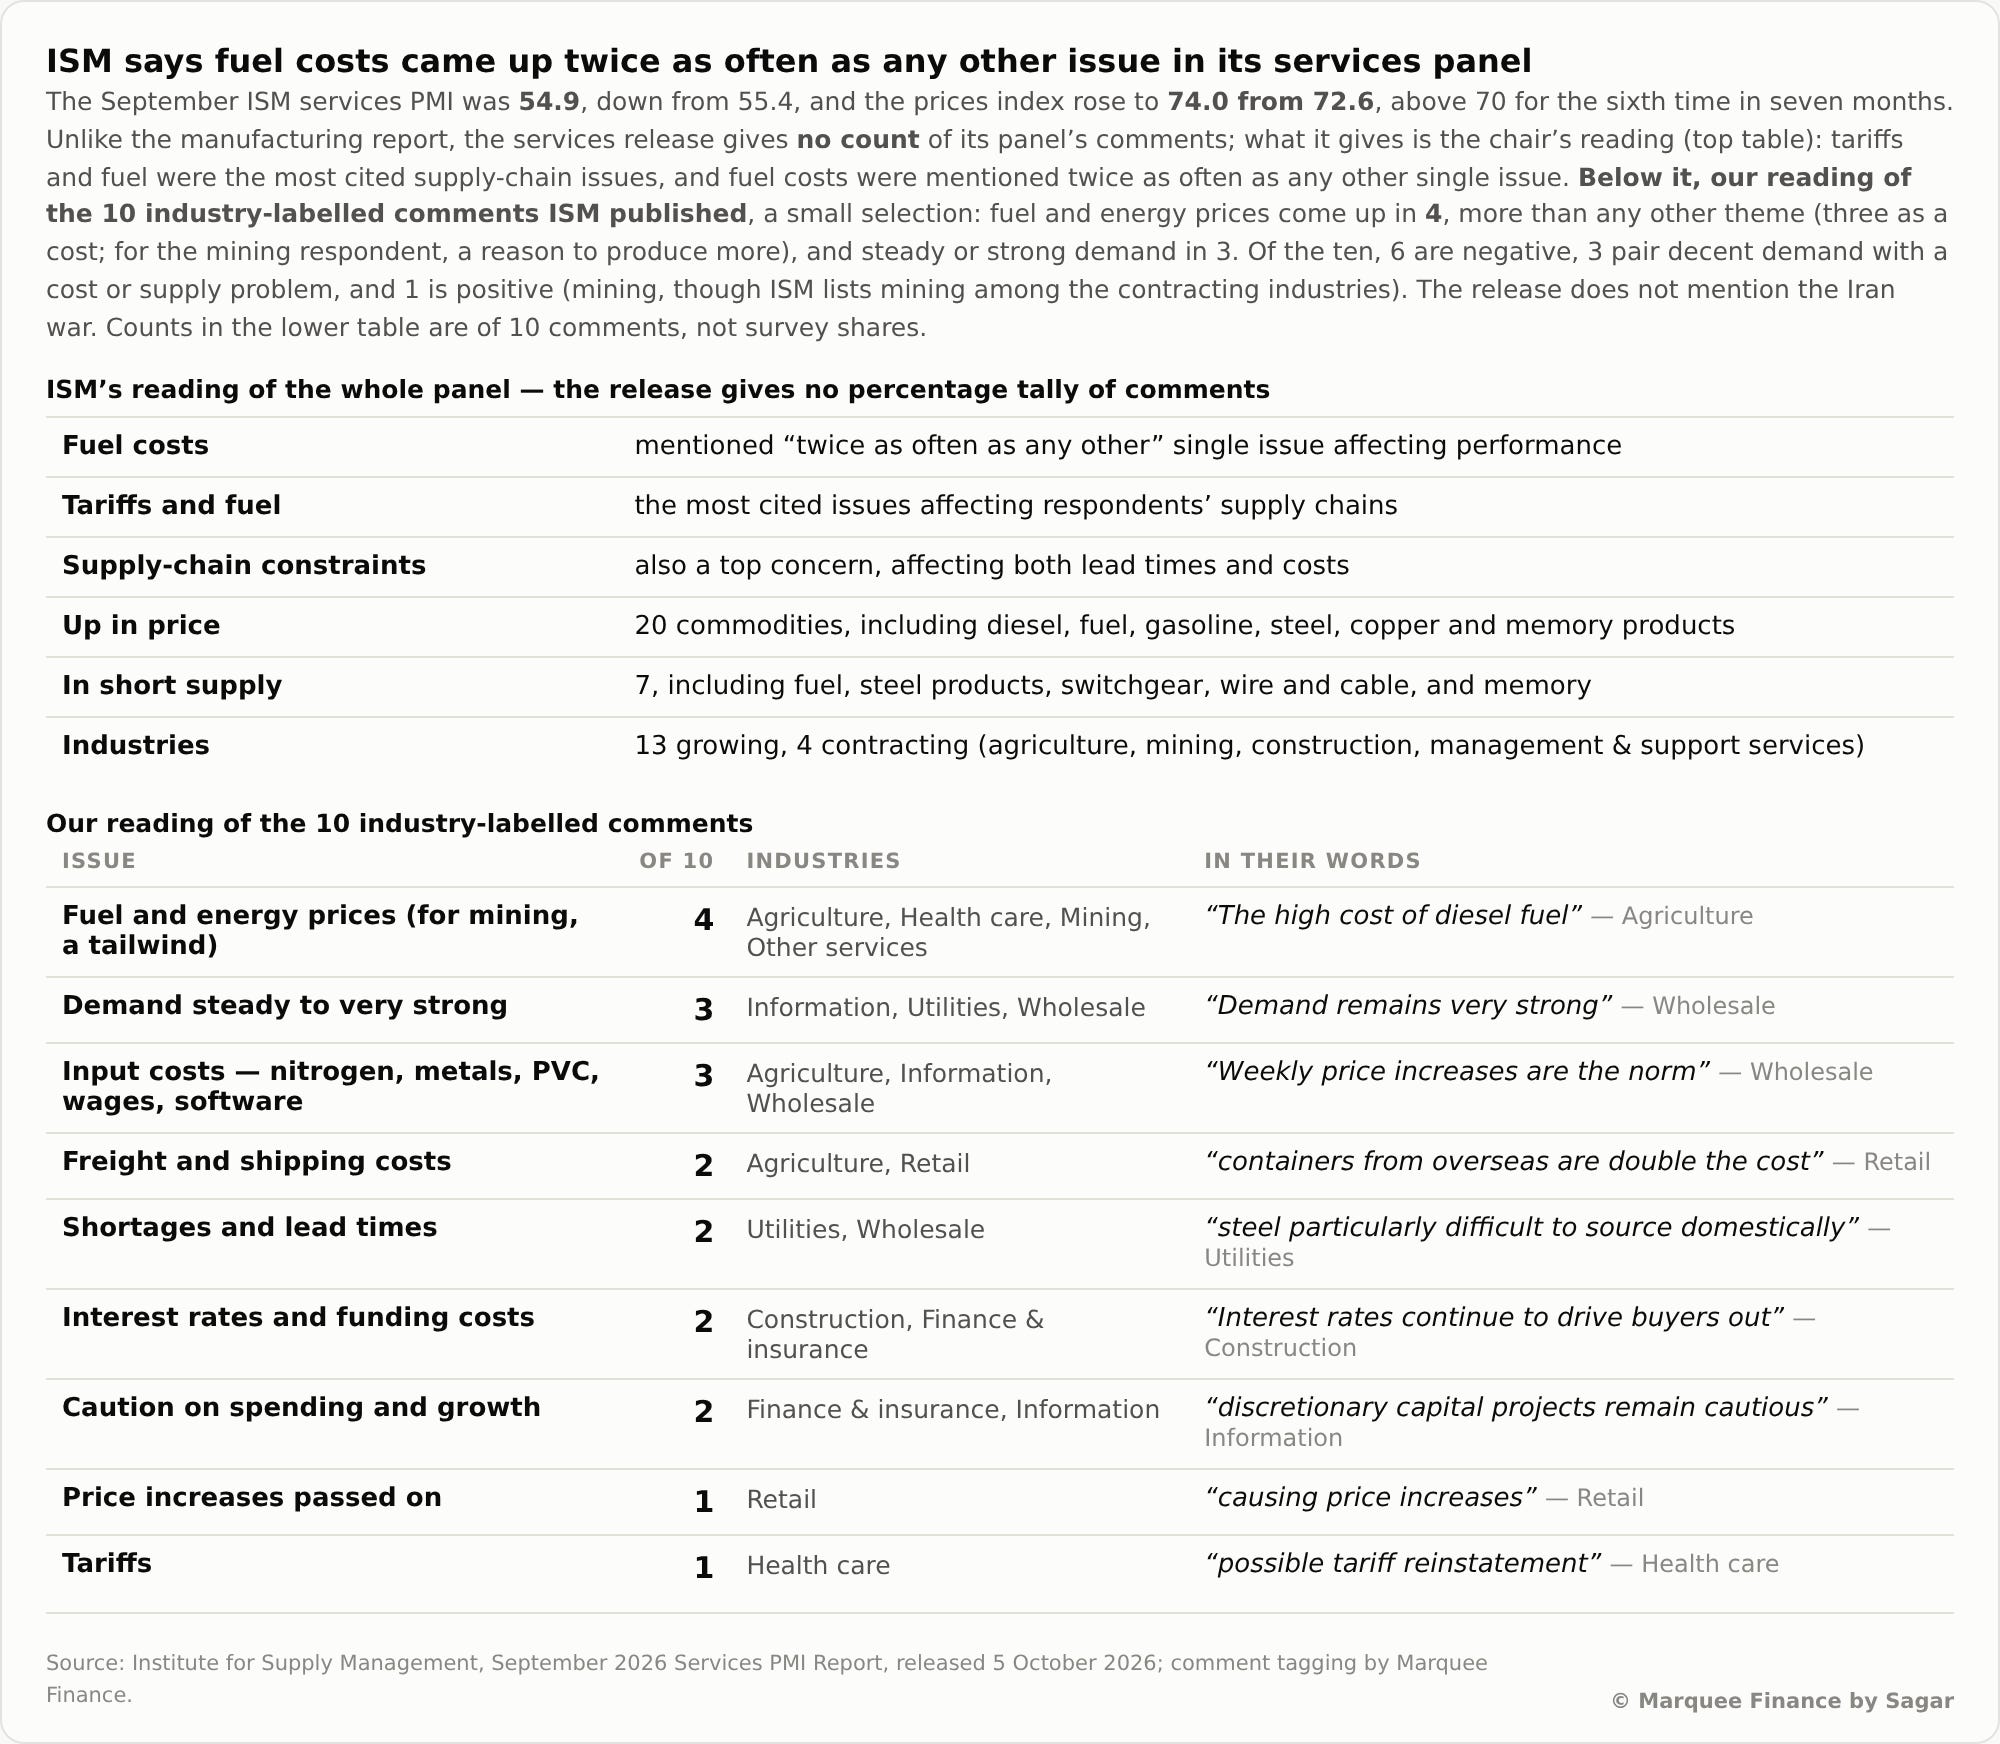
Tariffs are still hurting, while higher fuel costs, especially diesel, are now creating havoc on industries.
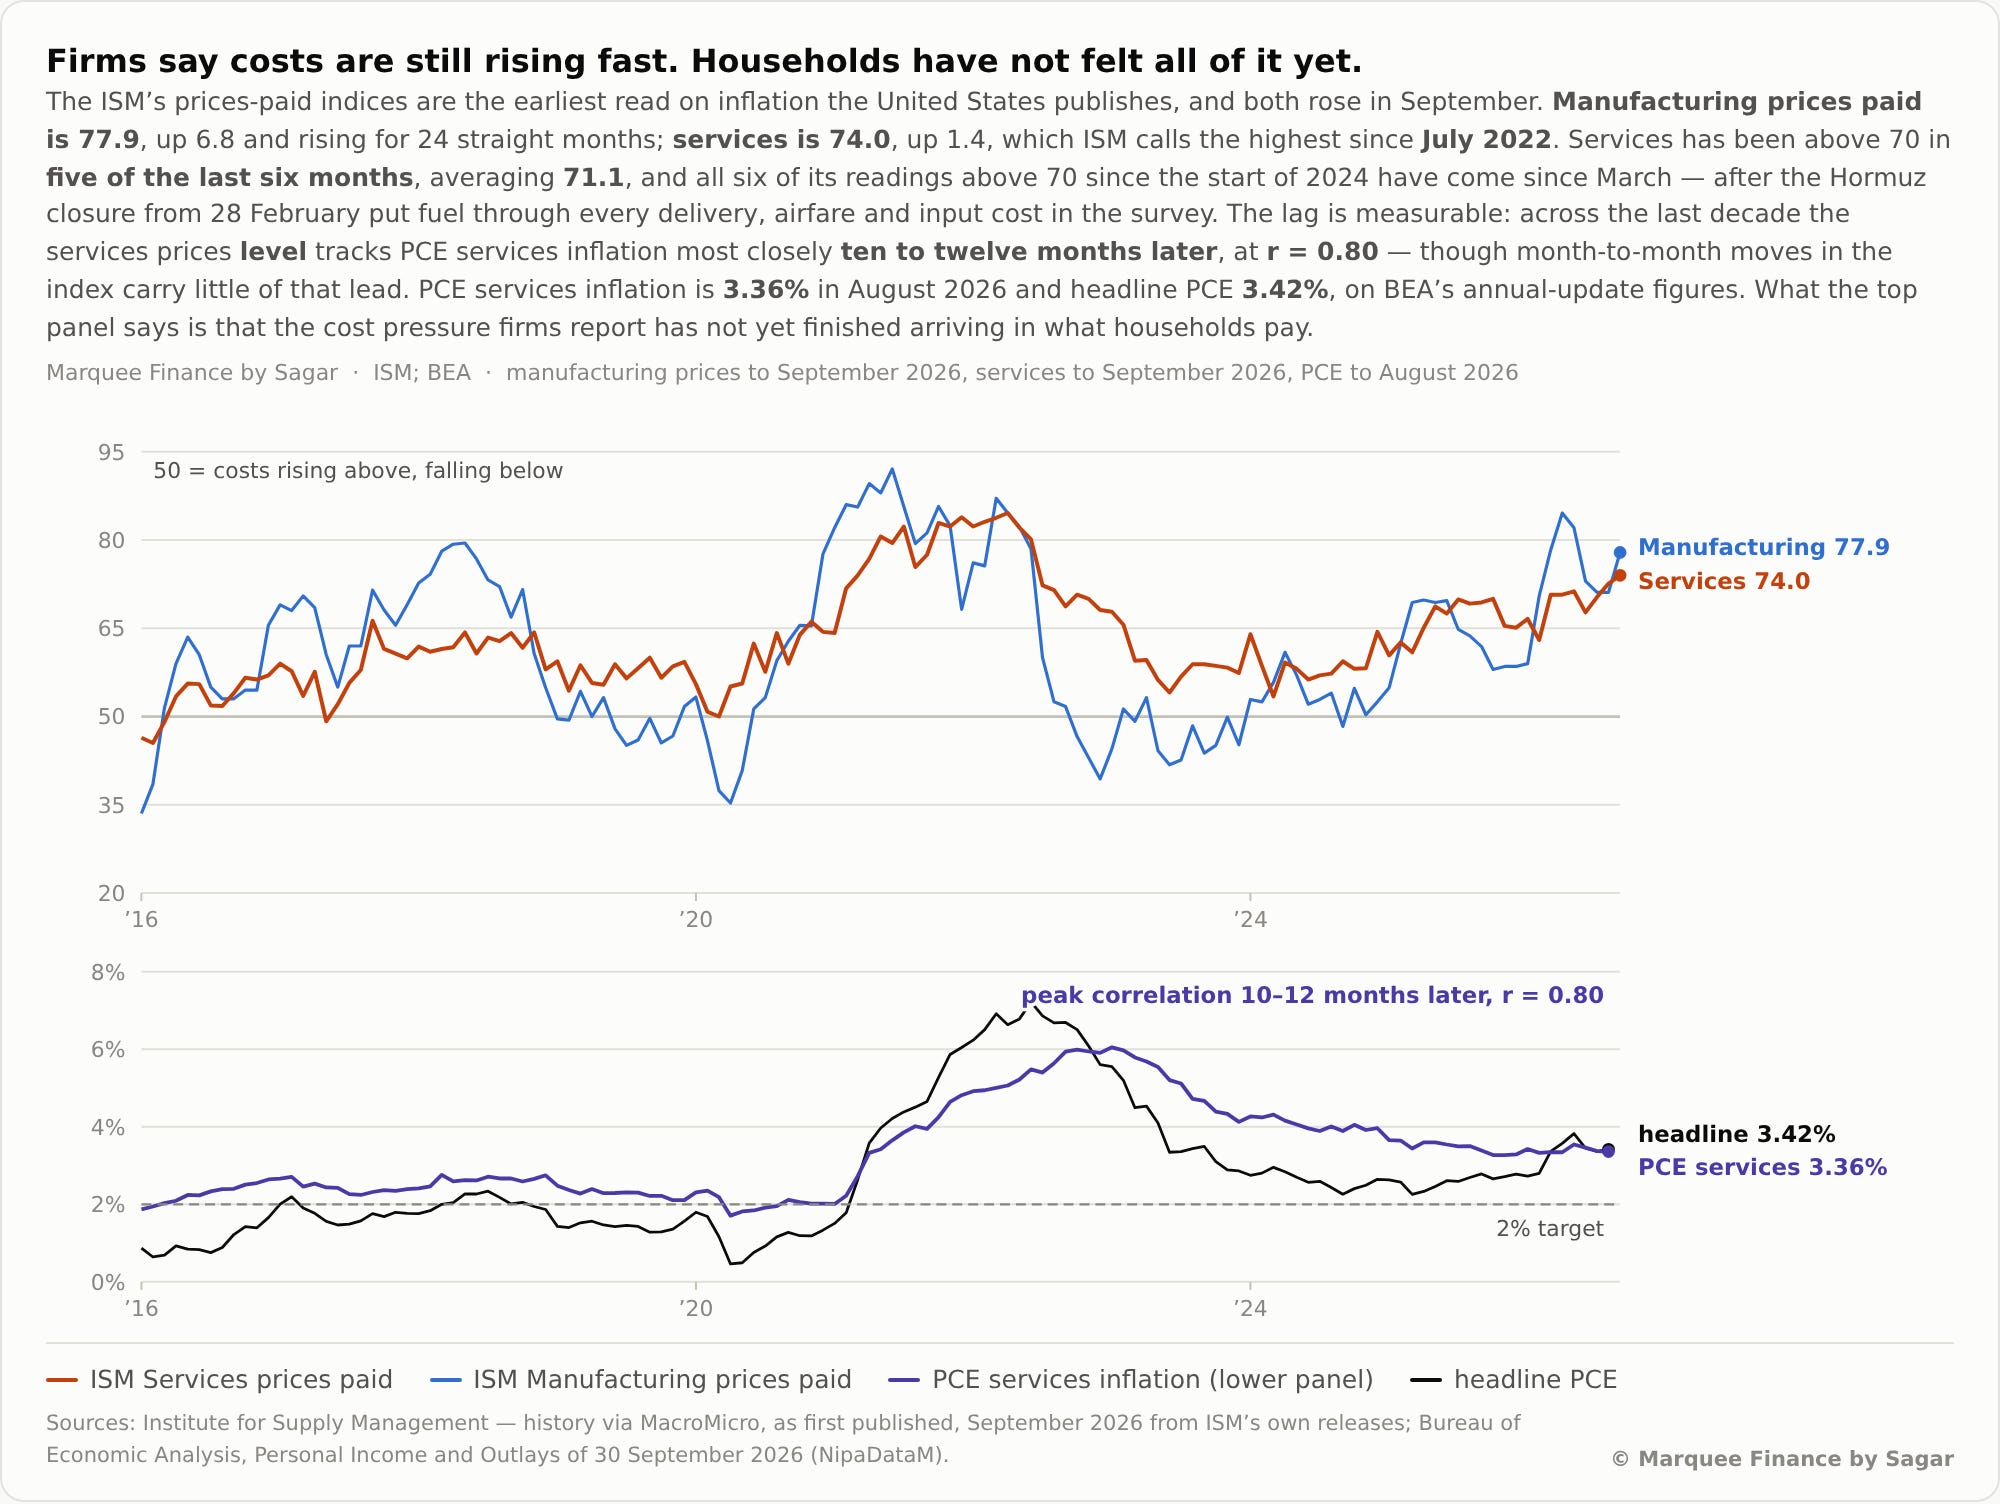
ISM Services Prices surged to 74, and given its tight correlation with inflation, CPI/PCE is likely to rise in the coming months.
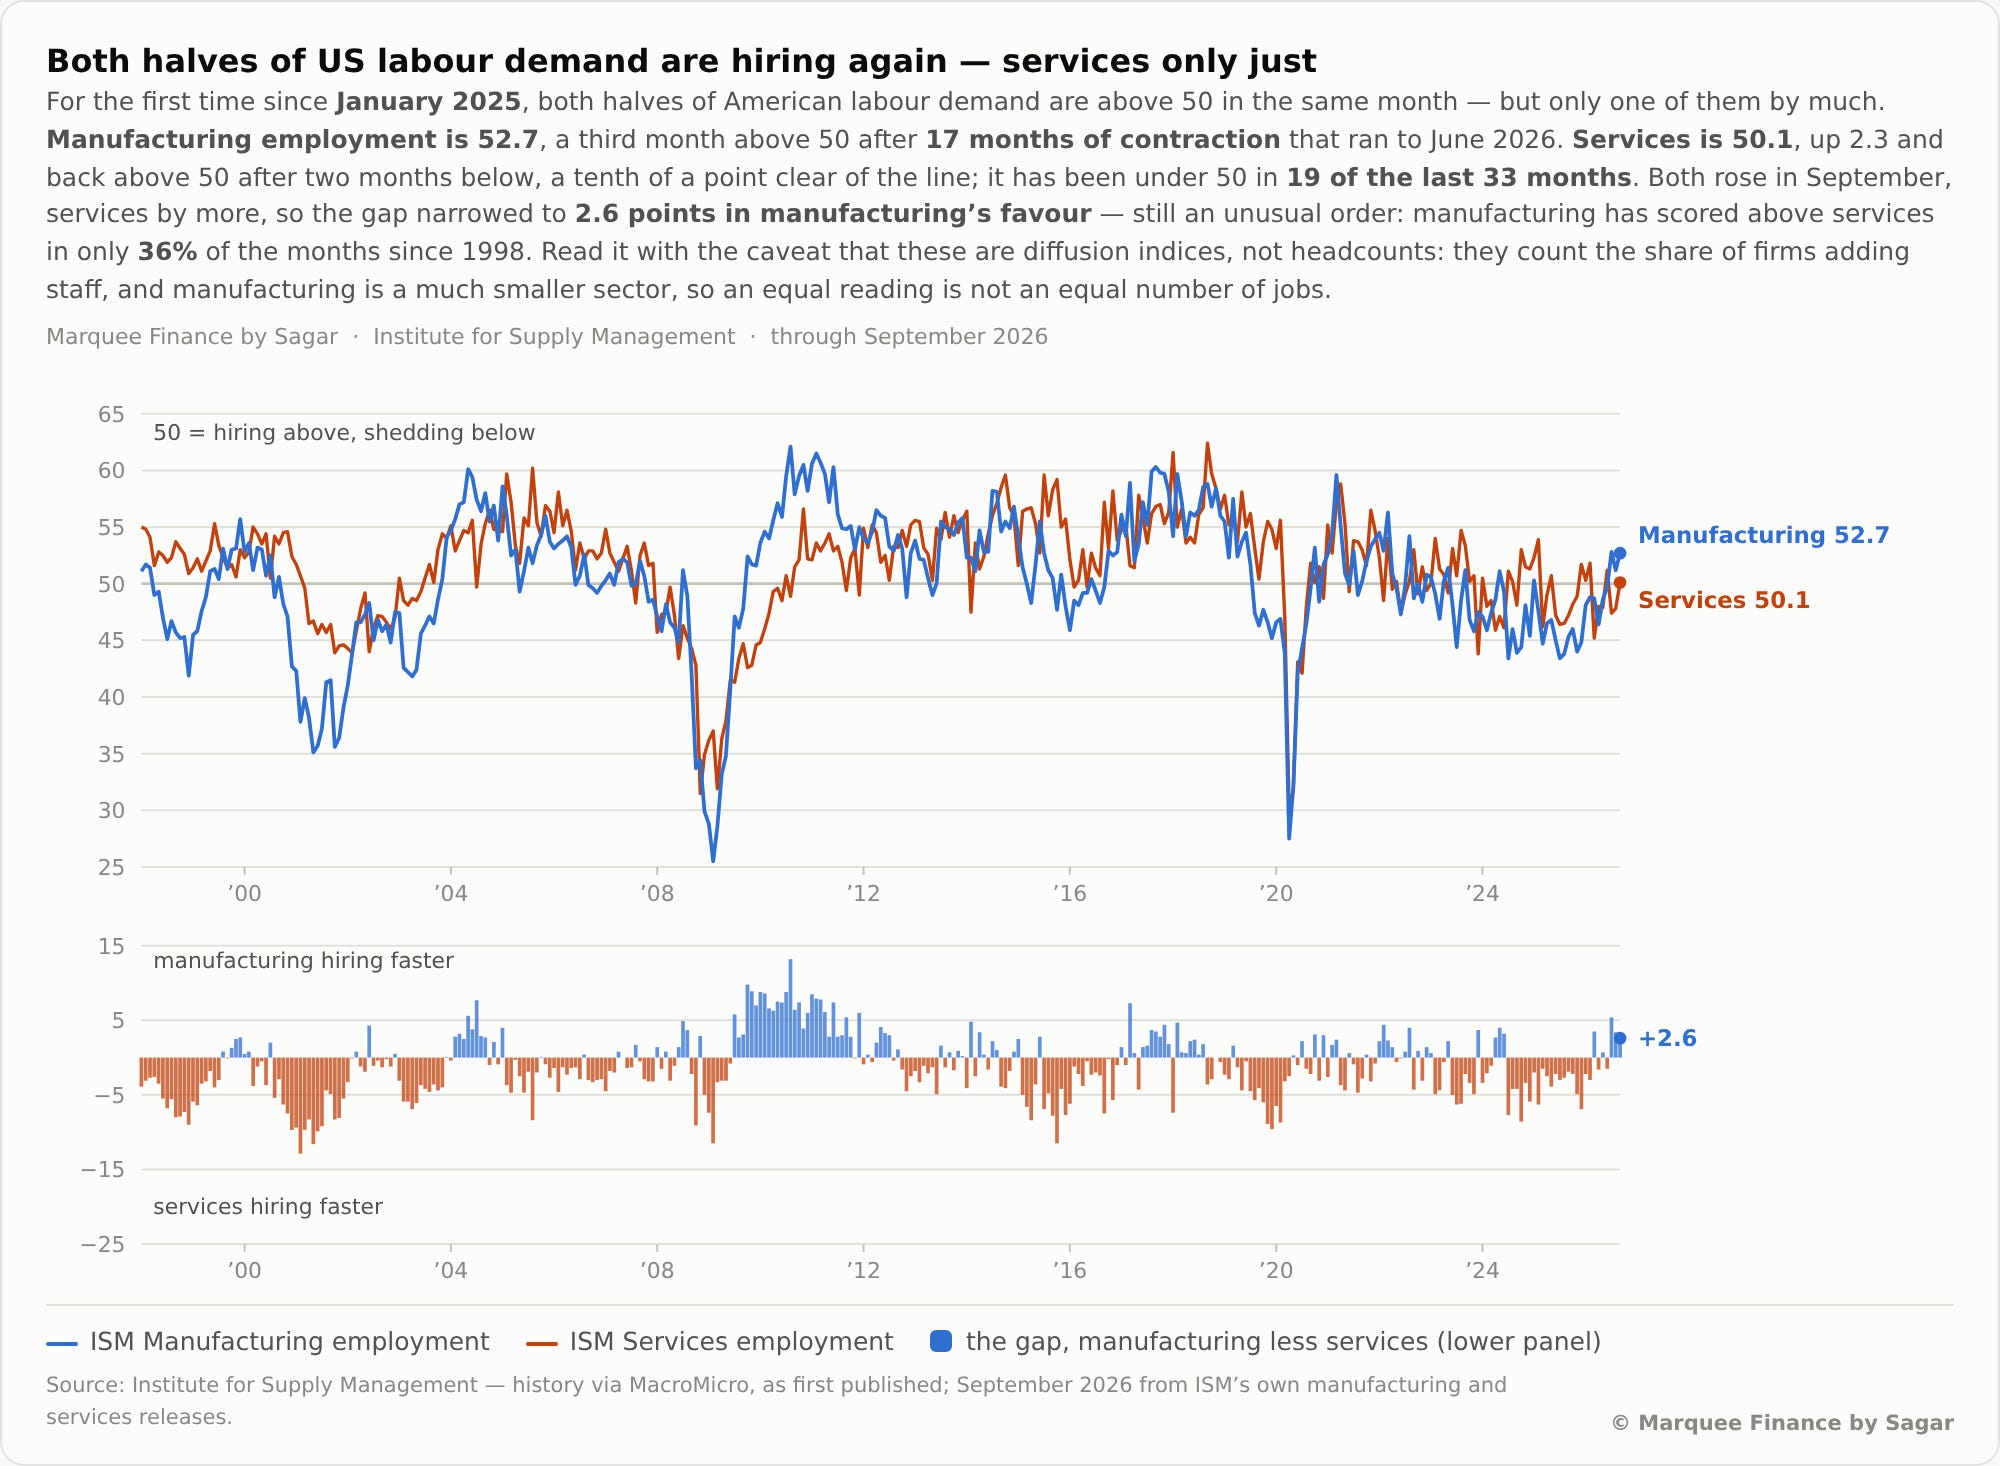
While last week ISM Manufacturing employment indicated a turnaround in the employment situation (due to the AI rollout), this week the Services Employment PMI also moved into expansionary territory, suggesting the labour market is not a concern.
Overall, the US economy remains resilient, but higher prices and rates might create issues in the coming months.
Equities!
A deeper look at market breadth shows some respite, likely as yields cooled a bit from the top.
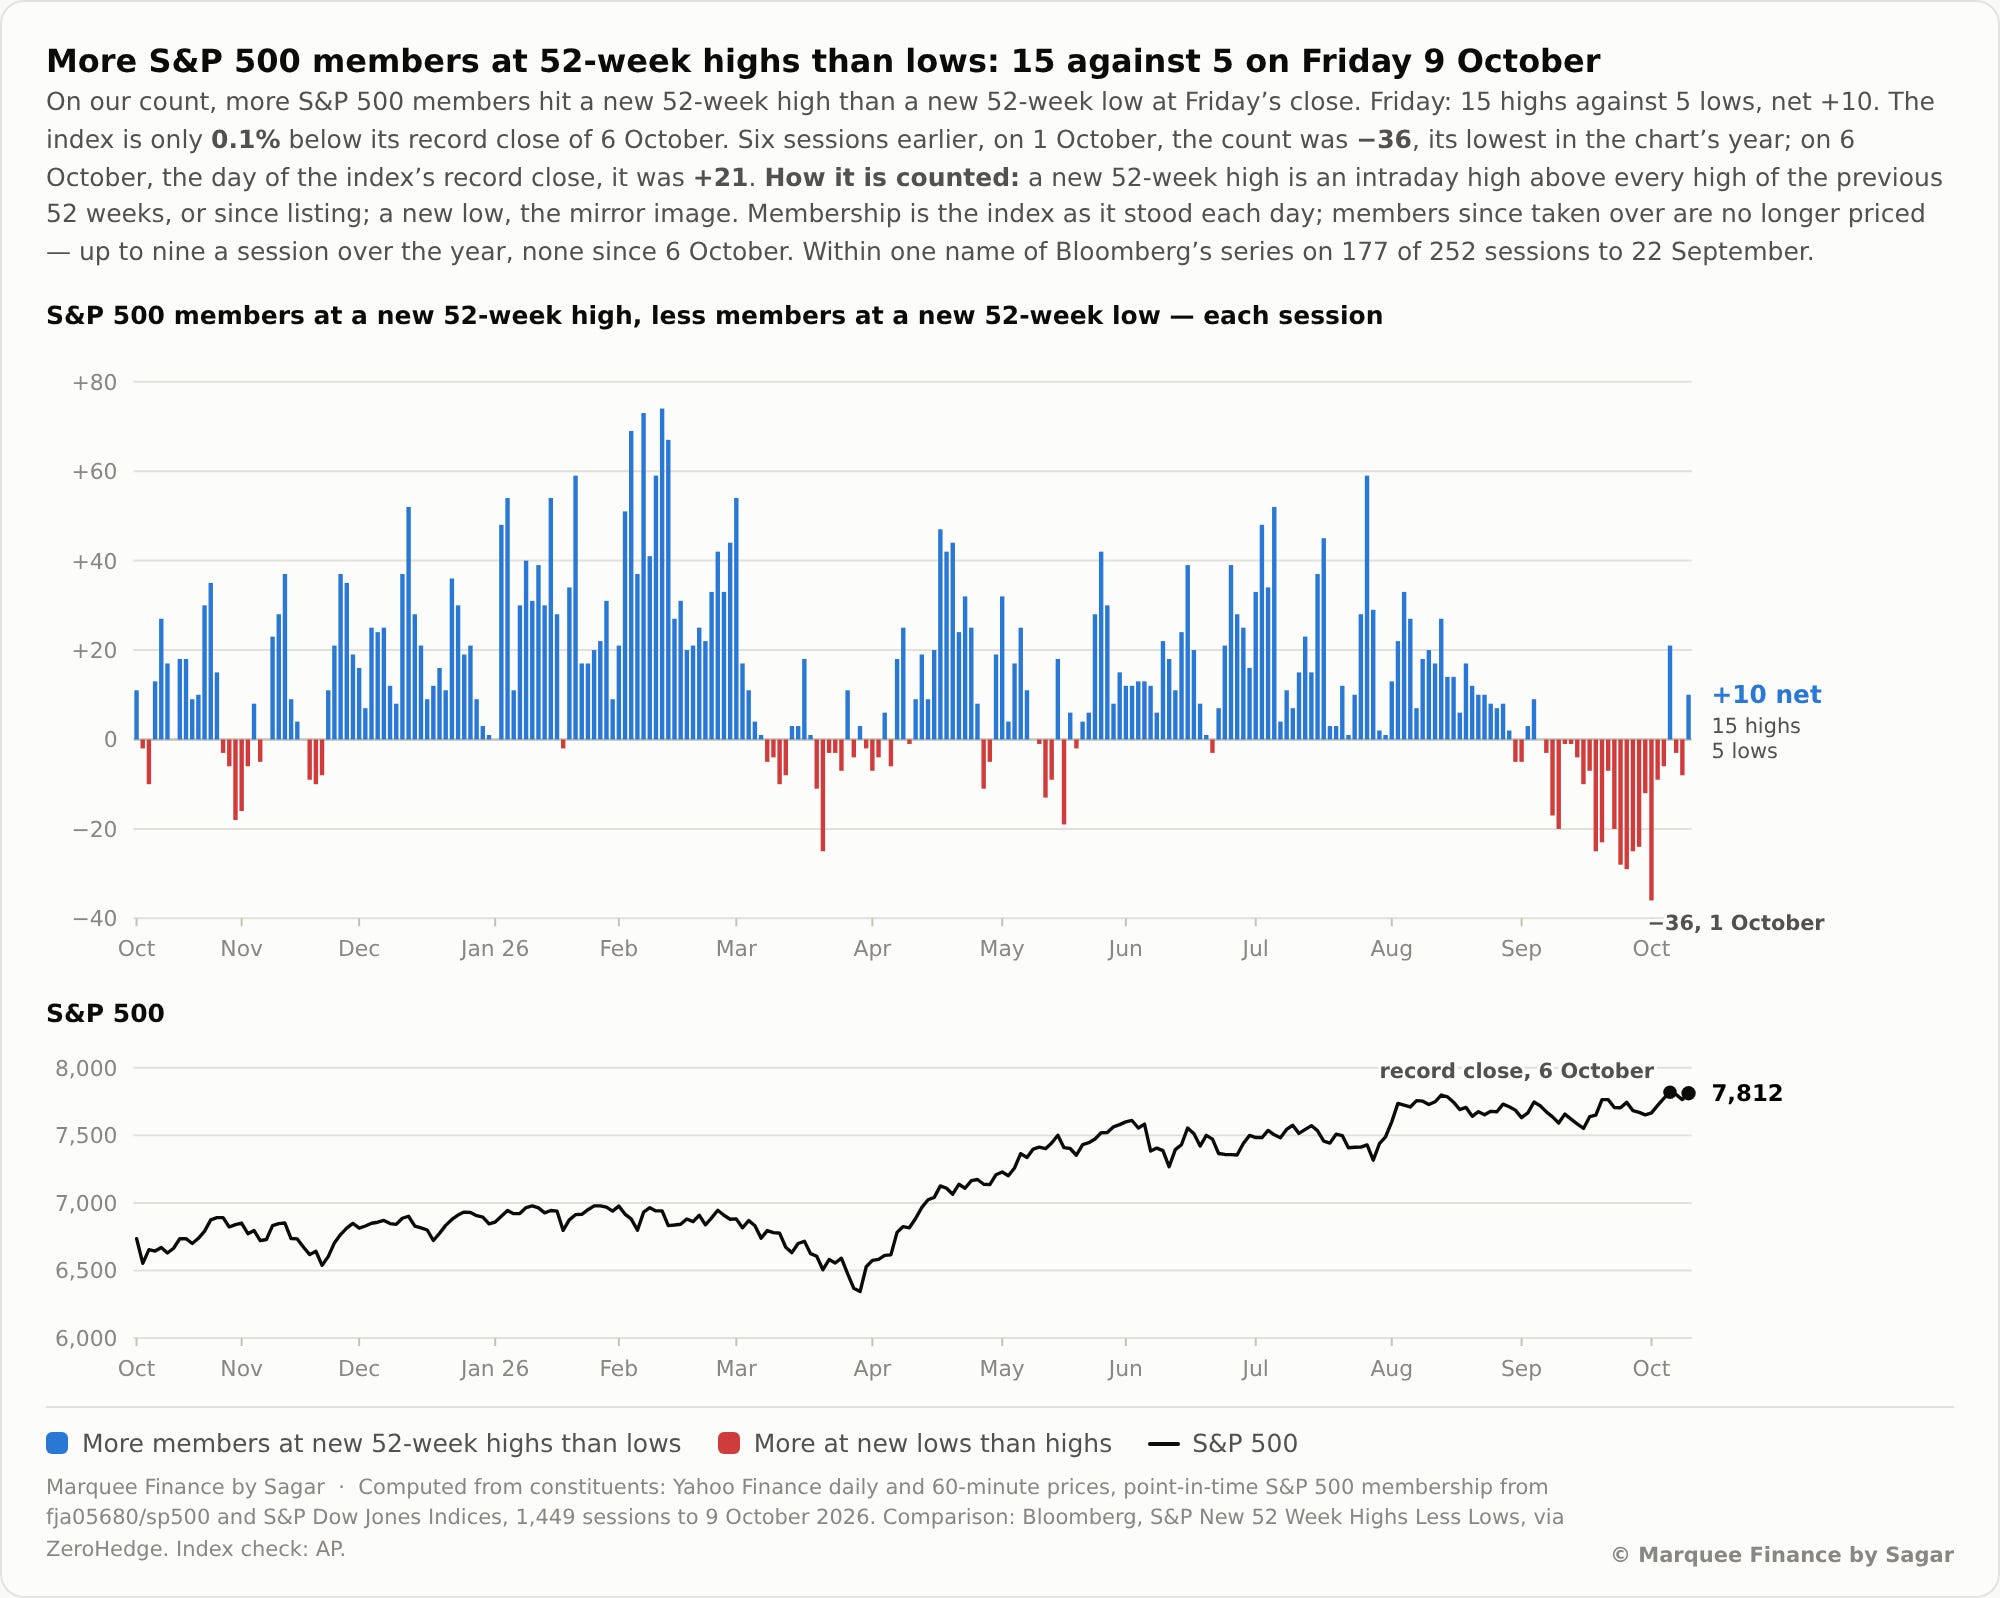
S&P 500 members at 52-week highs, rather than lows, were positive after a streak of negative prints throughout late September.
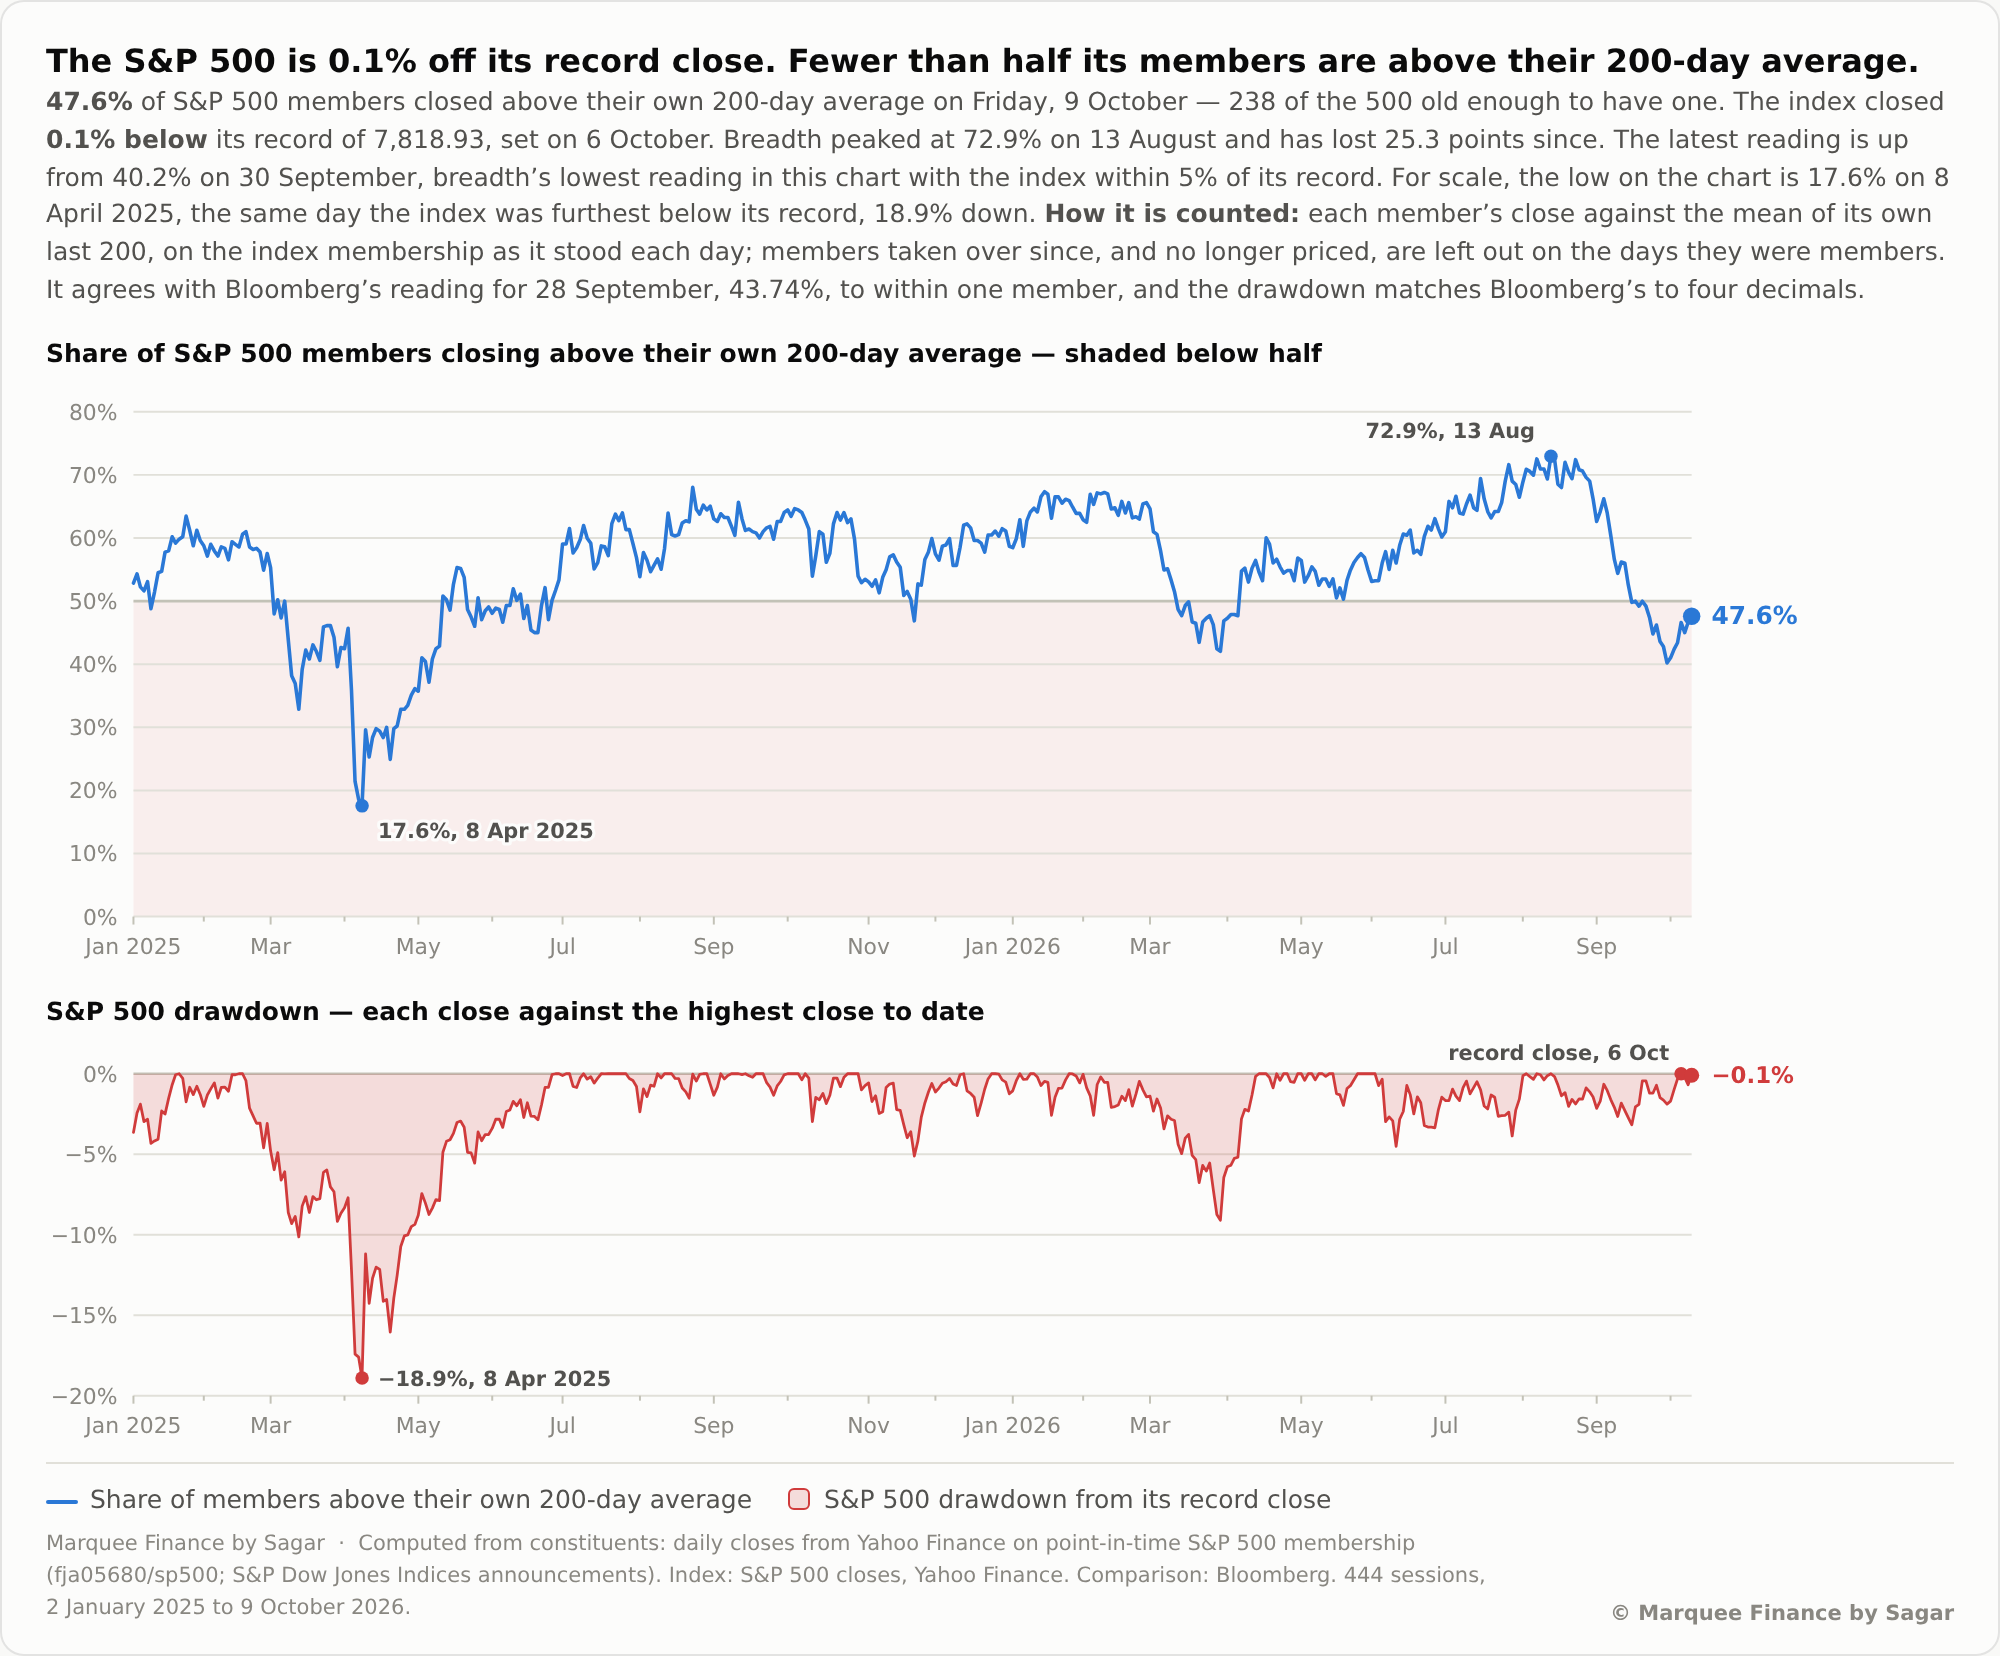
Nonetheless, 47.6% of its members were still below 200 DEMA, a mind-boggling figure for an index at ATH.
When we look at charts,