

We saw an unimaginable turn of events in less than a week as Jensen Huang, one of the world's most admired men, lost 33 years of credibility in hours.
Over the last few months, we have raised concerns about circular financing in the AI ecosystem, which has reached alarming levels.
Credit investors were the first to get out, as they have been bidding up the Credit Default Swap (CDS) prices of chip companies since August, when Chinese open-source models flooded the markets and began gaining market share from closed frontier models in the US.
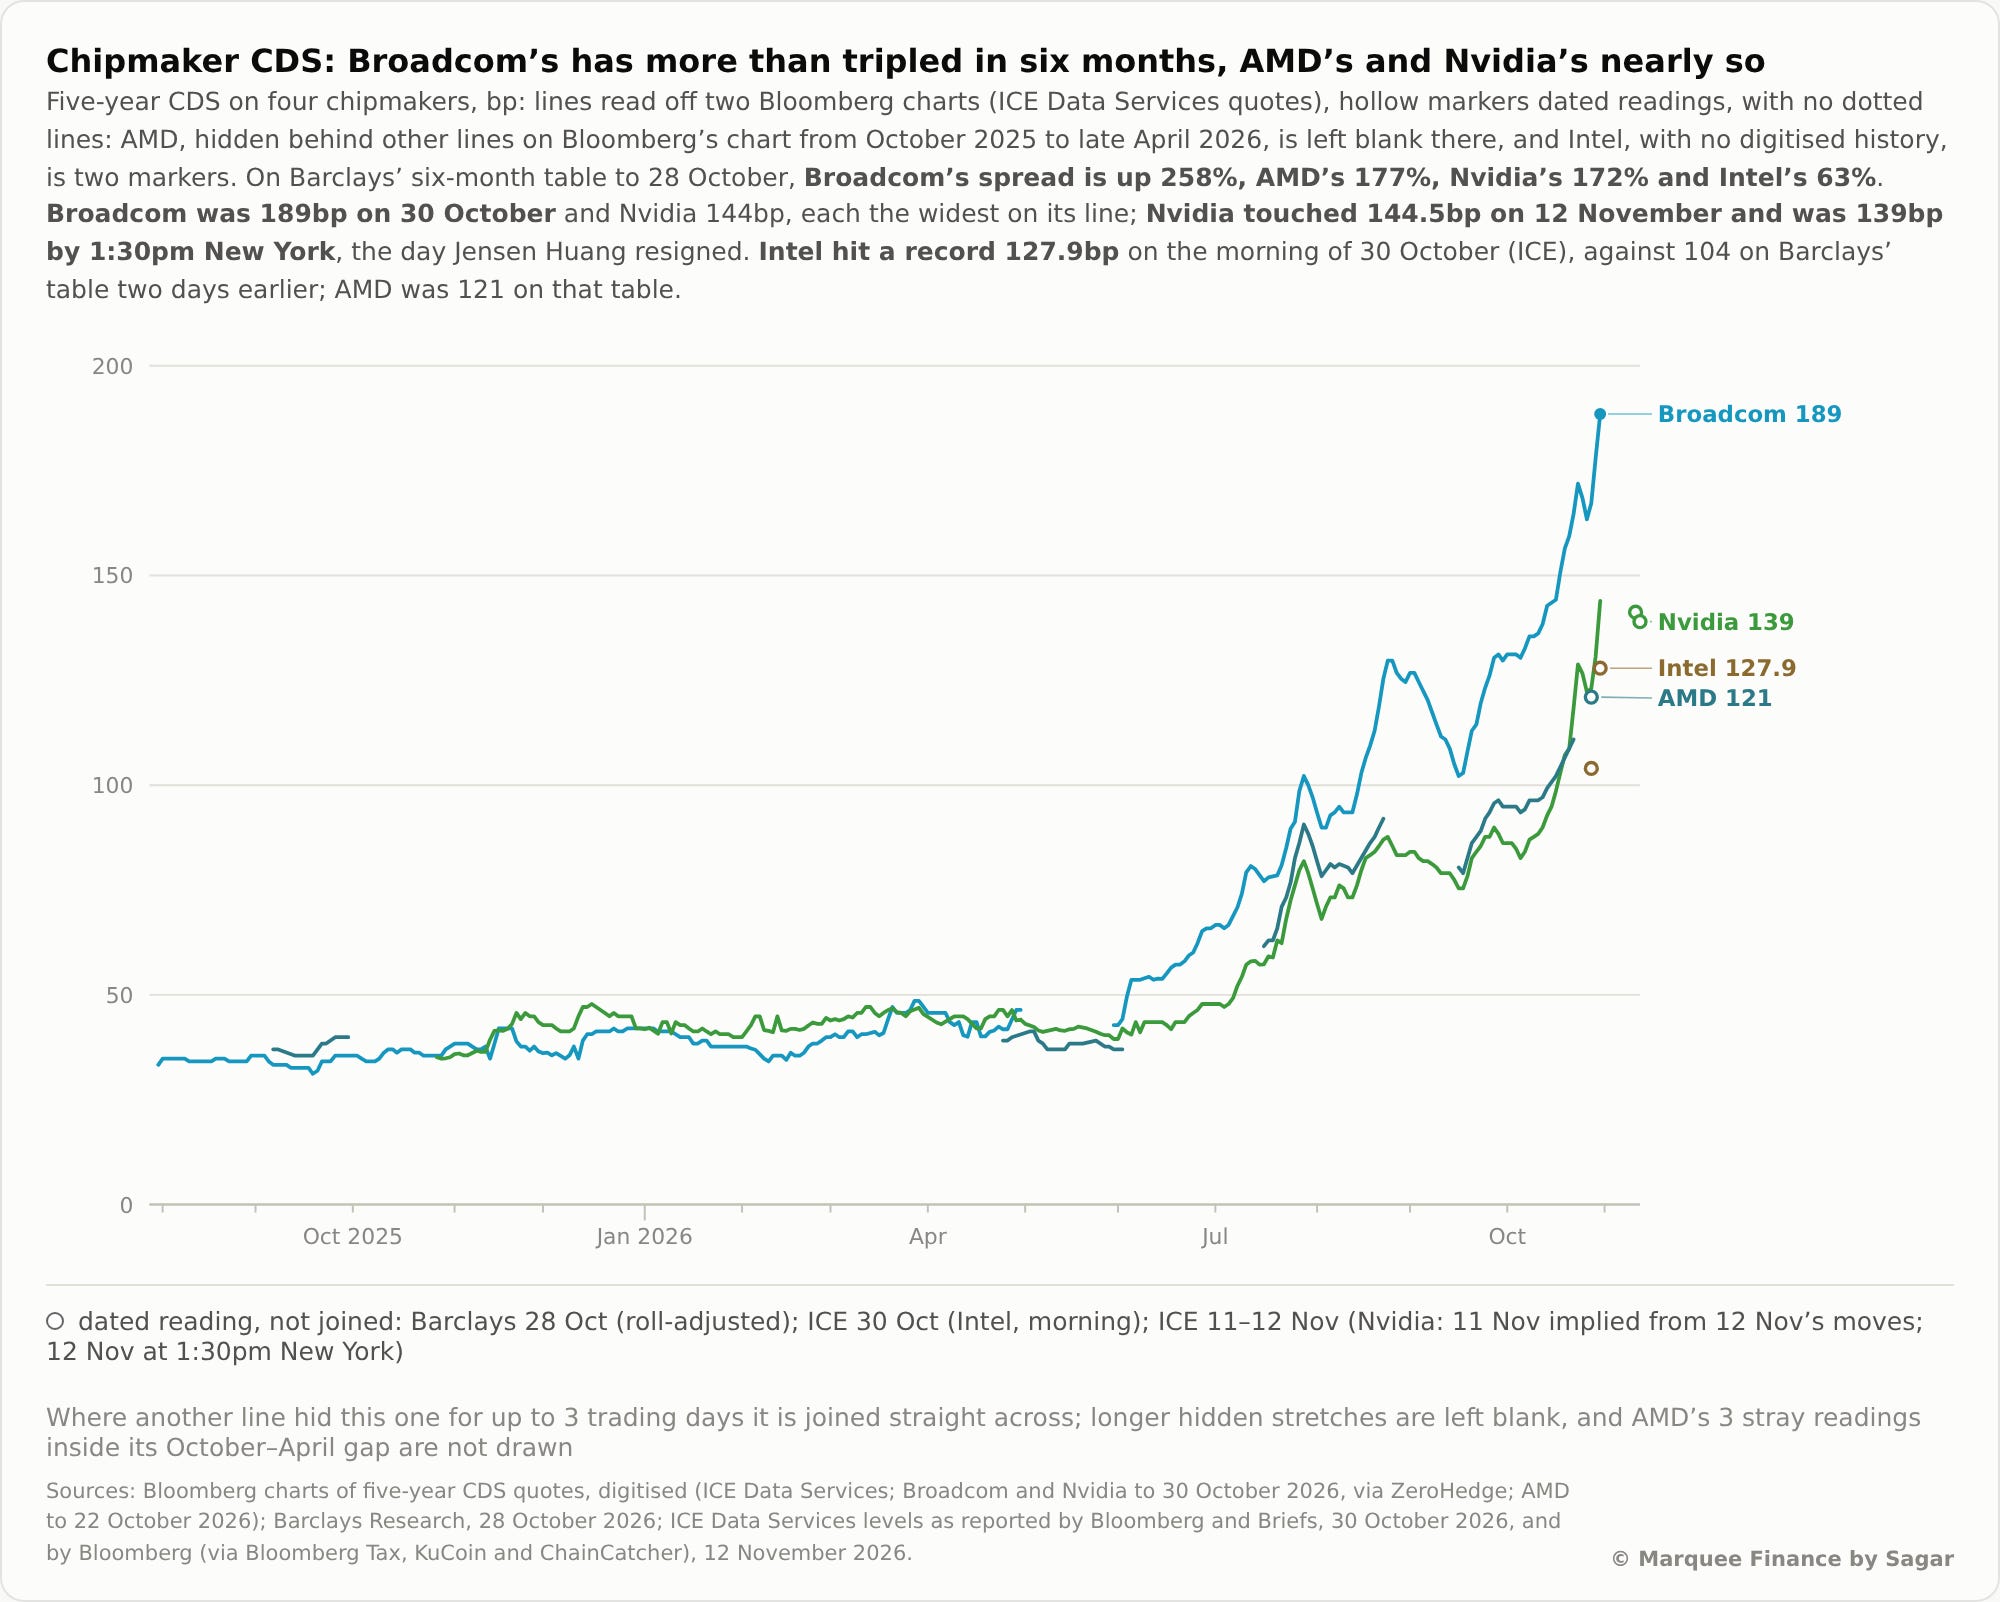
When we analyse NVDA, it’s a complete howler.
The company has been violating export controls (smuggling chips into China), has been at the centre of the AI circle jerk (also popularly known as the Central Bank of AI), and we now worry that if the bets go sour, we could head to bankruptcy.
It holds $99 billion in stakes in companies, including neoclouds such as CoreWeave and Nebius, whose financials have deteriorated due to high leverage.
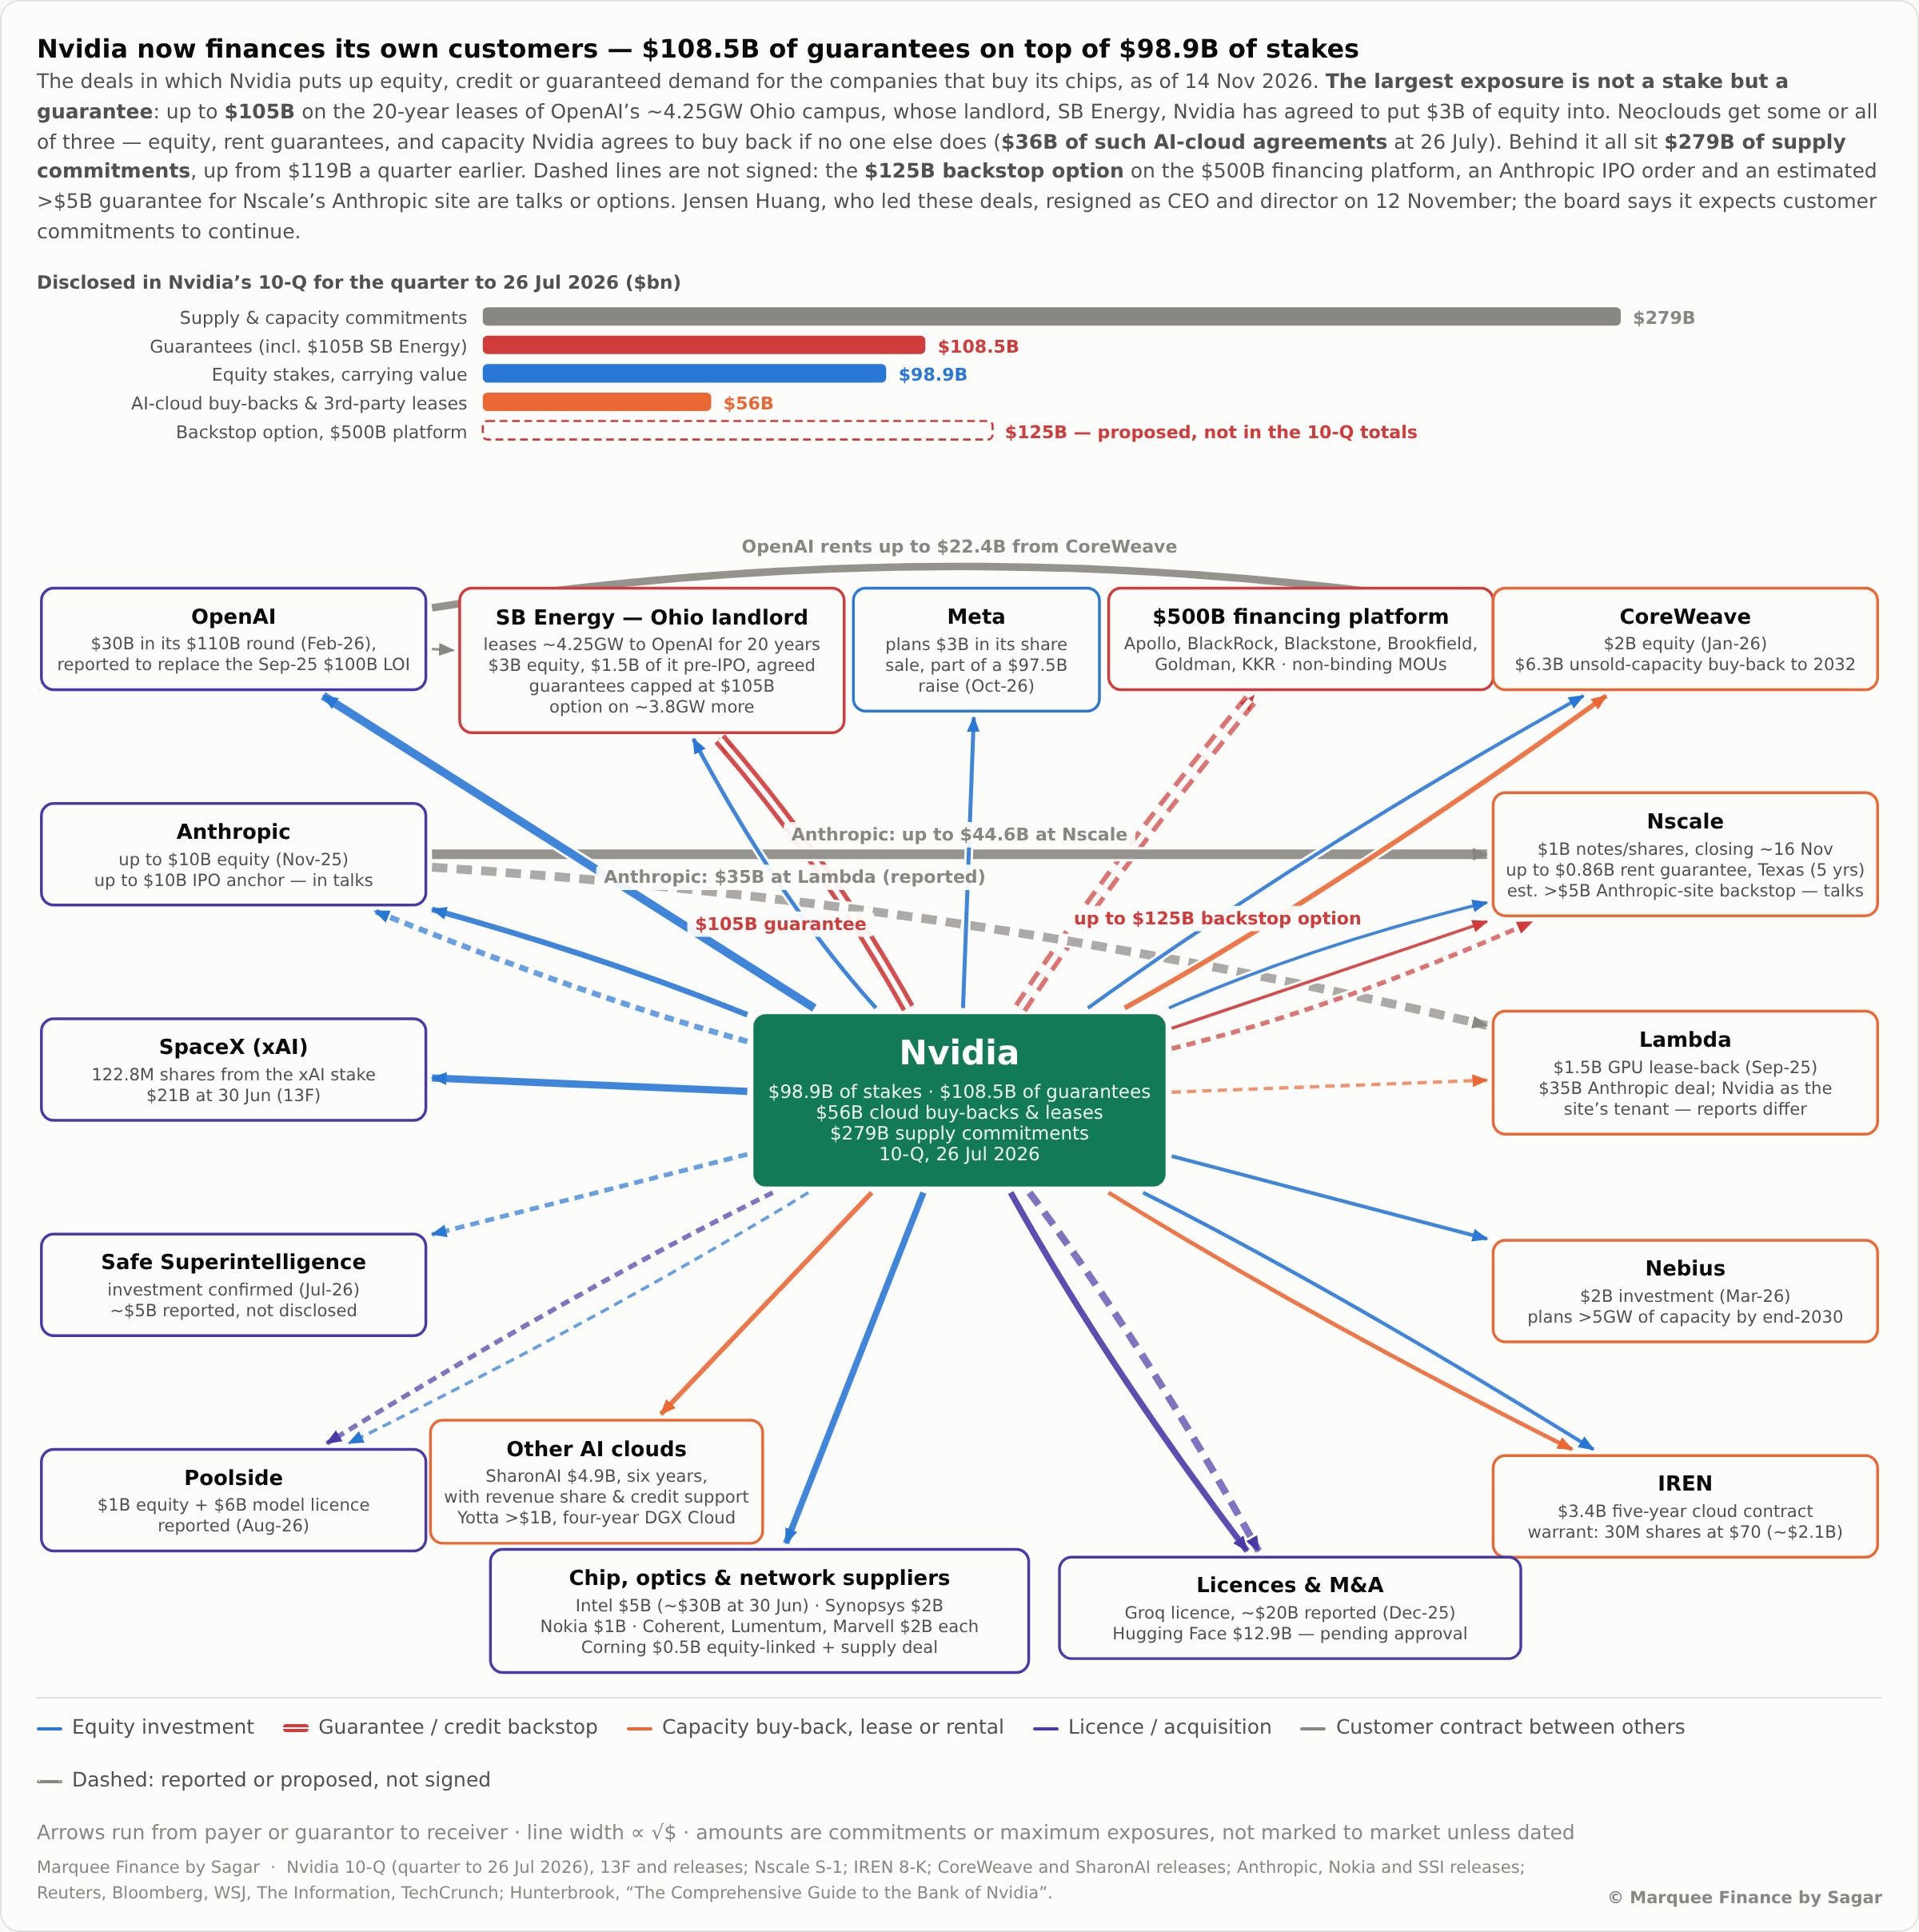
Furthermore, NVDA holds $105 billion of guarantees and $279 billion of supply commitments. With rising competition from AMD, AVGO, and GOOG, we believe the company will struggle to meet its commitments without Huang.
On the balance sheet, the company holds just $23 billion in net cash.
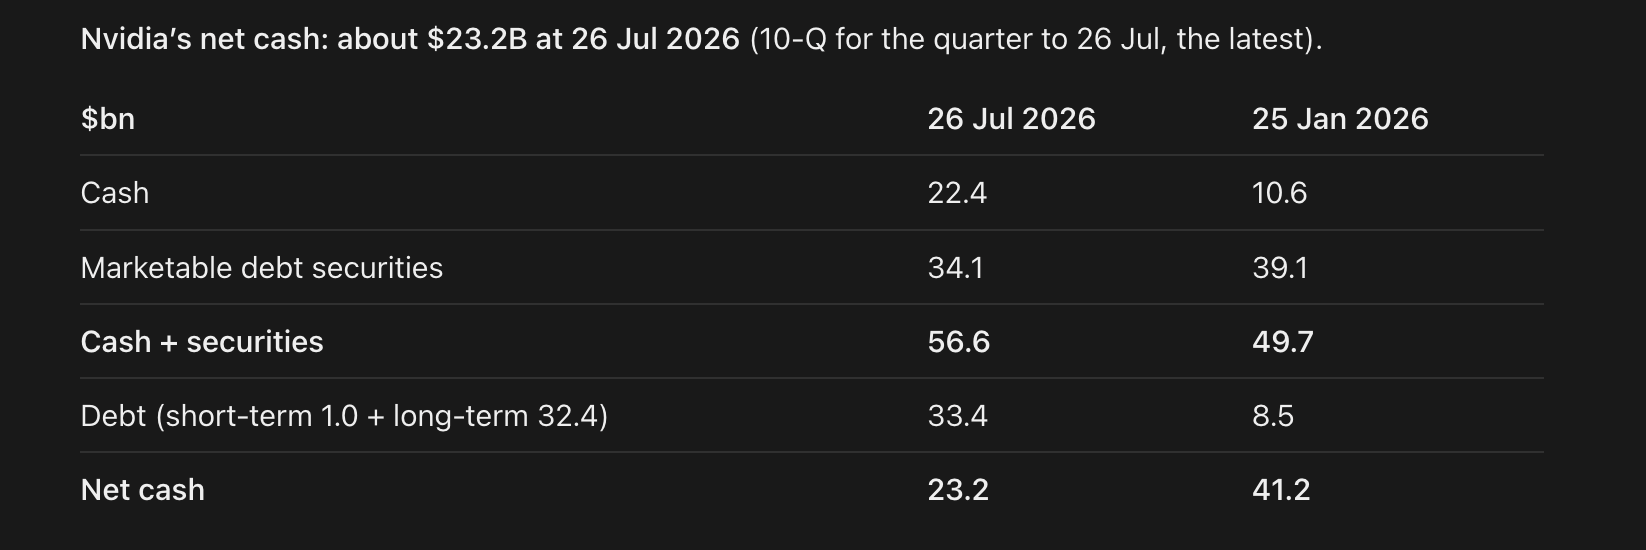
The mind-boggling fact is that the net cash almost halved in six months, even with $118B of net income in that time. The money went into equity stakes (about $31B added to private holdings), $39.8B in buybacks, and $6.3B in dividends. Debt also rose by about $25B.
Despite only $23 billion in net cash, the company bought $40 billion in shares in H1, which is overall baffling and underscores the need for a financial audit.
Thus, we can safely conclude that the “Emperor Has No Clothes”.
The technicals indicated trouble was brewing in the company, and we successfully shorted NVDA on 2nd November.
We have now completely booked profits on the short position.

Thanks to our short book and our large positions in the anti-AI trade, we have navigated the tumultuous environment successfully.
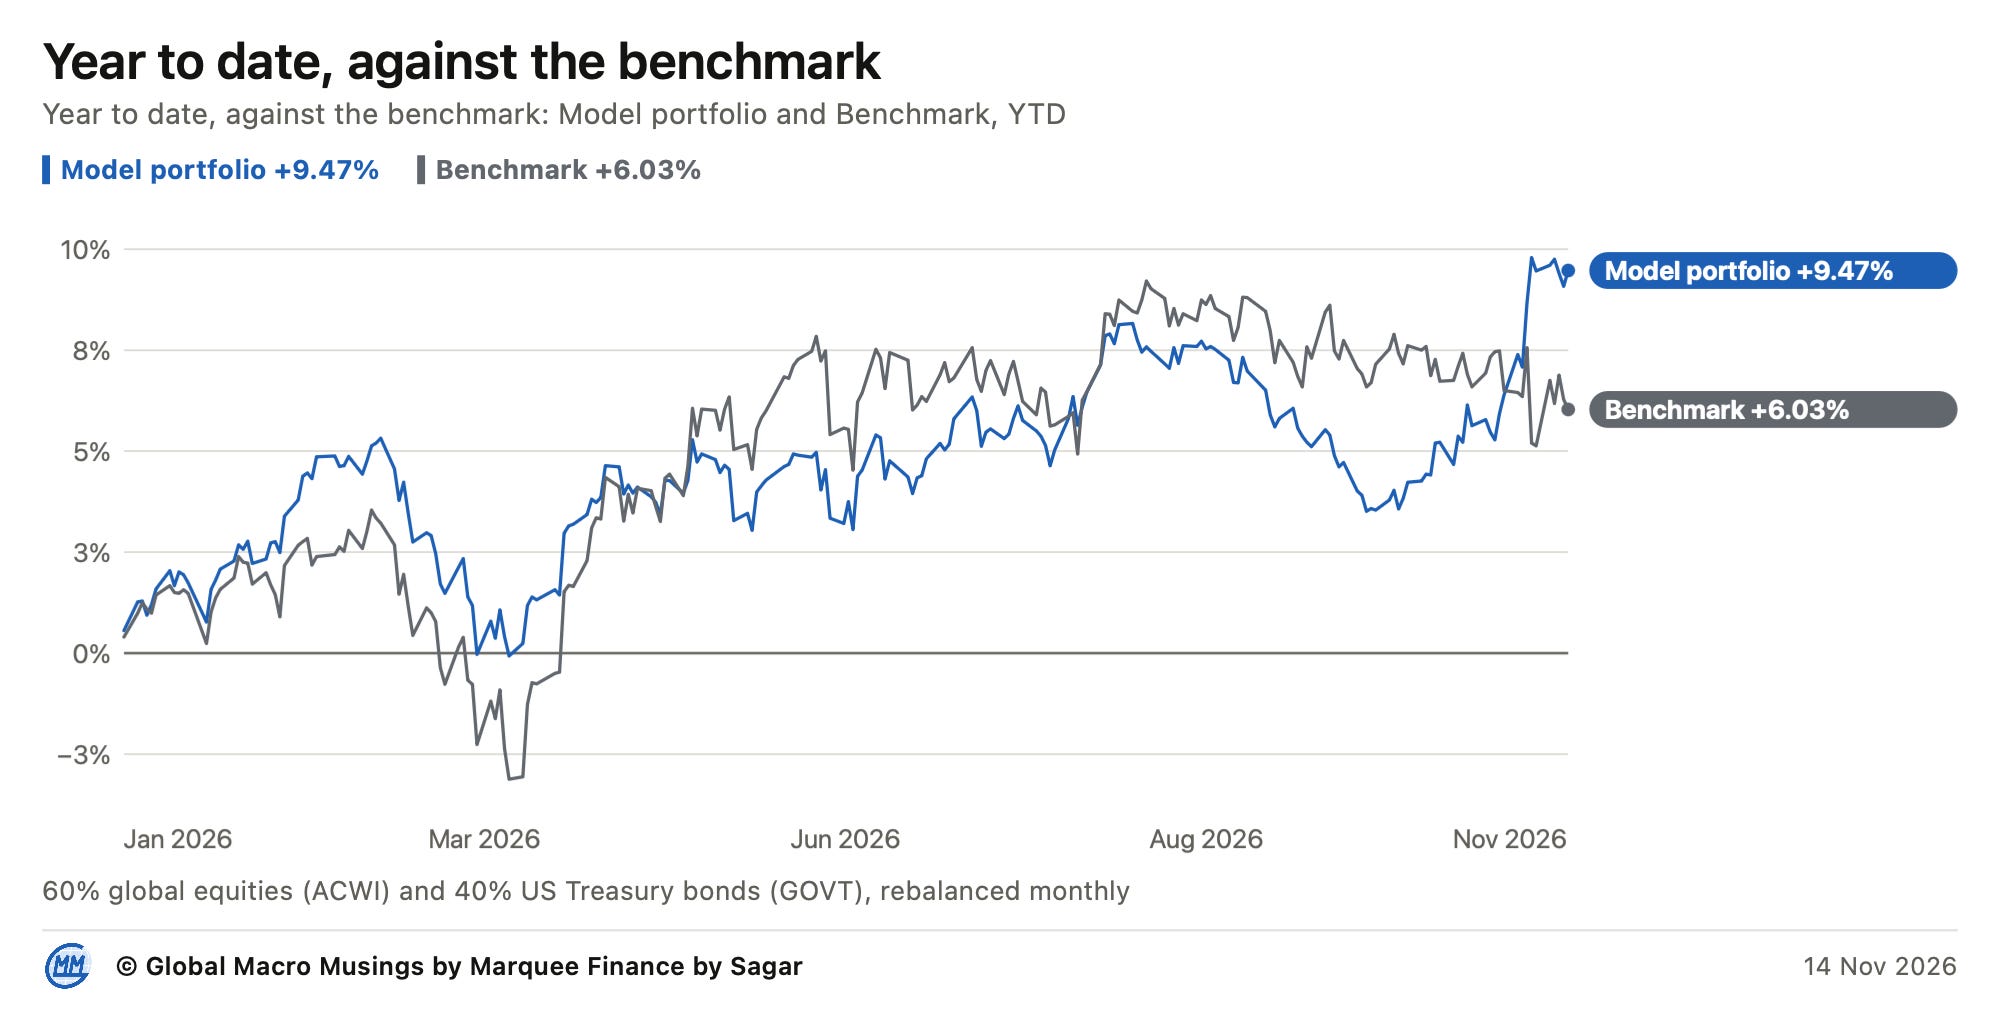
We are now up 9.47% YTD and are outperforming the benchmark by 340 bps.
PS: The launch date for Global Macro Musings for free subscribers has been finalised as 28th November 2026!
We have built an exciting product, and it has now also been integrated with Claude as well. You all will absolutely love it!!!
US/Equities/Bonds/Gold/Oil/Dollar/BTC!
The uptrend in the US CPI continues.
Headline CPI came in at 0.4% MoM vs expectations of 0.3% MoM, and core CPI came in 10 bps higher than expectations at 0.3% MoM.
The Supercore CPI (Services Ex-Rent) also jumped to 4.3% annualised.
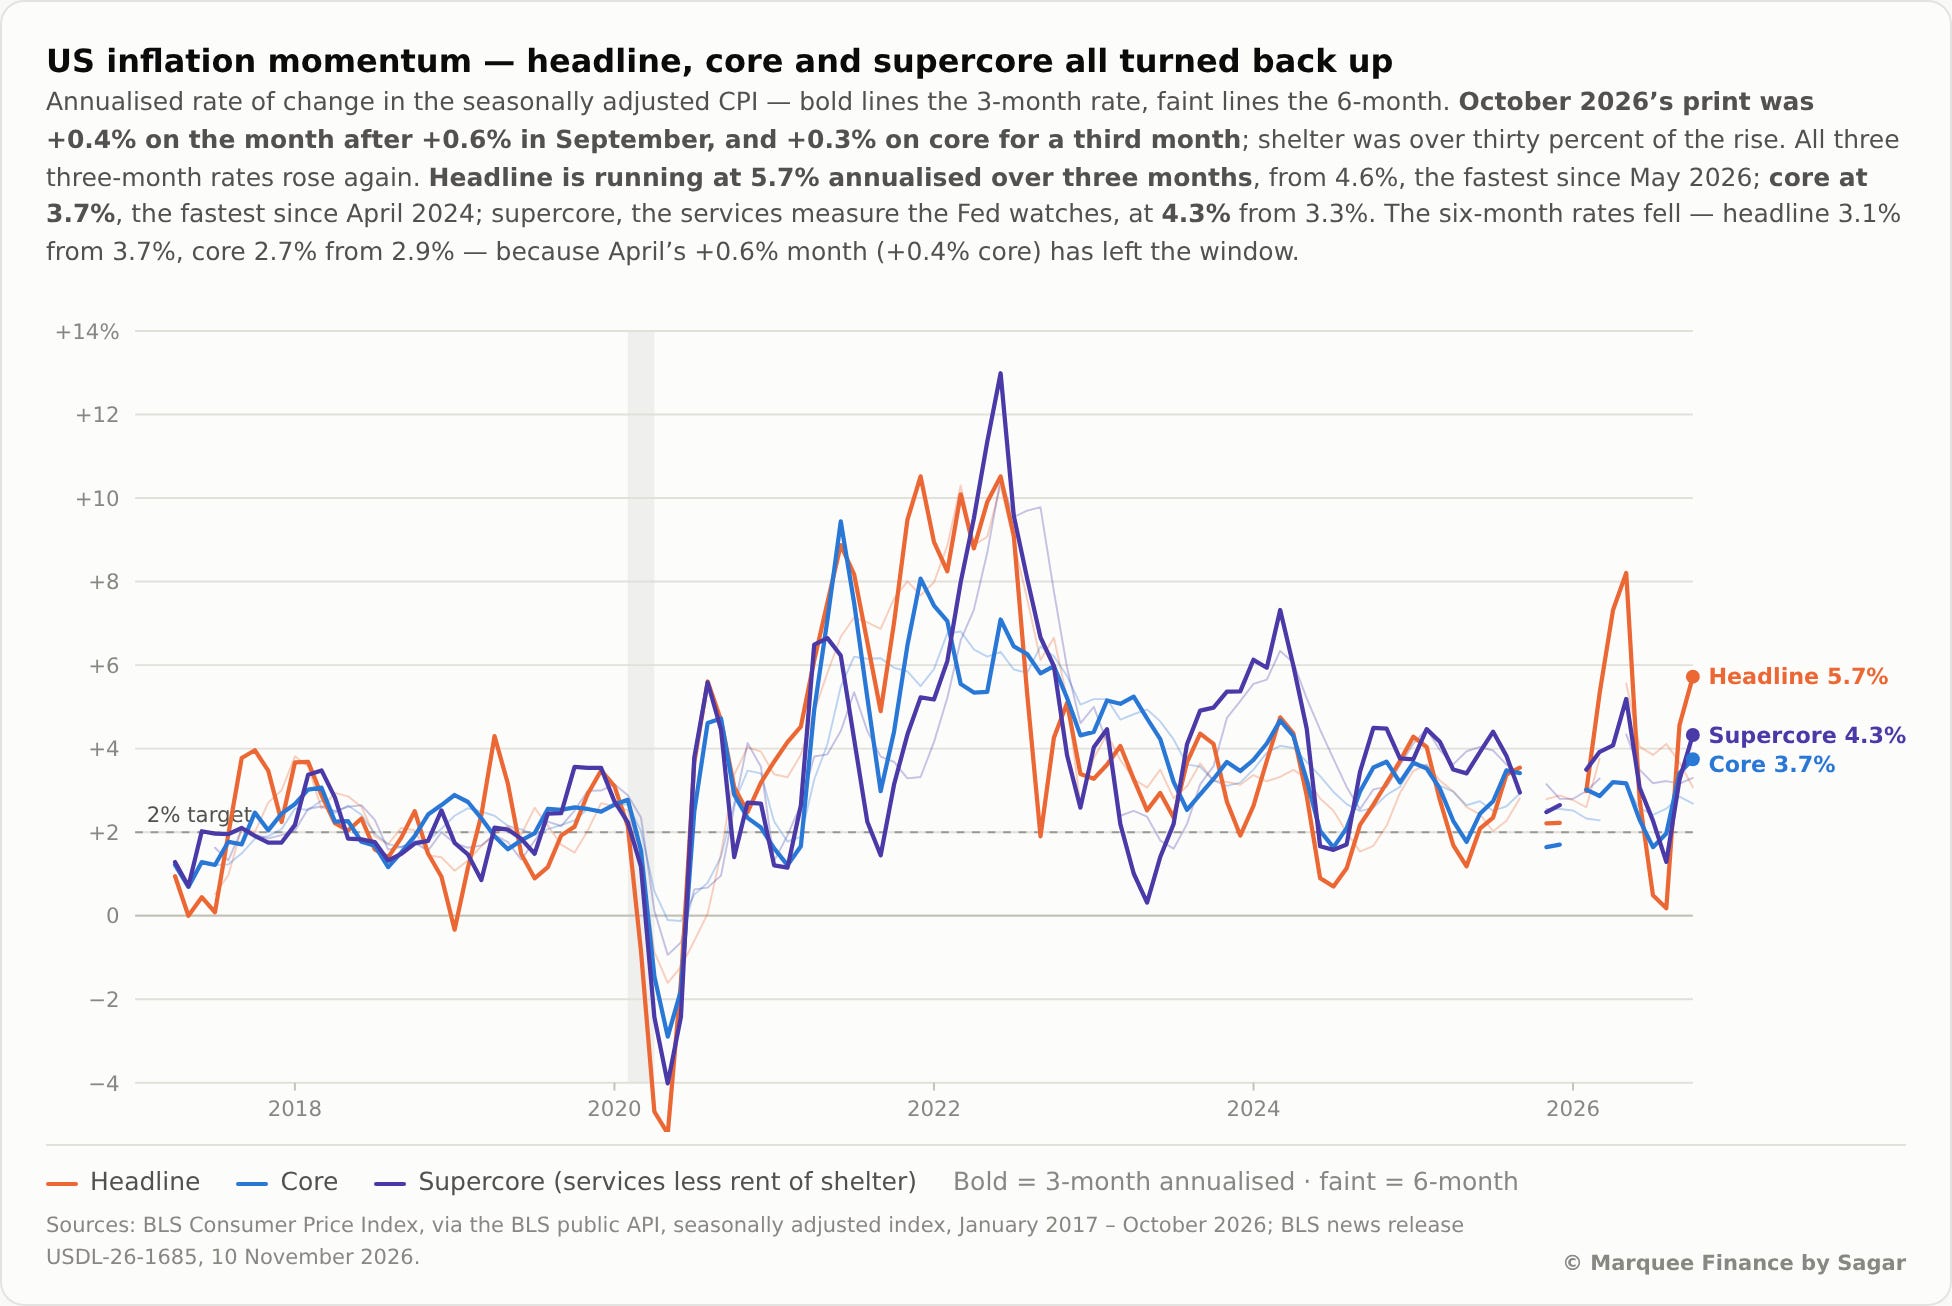
Note that the YoY figures were unavailable this time, as BLS didn’t print the October 2025 figures due to the prolonged US government shutdown last year.
As per the inflation breadth data, nearly half of the index by weight (52%) is running above 3%, indicating broad-based inflationary pressures.
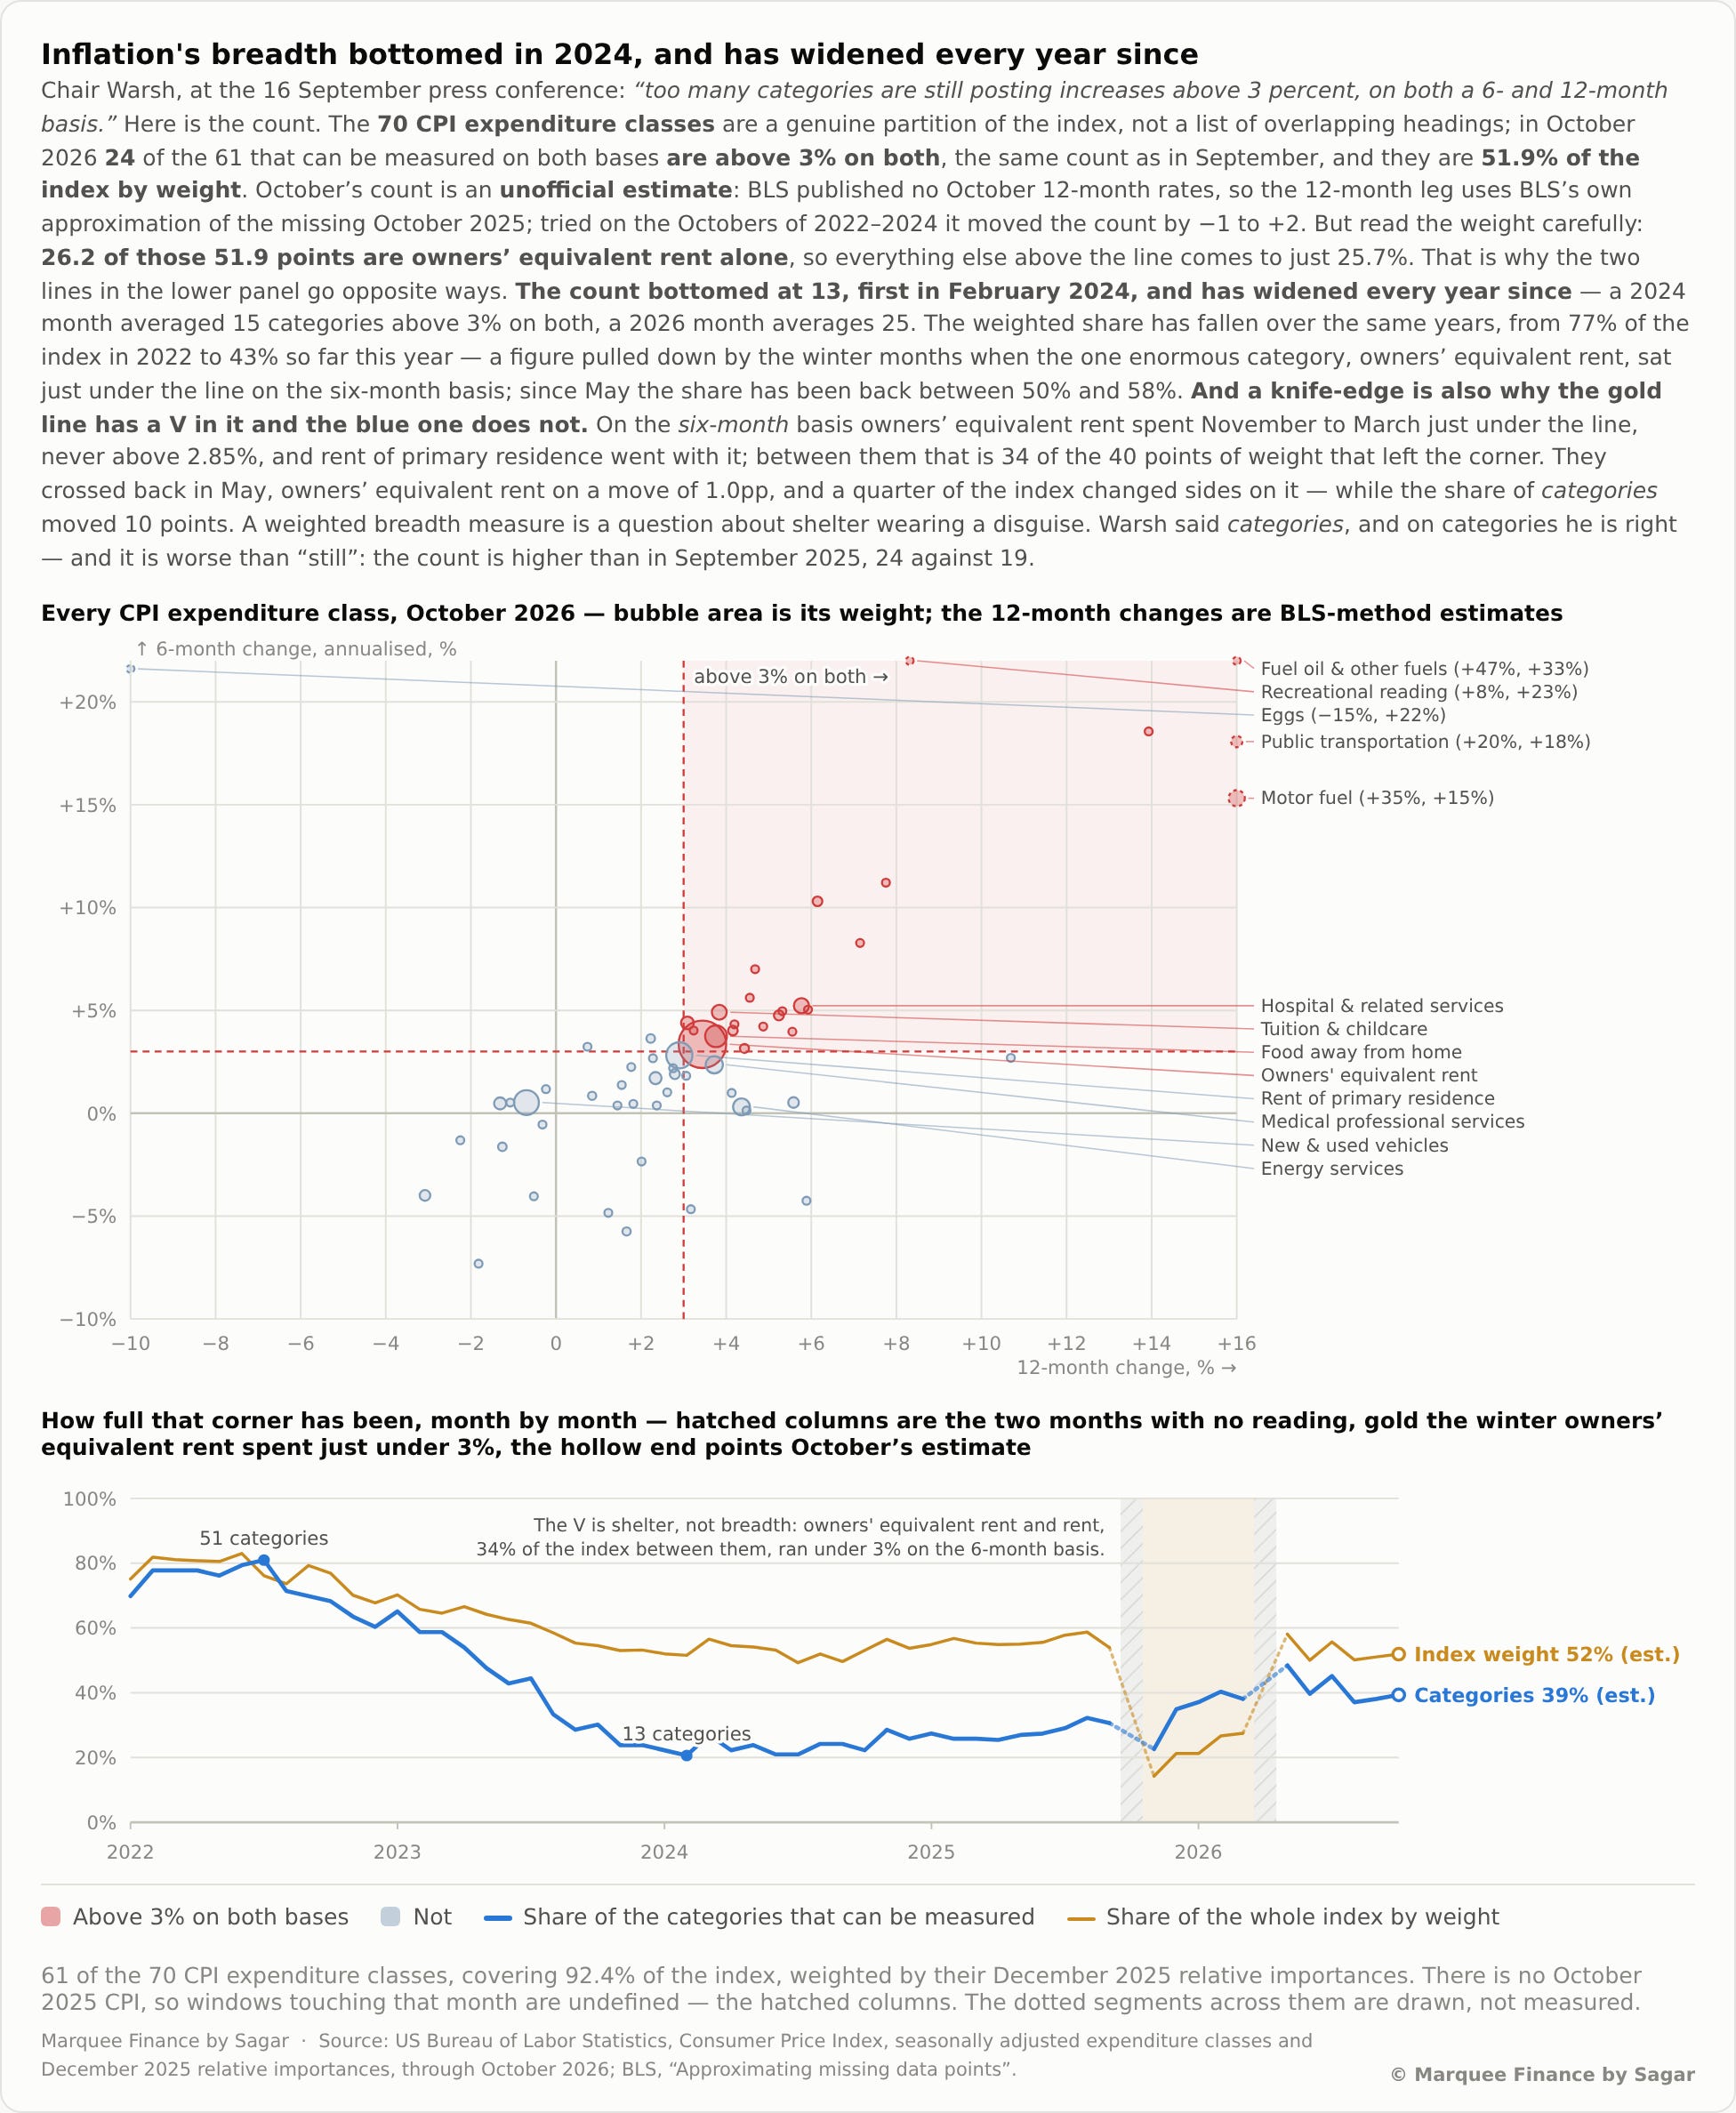
When we dig deeper and analyse the categories, ex-used cars and new vehicles, inflationary pressures can be seen across categories.
We will closely monitor motor vehicle insurance, as it’s a big contributor to the supercore, and with rising rates, it will move higher, as we saw in 2022.
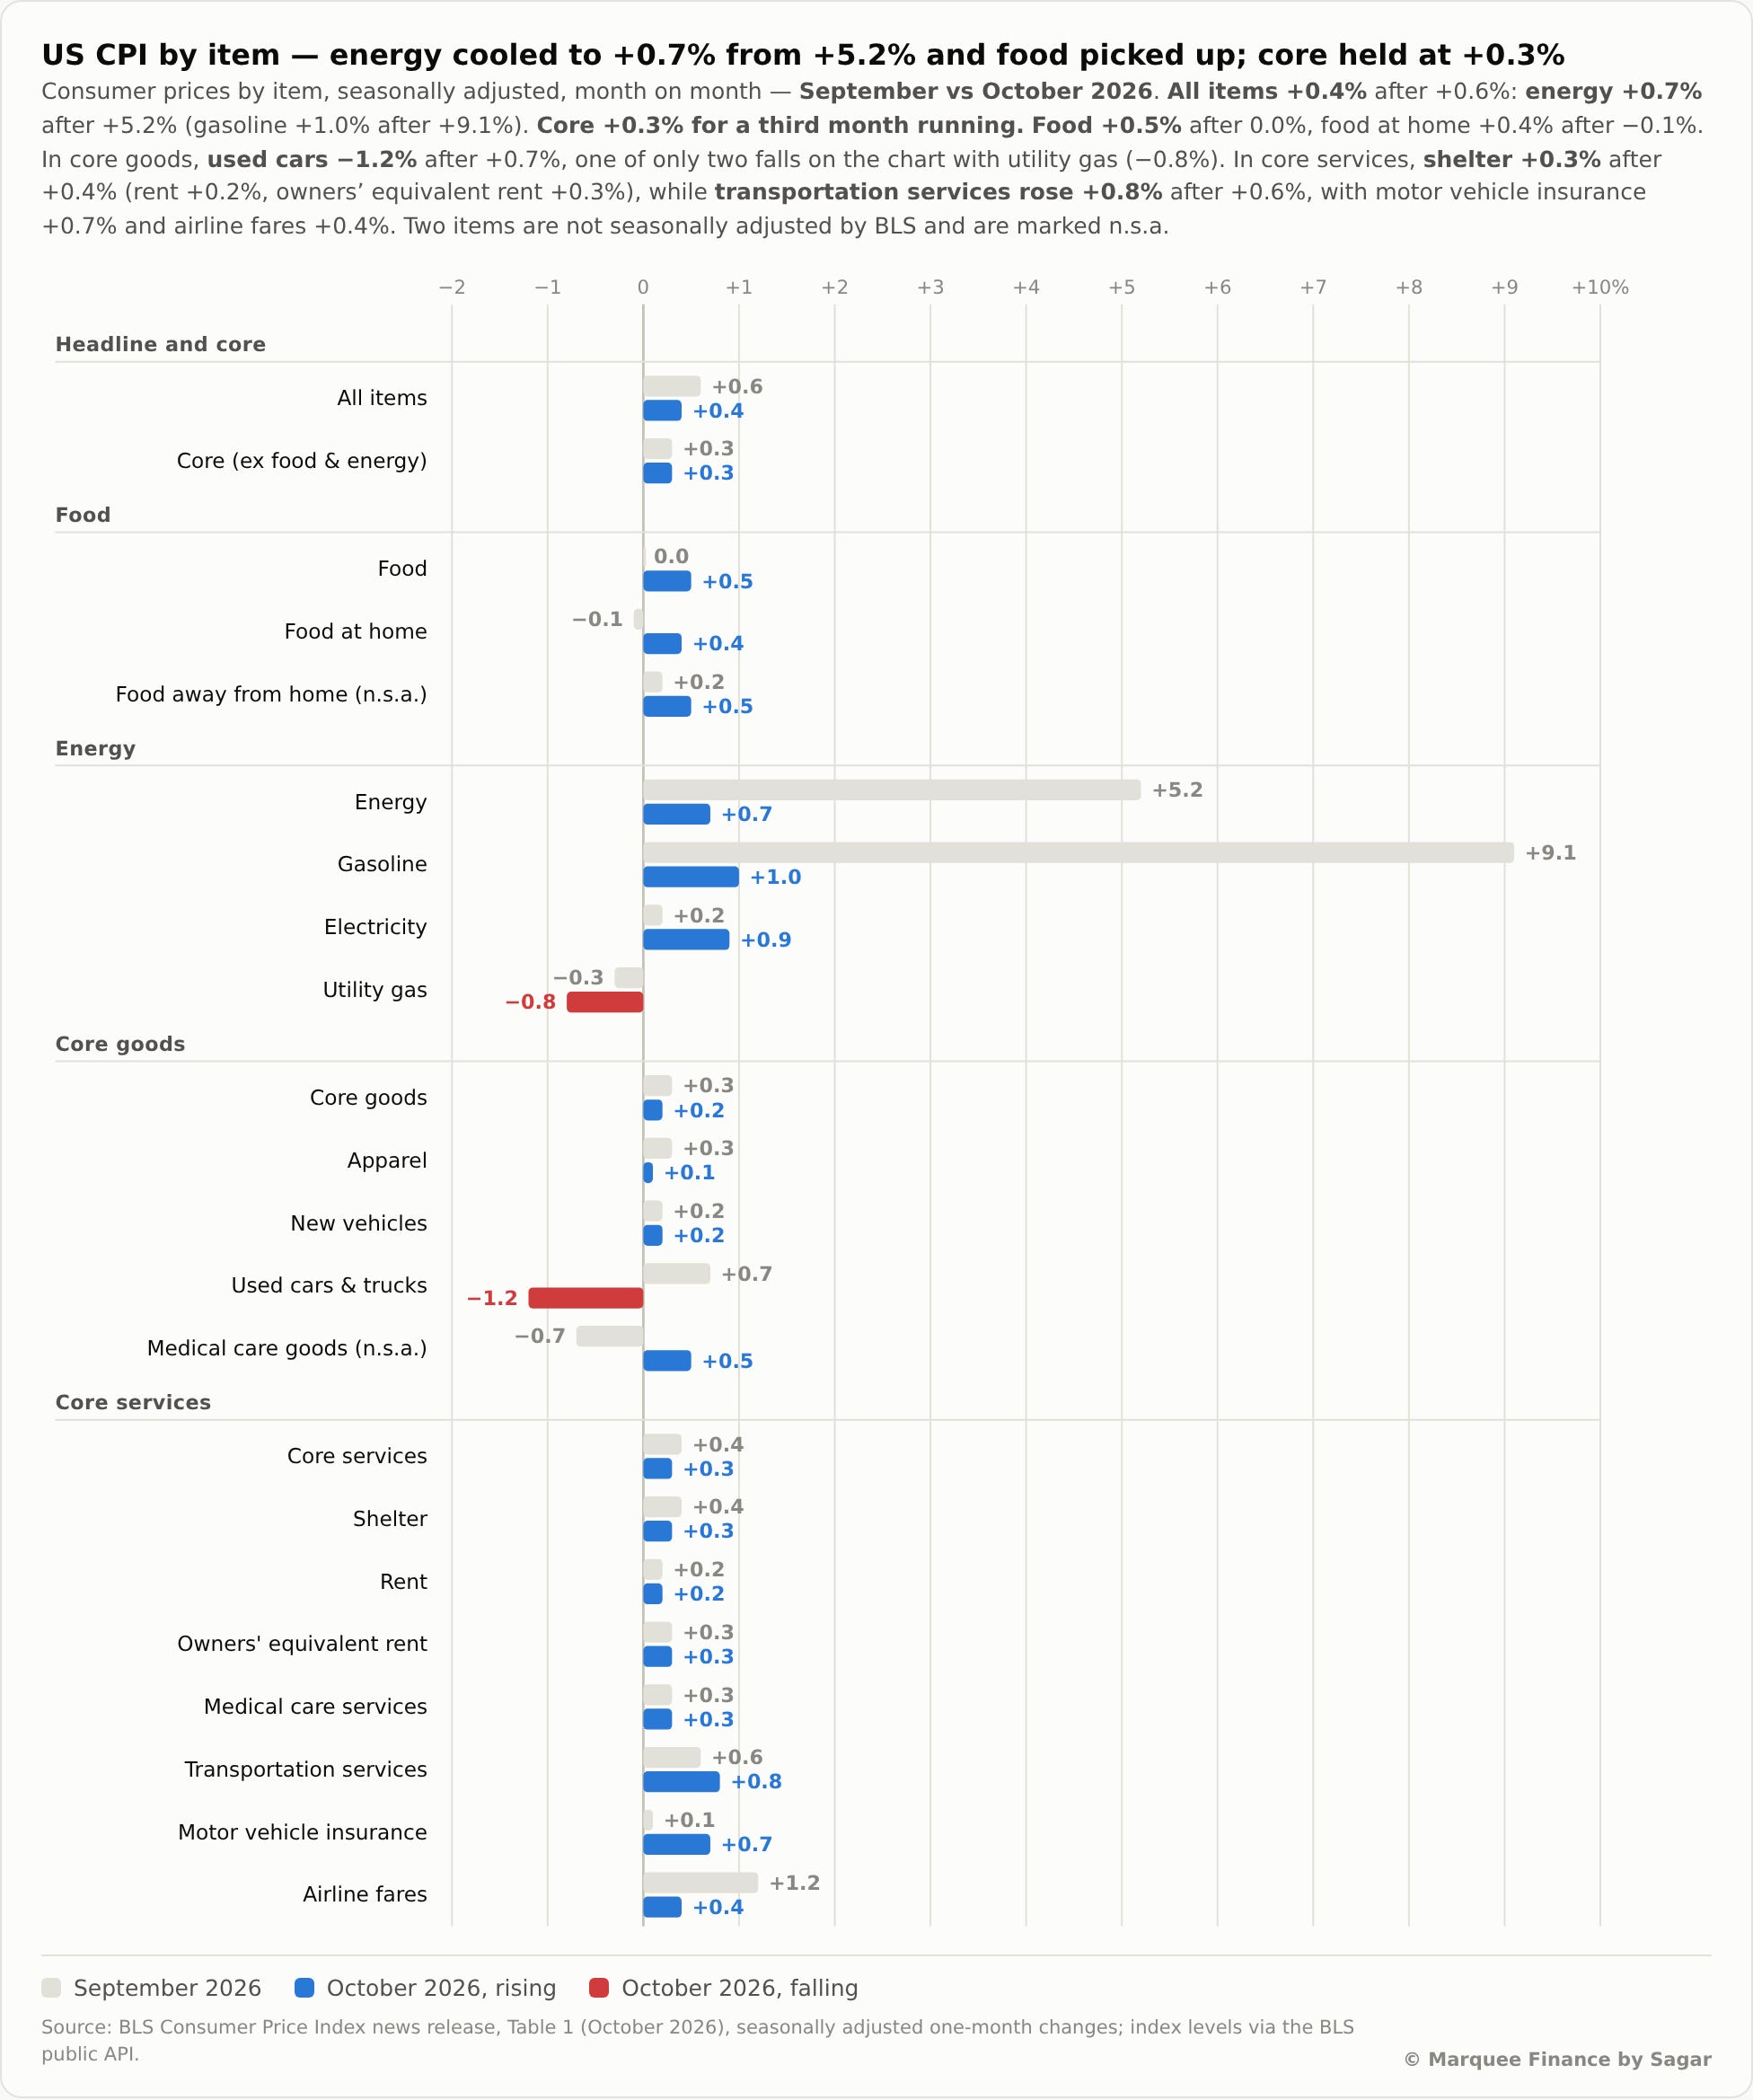
We've been saying that persistently higher energy prices eventually lead to broader inflationary pressures, which is visible in the official data with a lag.
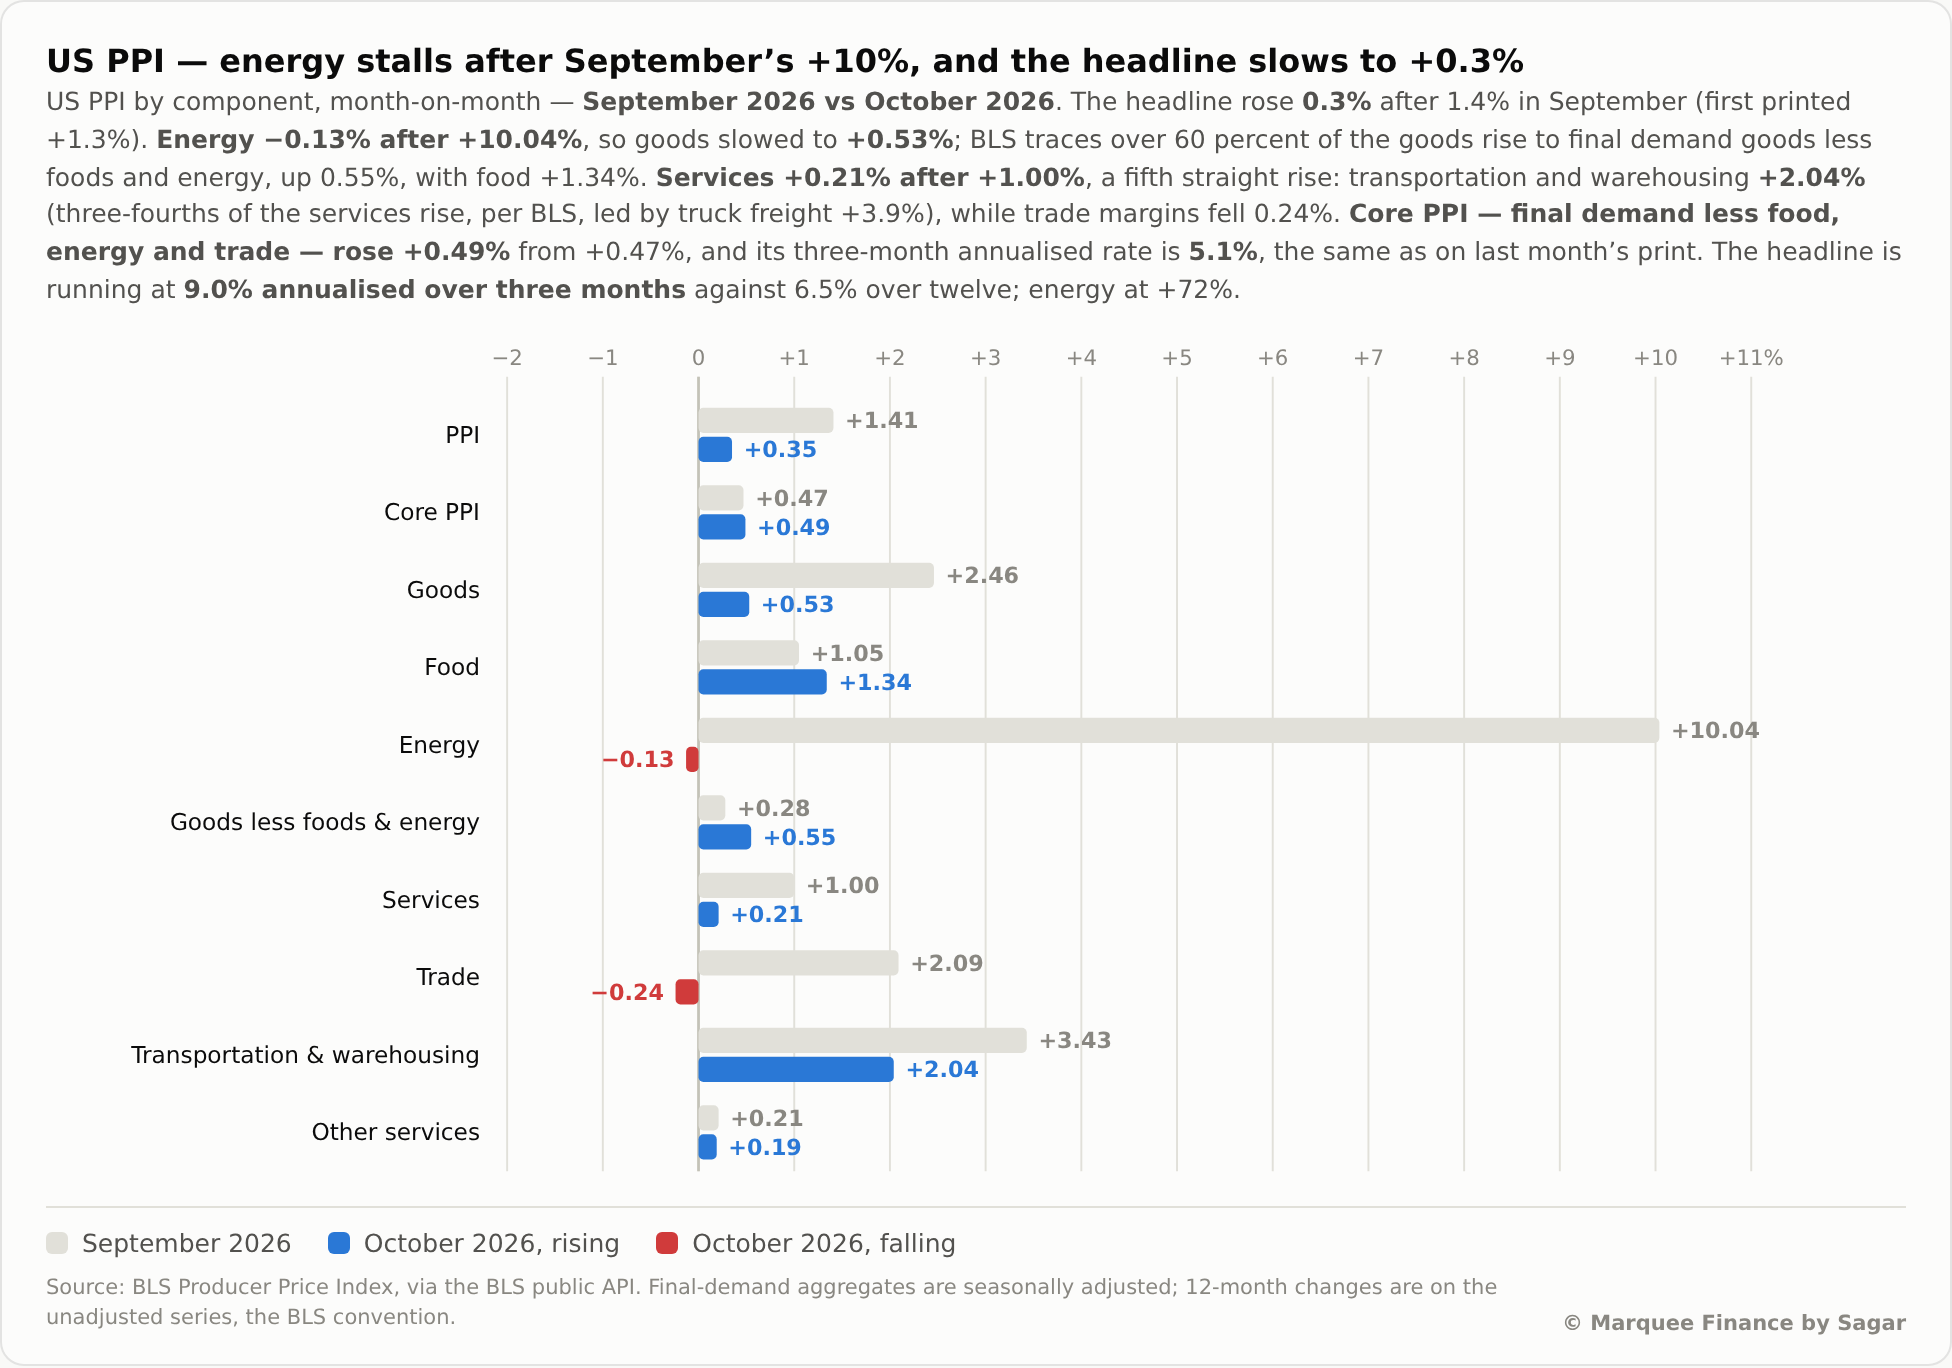
PPI was in line with expectations.
PPI has swung wildly in the past few months because of volatility in oil prices.
Both the headline and core PPI came in at 0.3% MoM.

Energy contributed negatively MoM due to a fall in oil prices.
Core PPI rose 0.49% MoM from 0.47% MoM.
In the NFIB Survey, Labour, taxes and inflation continue to rank as the top three in the “single most important problem”.
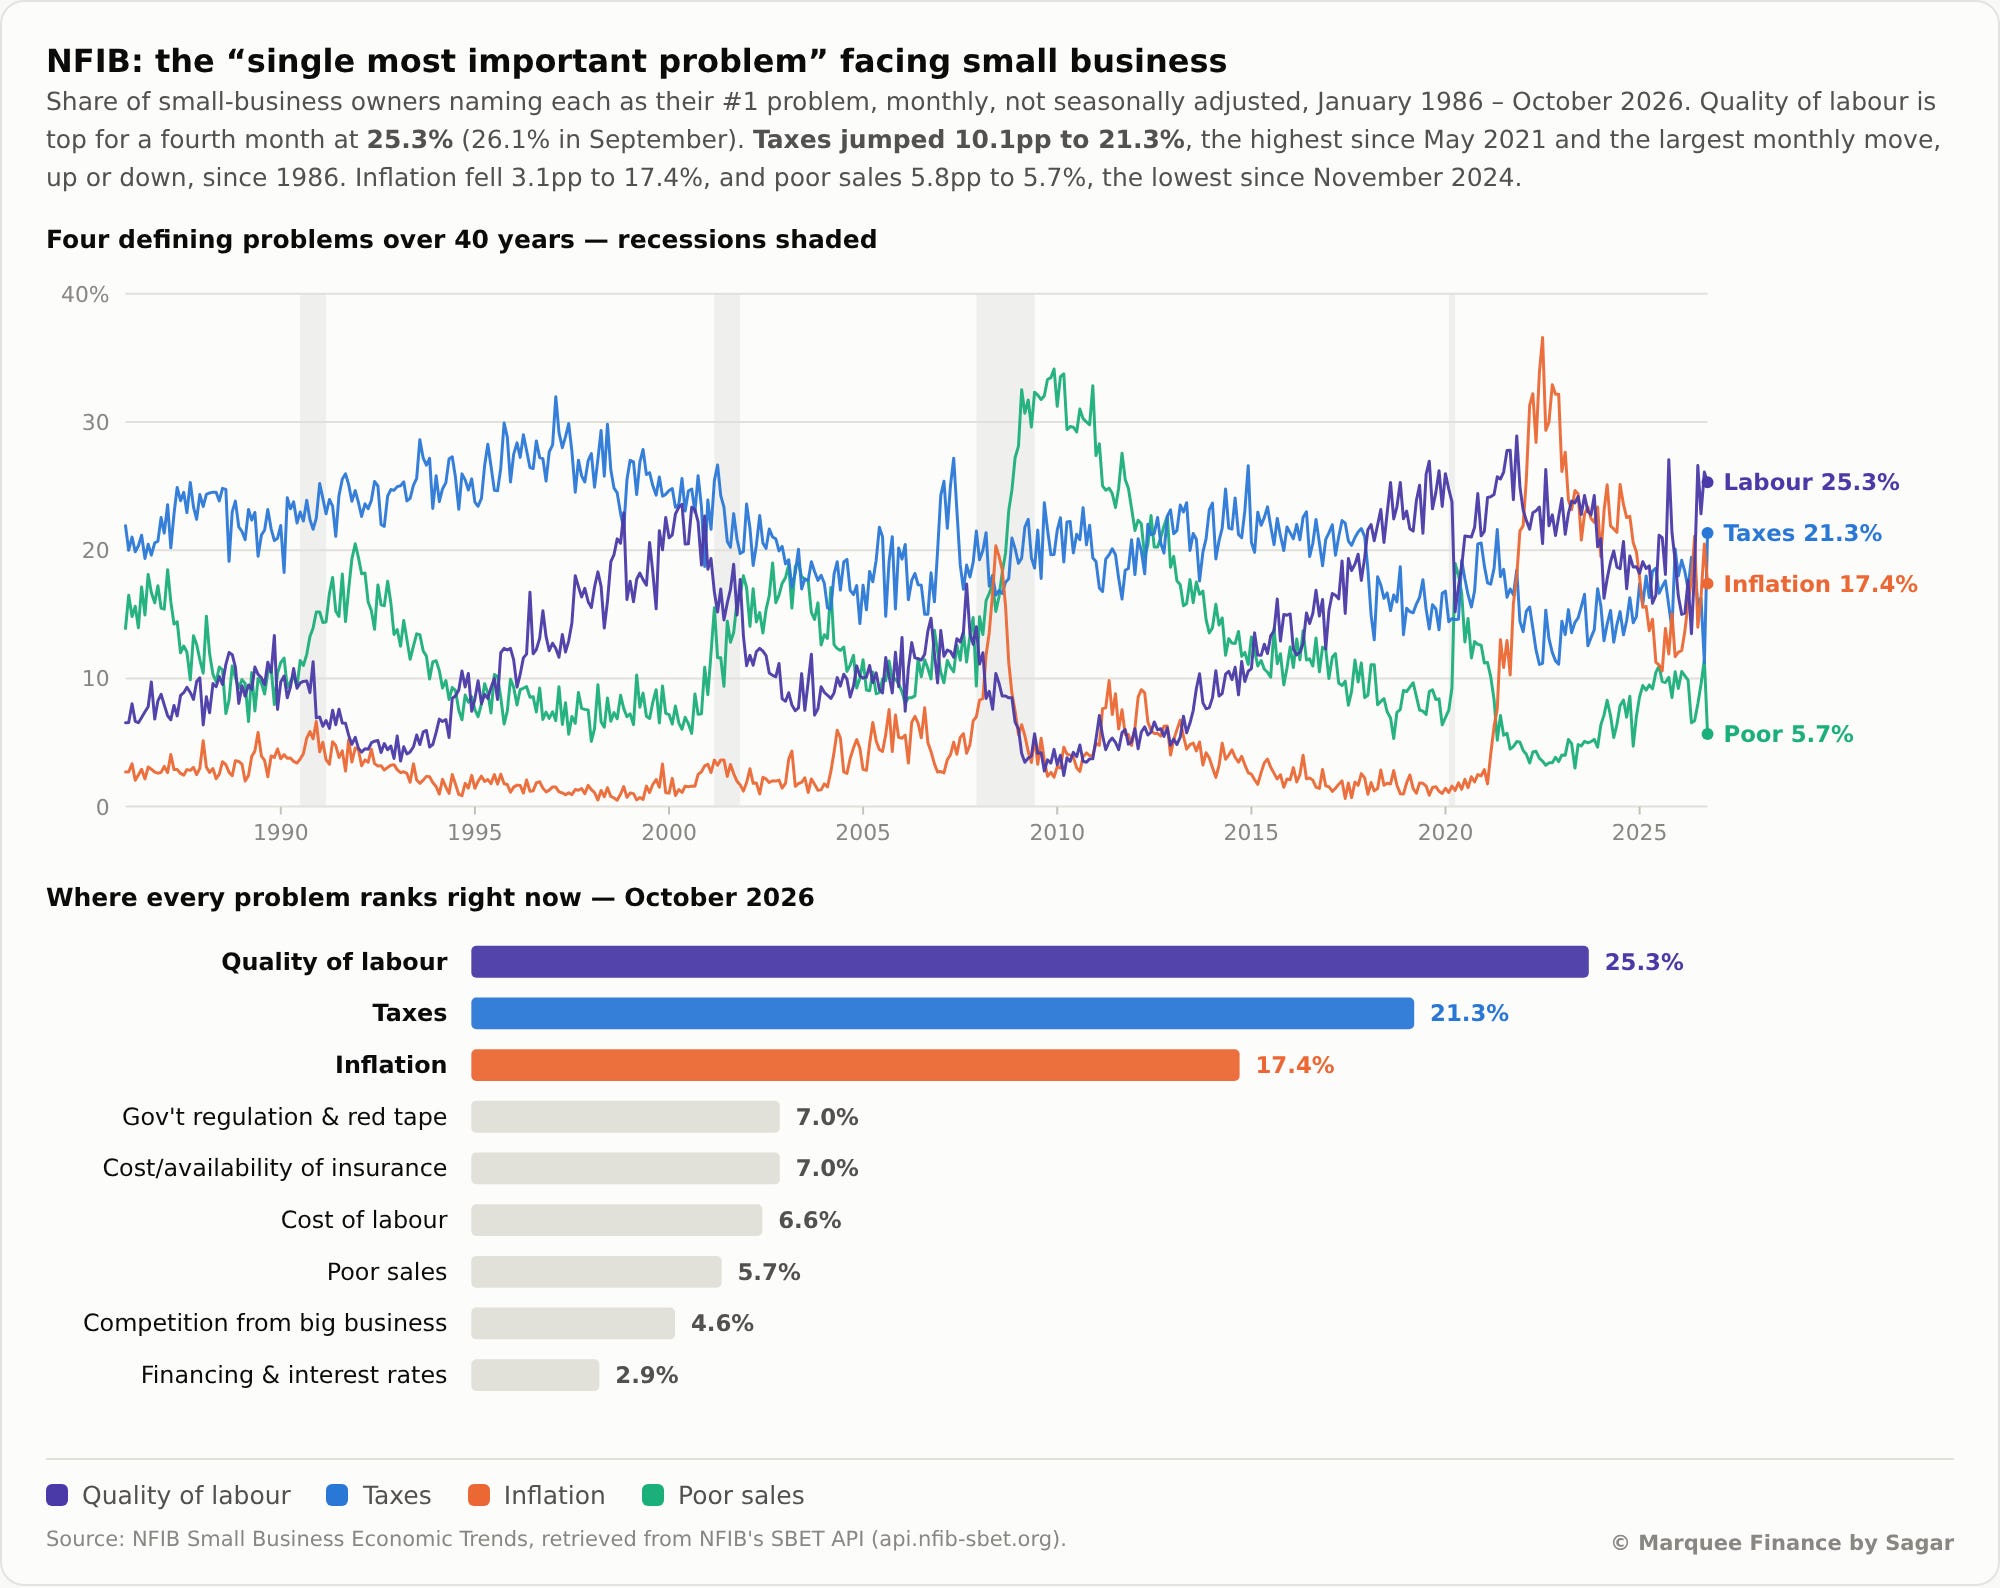
Small businesses are reeling from these problems because of Trump administration policies (immigration, tariffs and war), and we don’t believe a respite is in sight in the near term.
Equities!
Bulls worked hard this week to drive SPX higher.
Nonetheless, we still closed below the key